• Here’s why investors should be concerned about Austal shares moving forward

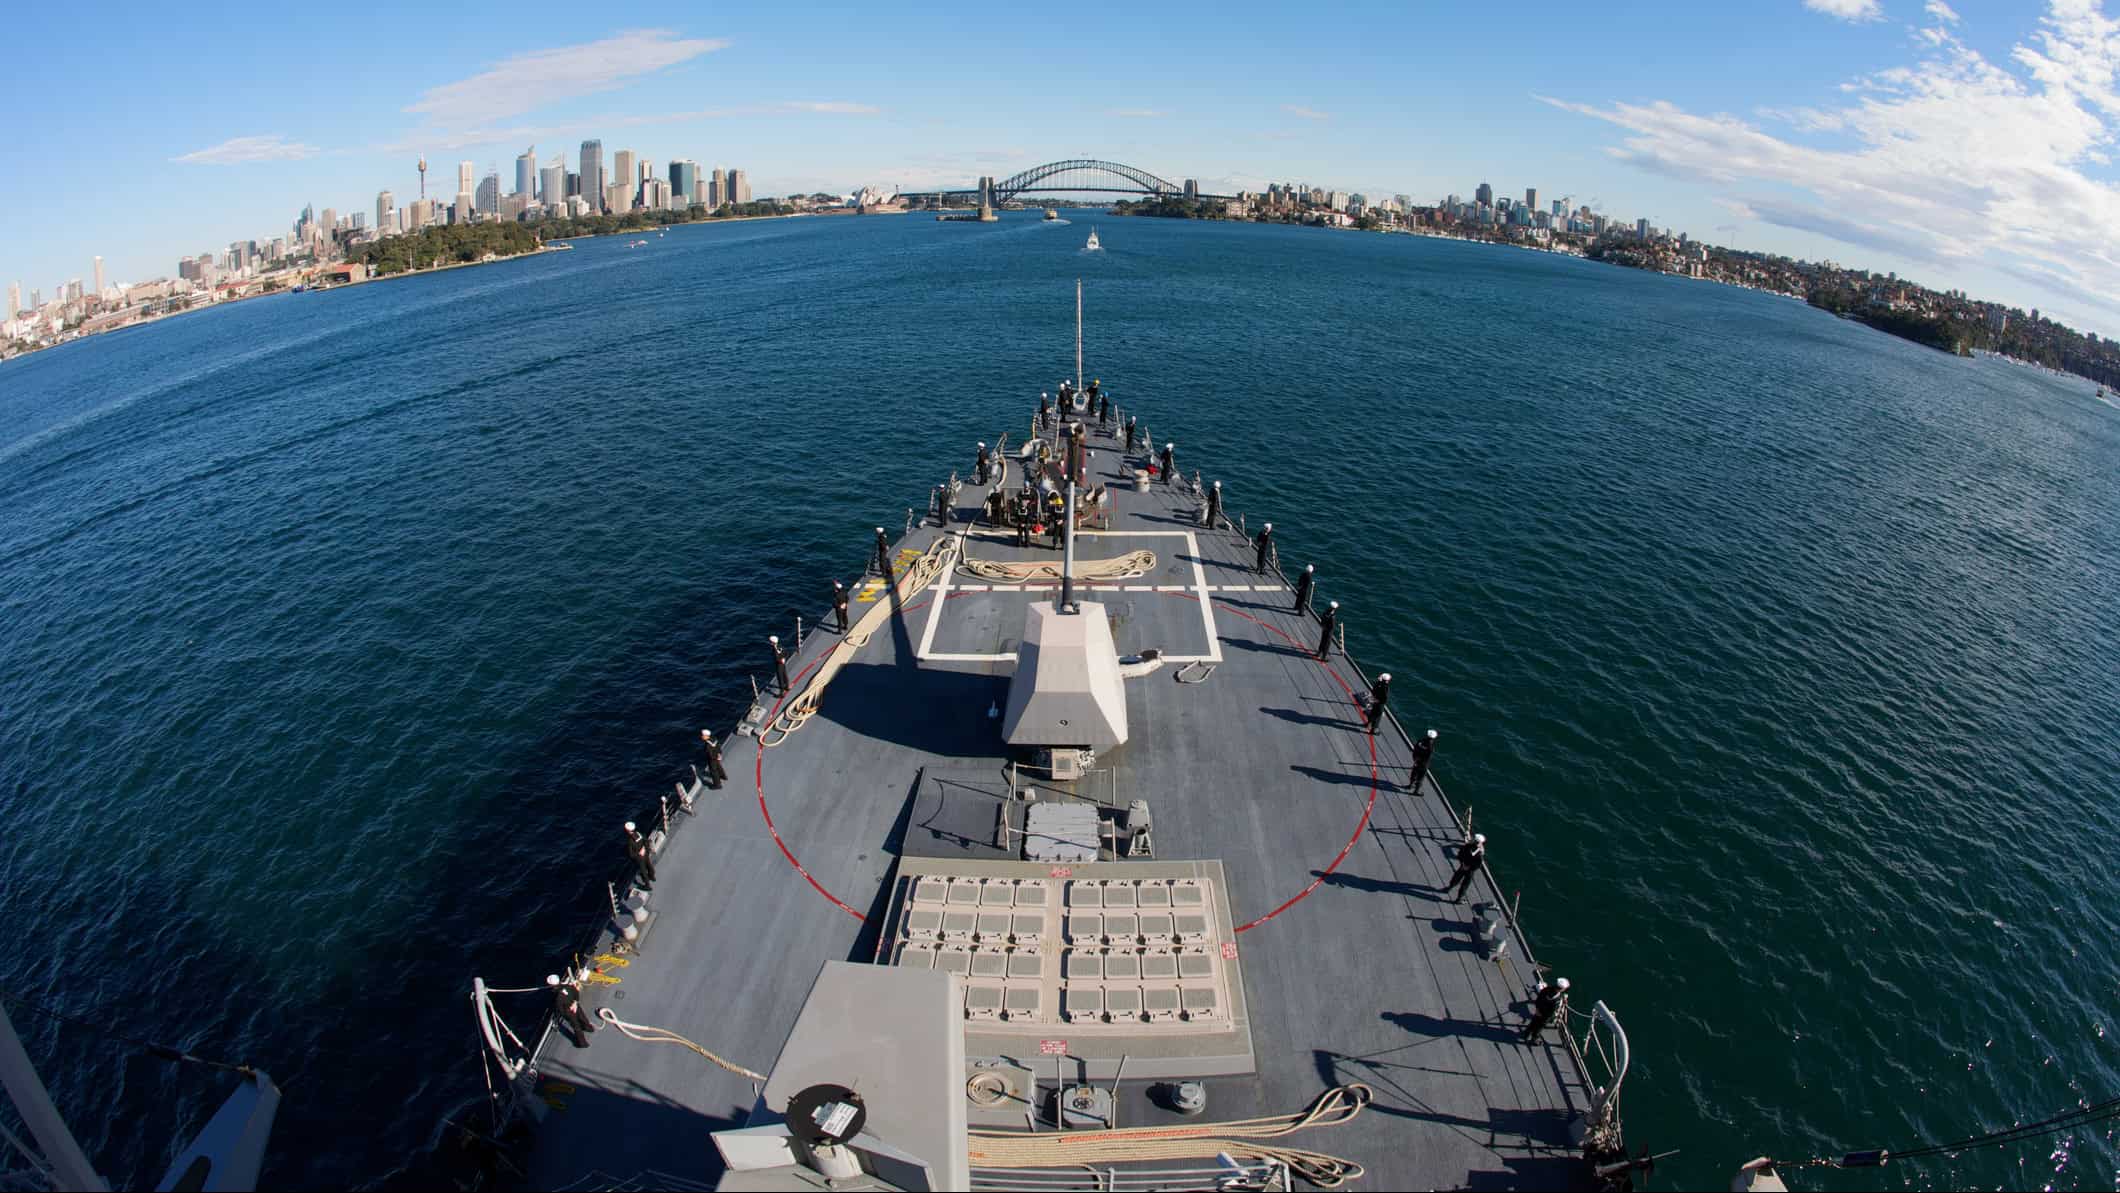
    A U.S. Naval Ship (DDG) enters Sydney harbour.

    ASX defence stocks like Austal Ltd (ASX: ASB) have ridden a rollercoaster over the last 12 months.

    Austal is an Australian-based shipbuilder that specialises in the design, construction, and support of defence and commercial vessels globally.  

    Austal’s products include naval vessels, defence surface warfare combatants, high-speed support vessels, patrol boats for law enforcement, offshore vessels, as well as passenger and vehicle ferries.

    The company also installs and maintains vessel command and control systems, communication and radar technology, and information management systems.

    A rollercoaster for Austal shares

    Global conflict and defence spending sent Austal shares soaring in early 2026.

    In January, Austal shares hit all time highs of almost $9 per share.

    However since then, they have been on a steady decline, closing last week at $4.19.

    This drop represents almost a 40% dip year to date.

    Unfortunately for investors looking to buy the dip, a new report from Bell Potter indicates there are potential headwinds emerging for Austal shares.

    Complexity lies ahead

    According to a new report from Bell Potter, Austal has a record $17.7 billion order book, giving it strong long-term growth.

    But delivering all this work won’t be easy. Bell Potter highlights three main risks:

    • Austal is starting several new steel shipbuilding projects at the same time in new facilities, which could lead to early operational problems and delays.
    • Some contracts are particularly challenging. For example, the T-AGOS ships have a very complex design that could require costly rework, while the OPC program is under government scrutiny, which could create additional risks and pressure on profits.
    • Austal plans to significantly expand its operations in Henderson over the next 12–18 months. If it struggles to hire enough skilled workers, construction of the LCM and LCH vessels could be delayed.

    In simple terms, the company has plenty of work lined up, but its biggest challenge is executing it well.

    If it can avoid delays, cost overruns, and labour shortages, the large order book should translate into strong earnings. If not, profits could come under pressure even though demand remains high.

    Tailwinds for Austal shares

    On the positive side, Bell Potter highlighted that Austal is well positioned to benefit from major increases in defence spending in both the US and Australia.

    Its shipyards are considered strategically important to expanding naval fleets, giving the company a long-term pipeline of work and strong growth opportunities over the coming decades.

    In Australia, ASB holds strategic importance to the shipbuilding industrial base with its appointment by the CoA as Strategic Shipbuilder under the SSA.

    The SSA guarantees a continuous, decades-long pipeline of work, estimated by management at over A$20b over 20 years, providing the stability needed to attract, train, and retain a highly skilled local workforce.

    Price target downgrade for Austal shares

    Based on this guidance, the team at Bell Potter has downgraded its share price target for Austal shares to $4.10 (previously $6.30).

    This indicates that the current share price is slightly above fair value.

    The broker has retained its hold recommendation on Austal shares.

    Although the valuation/growth arithmetic appears attractive, we believe we are entering a period of elevated risks as ASB ramps up several shipbuilding programs.


    The post Here’s why investors should be concerned about Austal shares moving forward appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Austal right now?

    Before you buy Austal shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Austal wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 16 June 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Aaron Bell has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Why this incredible ASX 200 tech stock could rise 27%

    Happy work colleagues give each other a fist pump.

    There are a lot of options for investors to choose from in the tech sector.

    But one of the best according to Bell Potter could be the ASX tech stock in this article.

    Which ASX 200 tech stock?

    The stock that Bell Potter is tipping as a top buy is location technology company Life360 Inc. (ASX: 360).

    The broker is bullish on the company’s outlook and sees next month’s quarterly update as a potential catalyst for its share price. It explains:

    Life360 will report its 2Q2026 result on 11th August and we see it as a potential catalyst for the share price for three key reasons: 1. We expect MAU growth to rebound to 4.3m – consistent with 2Q2025 – if not higher (VA consensus is 4.6m) which importantly will imply an exit run-rate of close to 5m given the Android issues which persisted into April and even May; 2. We expect paying circle growth to be strong again at c.155k which is notably above VA consensus of c.135k and even see upside risk to our forecast closer to the 1Q2026 result of 202k;

    And 3. If paying circle growth is >155k then we see potential for a further upgrade to 2026 revenue and EBITDA guidance as paying circle growth is obviously the key driver of subscription revenue. Note also that, if MAU growth is around or above our forecast then we would expect Life360 to maintain its 2026 MAU guidance of 17-20% growth which we would regard as positive given it implies growth of at least 5m in Q3 and Q4.

    Life360 shares tipped to rise strongly

    According to the note, Bell Potter has retained its buy rating on the ASX 200 tech stock with an improved price target of $35.00 (from $33.00).

    Based on its current share price of $27.46, this implies potential upside of 27% for investors over the next 12 months.

    Commenting on its investment thesis, the broker said:

    We have rolled forward our EV/EBITDA valuation by a year – so that 2027 is now the base – given we are now in 2H2026. We apply a 25x multiple compared to 30x previously. We have also modestly reduced the WACC we apply in the DCF from 9.6% to 9.5% given the prospect of a good Q2 result and potential guidance upgrade. The net result is a 6% increase in our target price to $35.00 which is >15% premium to the share price so we maintain our BUY recommendation.

    Life360 is our key pick amongst the large tech stocks we cover based on quality, valuation and potential catalysts. We note the stock looks reasonable value on a 2027 EV/EBITDA multiple of c.23x versus the FY27 EV/EBITDA of Technology One (which has a September year end) of c.26x.

    The post Why this incredible ASX 200 tech stock could rise 27% appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Life360 right now?

    Before you buy Life360 shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Life360 wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 16 June 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor James Mickleboro has positions in Life360. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Life360. The Motley Fool Australia has positions in and has recommended Life360. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

  • Why BHP and these ASX shares could be strong buys this week

    Smiling man sits in front of a graph on computer while using his mobile phone.

    Are you on the hunt for new portfolio additions in July? If you are, it could be worth hearing what analysts are recommending this week, courtesy of The Bull.

    Here are three ASX shares that have been named as buys:

    BHP Group Ltd (ASX: BHP)

    Catapult Wealth thinks that investors should be considering this mining giant. It has named BHP shares as a buy this week.

    The wealth management firm highlights strong copper prices, a robust balance sheet, and an attractive dividend yield as reasons to buy. It said:

    The global miner holds dominant positions in iron ore and copper and is leveraged to increasing demand during the energy transition. A review of the Jansen stage 2 potash project in Canada resulted in a cost blowout of about $US2 billion to $US6.9 billion. Despite the Jansen impairment and the risk of industrial action at iron ore operations in the Pilbara region of Western Australia, near term earnings momentum remains strong.

    Elevated copper prices and strong iron ore prices supported performance in full year 2026. The balance sheet remains robust with low net debt, while a recent dividend yield above 3 per cent adds income appeal. BHP offers cyclical upside and long term growth exposure to copper.

    Dexus Convenience Retail REIT (ASX: DXC)

    Another ASX share that is rated positively is Dexus Convenience Retail REIT.  It offers service station and convenience retail assets exposure.

    Sanlam Private Wealth has named its shares as a buy, highlighting its cheap valuation and big dividend yield. It said:

    This real estate investment trust owns service stations and convenience retail assets, mostly on Australia’s eastern seaboard. The fund’s portfolio was valued at about $760 million on December 31, 2025. The company was recently trading at a significant discount to net tangible assets (NTA) and was yielding about 8 per cent. The trust has an attractive development pipeline, modest debt and recently increased its buy-back target.

    Importantly, the NTA is supported by recent asset sales of 1.5 per cent above valuation. Recently announced capital gains tax changes make the company’s assets appealing to self-managed super funds looking for reliable income generating assets. DXC is a solid defensive play in the current environment.

    ResMed Inc. (ASX: RMD)

    The team at Catapult Wealth is also bullish on this sleep disorder treatment company. This week, it has named ResMed shares as a buy.

    The wealth management firm likes the company due to its defensive qualities and positive growth outlook. It said:

    ResMed is a global leader in sleep apnoea devices and digital health platforms, benefiting from strong structural demand and resilient clinical positioning. Despite the progression in GLP-1 therapies for treating sleep apnoea, ResMed’s CPAP (continuous positive airway pressure) treatments remain superior at this point in time. RMD continues to offer appealing growth, income and defensive healthcare exposure.

    The post Why BHP and these ASX shares could be strong buys this week appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP Group right now?

    Before you buy BHP Group shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 16 June 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor James Mickleboro has positions in ResMed. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended ResMed. The Motley Fool Australia has positions in and has recommended ResMed. The Motley Fool Australia has recommended BHP Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.