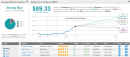
The Vocus Group Ltd (ASX: VOC) share price has been an impressive performer over the last two and a half months.
Since the specialist fibre and network solutions provider’s shares fell to a 52-week low of $1.80 in late March, they have rallied a massive 73% to trade at $3.13 today.
Is it too late to buy Vocus shares?
The Vocus share price can still go a lot higher from here according to one leading broker.
A note out of Goldman Sachs this morning reveals that its analysts have reiterated their buy rating and $3.85 price target on the company’s shares.
This price target implies potential upside of 23% for its shares over the next 12 months.
Why is Goldman Sachs bullish?
According to the note, the broker was pleased to see Vocus reiterate its FY 2020 guidance and announce the refinancing of its debt on Thursday.
Vocus revealed that it expects its FY 2020 earnings before interest, tax, depreciation, and amortisation (EBITDA) to be in the range of $359 million to $369 million.
This compares to the EBITDA of $356 million that Goldman was expecting. It believes this is reflective of the resilience of telecom earnings.
Overall, the broker remains positive on its outlook and also on its valuation in comparison to rival TPG Telecom Ltd (ASX: TPM).
Goldman commented: “We stay Buy on Vocus with this update removing two key investor issues (i.e. refinancing & lack of guidance commentary) and helping to de-risk our positive investment view.”
“This is based on: (1) improving Enterprise earnings outlook, with a meaningful opportunity to partner with NBN Co.; (2) favorable valuation (vs. TPM and history); (3) significant infrastructure asset base, which we see as attractive in a low-rate environment,” it concluded.
Should you buy Vocus shares?
While my preference in the telco space remains Telstra Corporation Ltd (ASX: TLS), I think Vocus is a great option as well.
Times have been hard for the company over the last few years, but it finally appears to be on track now to deliver solid growth over the coming years. This could lead to the Vocus share price outperforming over the medium term.
And here are more top shares which analysts have just given buy ratings to…
NEW! 5 Cheap Stocks With Massive Upside Potential
Our experts at The Motley Fool have just released a FREE report detailing 5 shares you can buy now to take advantage of the much cheaper share prices on offer.
One is a diversified conglomerate trading over 30% off it’s all-time high, all while offering a fully franked dividend yield of over 3%…
Another is a former stock market darling that is one of Australia’s most popular and iconic businesses. Trading at a significant discount to its 52-week high, not only does this stock offer massive upside potential, but it also trades on an attractive fully franked dividend yield of almost 4%.
Plus, this free report highlights 3 more cheap bets that could position you to profit in 2020 and beyond.
Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares.
But you will have to hurry because the cheap share prices on offer today might not last for long.
As of 2/6/2020
More reading
- 5 things to watch on the ASX 200 on Friday
- The 10 shares that significantly move the ASX 200 index
- Telstra shares and 2 other ASX companies to buy in a low-interest rate world
- Why I would buy these outstanding ASX 50 shares right now
- ASX 200 hits 6,000 points: Westpac provide AUSTRAC update, Vocus reaffirms guidance
Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Telstra Limited. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
The post Top broker tips the Vocus share price to zoom higher appeared first on Motley Fool Australia.
from Motley Fool Australia https://ift.tt/2UcSuVw