Category: Stock Market

  • Biotron share price rockets 38% on COVID trial results

    a group of medical researchers stands side by side with each other wearing white coats in their research laboratory with scientific equipment in the background.a group of medical researchers stands side by side with each other wearing white coats in their research laboratory with scientific equipment in the background.

    Those that believe that COVID-19 is yesterday’s news should look at the Biotron Limited (ASX: BIT) share price today.

    Shares in the small cap biotech jumped 37.5% to 9.9 cents each after reporting positive COVID-19 animal trial results today.

    The company said that its lead clinical drug BIT225 protected mice that have SARS-CoV-2 from severe disease.

    Bitotron share price jumps on more challenging test results

    This test was trickier than an earlier one the company conducted. In the latest test, the mice were infected by SARS-CoV-2 up to 48 hours before being treated with BIT225.

    In the earlier study, the mice were given BIT225 12 hours before being infected by SARS-CoV-2.

    The second trial was more challenging as it had a higher hurdle to demonstrate the efficacy of the drug, according to Bitotron.

    Why this animal trial matters

    “The results are important as they provide key information that will assist in determining the dosing regimen for BIT225 in planned human clinical studies,” said the company in its ASX statement.

    “The results further extend the robust in vivo data package that shows statistically and clinically significant efficacy of BIT225 in both treatment and prevention in murine models of COVID-19.”

    Biotron’s management believes the effectiveness of BIT225 to treat and prevent severe cases of the highly contagious disease sets it apart from other treatments.

    In fact, Biotron claims that this characteristic is a requirement for successful product development in this therapeutic area.

    Details of Biotron’s latest mice trial

    In all studies, BIT225 was tested in a human-adapted COVID-19 mouse model (K18-hACE2) that is routinely used to assess the ability of drugs to target SARS-CoV-2 and treat COVID-19 disease.

    There were five mice in each of the pre-dose and post-dose groups. There was also a control group with the same number of mice.

    In the groups that were treated with BIT225, all but one remained healthy and continued to gain weight as per age expectations through to Day 12 when the study was terminated. One of the five mice in the post-dose group died on Day 11 of the trial.

    In the control group made up of untreated mice, all lost weight and died by day eight of the study. The company noted that there was less weight gain if BIT225 treatment was delayed. But the trend lines are statistically similar regardless of when the drug was used.

    Next catalyst for the Biotron share price

    BIT225 was tested in a human-adapted COVID-19 mouse model (K18-hACE2) that is routinely used to assess the ability of drugs to target SARS-CoV-2 and treat COVID-19 disease.

    Bitotron has submitted a proposal to the US Food and Drug Administration to conduct a human clinical trial to assess the efficacy of BIT225 for the treatment of COVID-19.

    The application was made under the Coronavirus Treatment Acceleration Program and Biotron’s management is expecting a response soon.

    The post Biotron share price rockets 38% on COVID trial results appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Brendon Lau has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/kenIrAX
  • The CBA share price was the worst performer of the ASX 200 big banks in April. What happened?

    A girl wearing yellow headphones pulls a grimace, that was not a good result.A girl wearing yellow headphones pulls a grimace, that was not a good result.

    The S&P/ASX 200 Index (ASX: XJO) didn’t have a great month in April. Last month saw the flagship index go backwards by about 0.86%, not including the nasty falls we have seen today. But it was an even bleaker month for the Commonwealth Bank of Australia (ASX: CBA) share price. April saw CBA shares fall from $105.77 a share to $103.88, a fall of 1.8% or so, more than twice the fall of the ASX 200.

    But what might stick even deeper in CBA investors’ craw is that CBA was the worst-performing ASX 200 big four bank share. CBA investors have long enjoyed the bank’s reputation as the best performing ASX bank share. But that was certainly not the case last month.

    Take the National Australia Bank Ltd (ASX: NAB) share price. NAB shares ended April in the green with a rise of 0.87%. Westpac Banking Corp (ASX: WBC) shares didn’t do quite as well as that, but fell less than CBA did. It was a similar story with Australia and New Zealand Banking Group Ltd (ASX: ANZ).

    So after a period of topping out the ASX bank sector, what went wrong with CBA shares last month?

    Why was the CBA share price sold in April?

    One possible explanation for this scenario comes from reporting in the Australian Financial Review (AFR) today. The report quoted analysis from investment bank and broker JP Morgan. JP Morgan noted that NAB is currently the “only big four bank stock that domestic fund managers have a ‘well held’ position in”. This, the broker suggests, might mean that “investors have less conviction in the other three majors, which rank as ‘underheld’”.

    “This cooling on the banks follows a period of particularly strong performance, with the sector outperforming the ASX 200 and MSCI World Banks in the year-to-date,” the report quotes JP Morgan’s Jason Steed.

    But many ASX brokers have been warning about possible falls in the value of the CBA share price for a while now. Just this week, broker Morgans has retained a ‘reduce’ rating on CBA shares. That came with a 12-month share price target of just $77. Part of Morgans’ pessimism on CBA shares is the view that they are overvalued at current levels.

    So if the various commentary on CBA is to be believed, perhaps the bank might have a few more months of disappointing performance in front of it yet. But we shall have to wait and see what happens.

    At the current CBA share price, this ASX 200 bank share has a market capitalisation of $175.33 billion. That comes with a dividend yield of 3.65%.

    The post The CBA share price was the worst performer of the ASX 200 big banks in April. What happened? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in CBA right now?

    Before you consider CBA, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and CBA wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has positions in JPMorgan Chase and National Australia Bank Limited. JPMorgan Chase is an advertising partner of The Ascent, a Motley Fool company. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Westpac Banking Corporation. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/GVhyqdv

  • Worried about inflation? Here’s what Warren Buffett says Berkshire Hathaway is doing

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Legendary share market investing expert and owner of Berkshire Hathaway Warren Buffett

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Inflation is on the minds of investors, policymakers, and everyday Americans. We can feel it at the pump, at the grocery store, the post office, and even the barbershop. Since inflation is higher than the rate of economic growth, the real gross domestic product for the first quarter of 2022 decreased by 1.4% year over year. If we get another negative reading for the second quarter, the US economy will officially be in a recession.

    Both Warren Buffett and Charlie Munger spoke about inflation at Berkshire Hathaway‘s (NYSE: BRK.A) (NYSE: BRK.B) annual shareholders’ meeting on Saturday. Here’s what the longtime chairman and vice chairman said and how they’re positioning Berkshire to ride out the storm.

    An unavoidable consequence

    Buffett and Munger both spoke negatively about the state of the economy due to inflation and how it is largely a result of loose fiscal and monetary policy. This policy artificially inflated demand and effectively caused a supply/demand imbalance — the cure for which was rising prices to try and lower demand. And now, the remedy seems to be raising interest rates to try and reduce demand. “We are seeing an unleashing of the fact that we just mailed a lot of money one way or another,” said Buffett.

    However, Buffett and Munger view inflation as a necessary consequence to get the US out of what could have been a COVID-19 induced depression.

    “We’ve had a lot of inflation, and it was almost impossible not to have it if you’re going give out the kind of money we gave out. And it’s probably a good thing we did it, in fact, I think at one point when the Federal Reserve was creating the money, if they hadn’t done it our lives would be worse, a whole lot worse. Now that was an important decision,” said Buffett.

    In another exchange, Munger said, “It happened on a scale this time that we’ve never seen before. Those checks are just mailed out to everybody who claimed to have a business and claimed to have employees. They probably drowned the country in money for a while, and as you [Buffett] say, they probably had to do it.”

    “In my book, Jay Powell [chair of the US Federal Reserve] is a hero,” Buffett responded. “It’s very simple, he did what he had to do.”

    Find value wherever it’s available

    One way of growing wealth during inflationary times is looking for opportunities that aren’t otherwise available. The trick is having plenty of experience looking for those opportunities in other economic conditions, too. “We depend on mispriced businesses through mechanisms where we aren’t responsible for the mispricing of them,” Buffett said.

    Buffett surprised investors when he disclosed a roughly 9.5% stake in Activision Blizzard. The stake is worth about $6.2 billion as of Friday’s close. Buffett owned about $1 billion of Activision before Microsoft announced it would acquire it for $95 a share. Buffett then increased Berkshire’s position as a classic arbitrage opportunity under the assumption that Microsoft is a reliable buyer and would come through on the deal. That arbitrage opportunity is sizable, considering Activision Blizzard’s stock is currently $75.60 per share.

    Buffet’s Activision Blizzard play is merely an old-school way of finding value in a challenging market. However, regular investors should probably steer clear of these kinds of investments, as the deal isn’t based on fundamentals and could fall through. You don’t want to end up owning a company you don’t understand and didn’t really want in the first place.

    So what can you do?

    Learn from Buffett’s actions

    It’s all good and well to say that inflation is unavoidable. But the real question many investors are probably wondering about is how to position their portfolios for prolonged inflation.

    First off, it’s important to remember that economic cycles are simply par for the course in a long investing career. Whether inflation is the cause of a sell-off or not is secondary. The bigger takeaway is that a bear market can create life-changing wealth for investors in companies with bright futures, positive cash flows, and durable balance sheets.

    What Berkshire is showing through its actions is an increased buying appetite that we haven’t seen in years, which indicates Berkshire is finding value — mainly in the energy sector. In less than a year, oil and gas went from a minor allocation to a major one. Berkshire’s Chevron holding has pole-vaulted to its third-largest position, while Occidental Petroleum has been a top 10 holding since Berkshire increased its stake in February and March. Berkshire also took a stake in HP this year, and its acquisition of insurer Alleghany shows its classic value stock bent.

    Chevron is known for its industry-leading balance sheet and a low cost of production that allows it to reach breakeven free cash flow even when oil is in the low $40s per barrel. Meanwhile, Occidental Petroleum is a much more aggressive spender and has a higher breakeven than Chevron. But its relatively high capital expenditures have paid off now that oil and gas prices are at eight-year highs. Meanwhile, Berkshire’s other major positions are in diversified large companies like Apple and Coca-Cola, which is one of the most recession-resistant and reliable sources of passive income on the market.

    Treading carefully in a challenging market

    All told, Buffett’s actions show that Berkshire is finding value in the market, more value than it has found in years. But that Berkshire isn’t just buying the dip on any company. It is selectively buying companies that are contributors to inflation (upstream producers like Occidental) or have relatively reliable cash flows and inexpensive valuations (like Chevron and HP).

    For investors who don’t manage billions of dollars in assets, sticking with unstoppable stocks you’ll want in your corner if the market crashes can be a great way to rest easy at night and endure the gauntlet of a bear market.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Worried about inflation? Here’s what Warren Buffett says Berkshire Hathaway is doing appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Daniel Foelber has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Activision Blizzard, Apple, Berkshire Hathaway (B shares), and Microsoft. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended the following options: long January 2023 $200 calls on Berkshire Hathaway (B shares), long March 2023 $120 calls on Apple, short January 2023 $200 puts on Berkshire Hathaway (B shares), short January 2023 $265 calls on Berkshire Hathaway (B shares), and short March 2023 $130 calls on Apple. The Motley Fool Australia has recommended Activision Blizzard, Apple, and Berkshire Hathaway (B shares). The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.


    from The Motley Fool Australia https://ift.tt/l4yDAdn
  • The top 2 cryptos of April unmasked

    Two young boys, identical twins, dressed in suave business suits and ties wear sparkly masks over their eyes and pout at the camera.

    Two young boys, identical twins, dressed in suave business suits and ties wear sparkly masks over their eyes and pout at the camera.

    Cryptos didn’t have the best of months in April.

    In fact, running our slide rule over the data from CoinMarketCap, only four of the top 100 cryptos by market cap returned more than 1% to investors holding the tokens last month.

    Meanwhile, 90 of the top 100 virtual coins finished April in the red.

    Like we said, not a great month, overall.

    Bitcoin sets the crypto tone for April

    Bitcoin (CRYPTO: BTC) set the broader tone, losing 17% over the 30-day period.

    Bitcoin and the rest of the crypto market came under selling pressure as investors repositioned their holdings ahead of a series of expected interest rate hikes from the US Federal Reserve and other leading central banks.

    That repositioning also saw the tech-heavy US Nasdaq shed 14% last month as investors shy away from risk assets.

    With that gloom out of the way, here are the two best performing cryptos of April.

    This altcoin gained 64% last month

    The second best crypto to have held during April is Kyber Network Crystal (CRYPTO: KNC).

    Kyber kicked off April trading for US$3.14 and rounded off the month worth US$5.16 for a gain of 64%.

    Indicative of the continuing volatility in the crypto world, Kyber traded as low as US$2.88 last month and as high as $US5.72 on 28 April, which also marked its all-time high.

    If you’re not familiar with Kyber, CoinMarketCap tells us it’s “a hub of liquidity protocols that aggregates liquidity from various sources to provide secure and instant transactions on any decentralised application (DApp)”.

    Kyber has lost some ground in the first days of May, currently trading for US$4.56. That gives the crypto a market cap of US$880 million and ranks it as number 88 among the top 100 tokens.

    Which brings us to…

    April’s top crypto performer

    The best performing crypto to have held in April is ApeCoin (CRYPTO: APE).

    ApeCoin was trading for US$12.79 early on 1 April and finished the month trading for US$24.21, an impressive gain of 89%.

    Also highly volatile, ApeCoin traded for as low as US$10.57 in April and reached highs of US$26.91.

    The first two days of May haven’t been as kind to investors in ApeCoin, with the token retracing to US$17.08 at the time of writing. That’s down 57% from the record highs hit on 17 March.

    So, what is ApeCoin?

    According to CoinMarketCap, “ApeCoin is an ERC-20 governance and utility token used within the APE Ecosystem to empower and incentivize a decentralized community building at the forefront of web3.”

    At the current price, ApeCoin has a market cap of US$4.8 billion, making it the number 29 crypto in virtual circulation.

    The post The top 2 cryptos of April unmasked appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ApeCoin right now?

    Before you consider ApeCoin, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ApeCoin wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Bitcoin. The Motley Fool Australia has positions in and has recommended Bitcoin. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/fZiYolh

  • Own ANZ shares? Here’s what to expect from the bank’s half-year results

    A male sharemarket analyst sits at his desk looking intently at his laptop with two other monitors next to him showing stock price movements

    A male sharemarket analyst sits at his desk looking intently at his laptop with two other monitors next to him showing stock price movements

    All eyes will be on Australia and New Zealand Banking Group Ltd (ASX: ANZ) shares this week when the banking giant releases its half-year results.

    Ahead of the release on Wednesday, let’s take a look at what the market is expecting.

    What is the market expecting from ANZ’s first half results?

    According to a note out of Goldman Sachs, its analysts are expecting the market to be focusing a lot on the bank’s margins.

    In light of this, investors may want to pay close attention to ANZ’s net interest margin (NIM), which the broker expects to come in at 1.56%. This will be down 9 basis points versus the second half of FY 2021.

    Goldman also suggests investors pay “attention to management expectation around its leverage to higher cash rates.”

    What about ANZ’s profits and dividends?

    The note reveals that Goldman expects ANZ to deliver a pre-provisioning operating profit of $4,270 million and cash earnings of $2,971 million for the half. This will be down 4.2% and 7.4%, respectively, from the second half of FY 2021.

    Anything materially better (or worse) than these estimates could have a say in the direction ANZ shares take on Wednesday.

    Finally, the broker has pencilled in a fully franked interim dividend of 72 cents per share for the period. This will be up 2.9% on the prior corresponding period and flat on ANZ’s final dividend of FY 2021.

    Are ANZ shares in the buy zone?

    Goldman Sachs sees plenty of value in ANZ shares at the current level. The note reveals that its analysts have a buy rating and $32.74 price target on the bank’s shares.

    Based on the current ANZ share price of $27.32, this implies a potential return of 20% for investors over the next 12 months before dividends. This stretches to over 25% if you include them.

    The post Own ANZ shares? Here’s what to expect from the bank’s half-year results appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ANZ right now?

    Before you consider ANZ, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ANZ wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/AiVEwfa

  • Why is the Webjet share price beating the ASX 200 today?

    A little boy in flying goggles and wings rides high on his mum's back with blue skies above.A little boy in flying goggles and wings rides high on his mum's back with blue skies above.

    Bullish updates from travel-related ASX shares are putting the wind beneath the wings of the Webjet Limited (ASX: WEB) share price today.

    The Webjet share price is up 1.16 at the time of writing, to $6.10, while the S&P/ASX 200 Index (ASX: XJO) is diving 1.24%.

    A trading update from Qantas Airways Limited (ASX: QAN) is exciting Webjet shareholders. The airline reported a significant rebound in free cash flow. That’s thanks to strong demand for travel following the easing of international border restrictions.

    Webjet share price riding higher on Qantas’ jetstream

    The pickup in sales prompted Qantas to forecast a return to profitability. The airline still expects underlying earnings before interest and tax for FY22 to be in the red. However, underlying earnings before interest, tax, depreciation and amortisation (EBITDA) is tilled to come in at between $450 million and $550 million.

    The improved cash position plus the return of the travel bug was enough to convince Qantas to purchase 12 Airbus A350s. The acquisition is part of its Project Sunrise program. The new aircraft will enable Qantas to offer direct flights to Europe and the United States from any city in Australia.

    “The board’s decision to approve what is the largest aircraft order in Australian aviation is a clear vote of confidence in the future of the Qantas Group,” said Qantas CEO Alan Joyce.

    “The phasing of this order means it can be funded within our debt range and through earnings, while still leaving room for shareholder returns in line with our financial framework.”

    More good news for the Webjet share price

    What’s good for the goose is good for the gander. Investors are betting that the pent-up demand for international travel will be a tailwind for the Webjet share price too.

    Better still, Qantas isn’t the only one in the sector that provided an upbeat assessment for the industry.

    The Helloworld Travel Ltd (ASX: HLO) share price is also taking off today after the company released its quarterly update.

    Earnings jump as travel rebounds

    The travel agent said that total transaction value (TTV) in the recent quarter jumped 60% over the same time last year. TTV for the quarter ending 31 March 2022 was $419 million.

    Revenue also increased by 52% to $22.8 million. While EBITDA loss narrowed to $1.9 million from $4 million over the period.

    “International travel has resumed, and confidence is returning as travelers book with longer lead times and higher average spend,” said Helloworld in its ASX statement.

    “Based on retail, wholesale and inbound booking intakes across the first three months of 2022 we expect a rapid improvement in revenues across the coming months.”

    Clear skies ahead

    But there was another big move signalling that international travel is about to make a big comeback. Regional Express Holdings Ltd (ASX: REX) announced its intention to partner with Delta Air Lines.

    The airlines are aiming to sign a deal that would allow reciprocal ticketing and baggage services. The Rex and Delta connectivity is due to commence in the third quarter of 2022.

    There are high hopes that all the good news will translate to further gains for Webjet. The Webjet share price has jumped over 20% over the past year.

    The post Why is the Webjet share price beating the ASX 200 today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Webjet right now?

    Before you consider Webjet, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Webjet wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brendon Lau has positions in Webjet Ltd. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Helloworld Limited. The Motley Fool Australia has positions in and has recommended Helloworld Limited. The Motley Fool Australia has recommended Webjet Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/Wnm6vBc

  • What happened with the Bitcoin price in April?

    A bitcoin trader looks afraid and holds his hands to his mouth among graphics of red arrows pointing down

    A bitcoin trader looks afraid and holds his hands to his mouth among graphics of red arrows pointing down

    After charging 20% higher in March, the Bitcoin (CRYPTO: BTC) price went the opposite direction in April.

    Depending on your time zone, the world’s number 1 token by market cap kicked off the month just past trading for US$45,843. By the late hours of 30 April, the Bitcoin price stood at US$38,063, down 17% for the month.

    In a sign of its continuing volatility, Bitcoin traded for as high as US$47,313 in April while it reached lows of US$37,585, according to data from CoinMarketCap.

    Up 1.6% so far in May, the digital token is down 44% from its 10 November all-time highs.

    Why did the Bitcoin price retrace in April?

    The biggest headwind facing the Bitcoin price last month was the spectre of a series of significant interest rates from the US Federal Reserve, with other major central banks expected to follow.

    Commenting on Bitcoin’s slide earlier in April, eToro’s market analyst and crypto expert Simon Peters said:

    The moves down underpin what has emerged as a significant trend in 2022 – that cryptoassets don’t appear immune to rate hike environments. Moving to a similar beat to traditional stock markets such as the Nasdaq 100, crypto appears to be struggling under an increasing rate environment.

    Indeed, the tech-heavy Nasdaq closed down 14% in April, compared to the 17% fall in the Bitcoin price.

    But it wasn’t all bad news for crypto investors.

    Buy your luxury car with crypto

    During the month gone by, CoinSpot reported that it was partnering with luxury car retailer Dutton Garage to allow its customers to buy vehicles with a range of 30 some cryptos, including Bitcoin.

    Customers can either pay for all or part of their shiny new Porsches or Mercedes with crypto, with any additional payments made with good old Aussie dollars.

    “Increasing crypto’s utility is the key to driving mass adoption of what we believe is the future of finance,” CoinSpot chief product officer Gary Howells said at the time the partnership was announced.

    With the Bitcoin price falling 17% in April, swapping the tokens out for a new vehicle may have been fortuitous timing.

    The post What happened with the Bitcoin price in April? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Bitcoin right now?

    Before you consider Bitcoin, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Bitcoin wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Bitcoin. The Motley Fool Australia has positions in and has recommended Bitcoin. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/os35hlR

  • 3 timeless investing lessons from the 2022 NASDAQ bear market

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    volatile asx share price represented by investors riding a roller coaster

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Meta Platforms (NASDAQ: FB) stock went up more than 17% on Thursday, then Amazon (NASDAQ: AMZN) stock was down over 12% in after-hours trading.

    When such large companies make mega moves to the upside and downside, it can be a sign that the market is volatile. And given the NASDAQ Composite Index (NASDAQ: .IXIC) has plunged into a bear market in a matter of months, it is clear that the 2022 stock market is looking much different than the rip-roaring year we had in 2021. A bear market is defined as a drawdown of at least 20% from an all-time high, while a correction, which the S&P 500 Index (SP: .INX) is currently in, is a drawdown of at least 10% from an all-time high.

    However, bear markets are not inherently bad things. And with the right temperament and patience, they can even lead to life-changing wealth. Here are three timeless investing lessons from the 2022 Nasdaq bear market that you can take with you to become a better investor.

    1. It’s a staircase up and an elevator down

    There’s an old saying that the stock market is a staircase up and an elevator down. We are seeing this pattern play out before our very eyes.

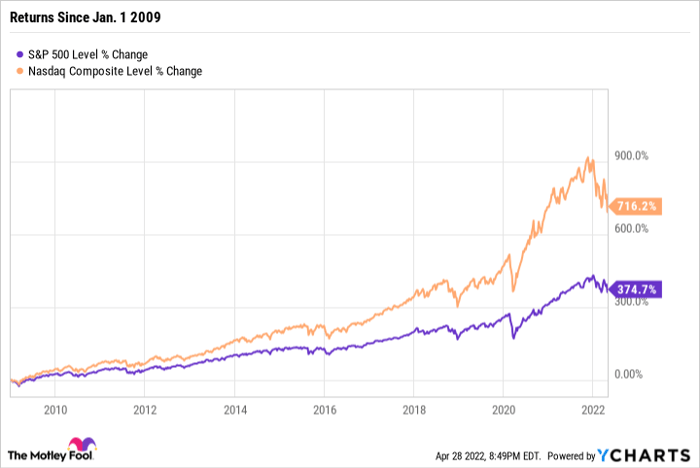
    Bull markets are typically slow and steady and last for multiple years, while bear marks are sharp and swift and tend to last for just one or a few years. At least that’s what history tells us. And that’s certainly what has played out since the financial crisis. There has been a more or less uninterrupted 12-year bull market since the financial crisis. But included in that bull market have been a handful of bear markets — such as the fall 2018 bear market, the spring 2020 bear market, and the bear market we are currently in.

    Yet through it all, the S&P 500 has still produced a 375% return (without factoring in dividends) since 1 January 2009, while the NASDAQ Composite has produced a more than 700% return (without factoring in dividends).

    ^SPX Chart

    ^SPX data by YCharts

    The median annual gain of the S&P 500 between 1950 and 2021 was 12.36%. But the standard deviation for that period was 16.04 percentage points. That means that roughly one out of every three years produces an annual return of worse than -5.91% or greater than 26.17%.

    It’s also worth mentioning that there have been 18 down years and 53 up years since 1950. But the average return during a down year is -11.4%. However, that data is somewhat misleading given the unlikelihood that bear markets correlate with calendar years. For example, in 2018 the S&P 500 was up close to 10% year-to-date (YTD) in early October 2018, fell to -12% YTD by Christmas Eve (a 22-percentage-point swing in less than three months), but then finished the year down just 6%.

    2. Valuations matter

    Probably one of the most contentious debates in investing is on valuation. On one end of the spectrum, you have investors like Warren Buffett, who preach value investing and only pay reasonable amounts for businesses based on their earnings, free cash flow, etc. Then on the other end, you have investors like Cathie Wood, who argue that innovative companies that change the paradigms of their industries have so much upside that valuation should be an afterthought.

    The 2022 bear market has taught us that while companies may have tons of potential, there is a great deal of uncertainty as to whether they can live up to lofty expectations. Uncertainty can come in the form of unreliable management, as we have seen through the spectacular collapse of Teladoc Health stock, which is down over 90% from its all-time high. It can also come in the form of increased competition, which we have seen in the fintech space as legacy financial services companies open their pocketbooks on investments, which has strained the edge that companies like Robinhood, SoFi, and Upstart were thought to have in spades.

    The best approach for most investors is to find a middle ground between value and growth by using as many known variables as possible and avoiding unknown ones. In this vein, that probably means sticking mostly with established companies with positive free cash flow and growth potential. These are the types of companies you’ll want in your corner if the market crashes.

    3. Invest in companies that you understand and that suit your personal risk tolerance

    The biggest mistake an investor can make isn’t selling too soon or buying something too high. It’s investing in companies that you don’t understand and that don’t suit your personal risk tolerance. Because if you do that, then you won’t know why a stock can go up 400% in a year and then fall 90% the next. Or why a stodgy dividend stock can barely move while the market soars and then barely fall when the market tanks.

    Aligning your personal risk preferences with companies you understand and believe in is the best way to avoid the psychological torment that can come when a bear market is straining good and bad companies alike, and you don’t know how to react. By sticking with a process, you stand the best chance to endure market volatility and let the power of compound interest work in your favour over the long term.

    Embrace lifelong learning

    Many investors who are new to the stock market have never endured a multi-year bear market. The bear market of late 2018 only lasted a matter of months. Same with the 2020 bear market. In fact, there has not been a bear market that has lasted for more than a year since 2008. By taking a long-term perspective while also using the bear market as a learning experience, you can use this period of stock market volatility to sharpen your skills and become a better investor. If done correctly, this approach could pay lifelong dividends that far exceed any pain your portfolio is currently suffering.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post 3 timeless investing lessons from the 2022 NASDAQ bear market appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. Randi Zuckerberg, a former director of market development and spokeswoman for Facebook and sister to Meta Platforms CEO Mark Zuckerberg, is a member of The Motley Fool’s board of directors. Daniel Foelber has the following options: long January 2024 $100 calls on Teladoc Health, long January 2024 $150 calls on Teladoc Health, short January 2024 $110 calls on Teladoc Health, short January 2024 $170 calls on Teladoc Health, and short July 2022 $7.50 puts on SoFi Technologies, Inc. The Motley Fool has positions in and recommends Amazon, Meta Platforms, Inc., Teladoc Health, and Upstart Holdings, Inc. The Motley Fool Australia has recommended Amazon and Meta Platforms, Inc. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/pQNhxsS

  • Why Alkane, Chalice Mining, PointsBet, and Qantas shares are rising today

    The S&P/ASX 200 Index (ASX: XJO) is on course to start the week with a sizeable decline. In afternoon trade, the benchmark index is down 1.25% to 7,342.7 points.

    Four ASX shares that have defied the market selloff today are listed below. Here’s why they are rising:

    Alkane Resources Limited (ASX: ALK)

    The Alkane share price is up 4% to $1.06. This follows the release of an update on the gold miner’s Roswell Deposit. According to the release, it has been updated after an additional 7,000 metres of drilling and now stands at approximately 904,000 ounces. This is up 37% from its previous estimate.

    Chalice Mining Ltd (ASX: CHN)

    The Chalice Mining share price is up 2% to $7.09. Investors have been buying this mineral exploration company’s shares following the release of further promising drilling results from the world class Julimar project. Chalice Managing Director and Chief Executive Officer, Alex Dorsch, said: “With each new round of drilling results, the scale, quality and potential upside of this world-class critical minerals system just keeps getting better and better.”

    PointsBet Holdings Ltd (ASX: PBH)

    The PointsBet share price is up 4% to $3.12. This appears to have been driven by a positive response to the sports betting company’s third quarter update from Goldman Sachs. The broker has retained its buy rating with a $5.78 price target. It notes that PointsBet’s revenue was in line whereas its cash burn/marketing was better-than-expected.

    Qantas Airways Ltd (ASX: QAN)

    The Qantas share price is up 2.5% to $5.75. The catalyst for this was the release of a trading update by the airline operator. That update revealed that domestic travel numbers are rebounding faster than expected. This is expected to underpin second half underlying EBITDA of $450 million to $550 million, which will be a big improvement on Qantas’ first half EBITDA loss of $245 million.

    The post Why Alkane, Chalice Mining, PointsBet, and Qantas shares are rising today appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Pointsbet Holdings Ltd. The Motley Fool Australia has recommended Pointsbet Holdings Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/6bIe4ad

  • Here are the 3 most heavily traded ASX 200 shares on Monday

    Boy looks quizzical standing in front of a graph.

    Boy looks quizzical standing in front of a graph.

    The S&P/ASX 200 Index (ASX: XJO) has a serious case of Mondayitis on the first day of the trading week so far. The index clearly fell out of the wrong side of the bed this morning and is down a nasty 1.25% at just under 7,340 points at the time of writing.

    But rather than dwelling on that, let’s delve deeper into the share market today and check out the ASX 200 shares that are currently at the top of the market’s volume charts, according to investing.com.

    The 3 most-traded ASX 200 shares by volume this Monday

    Telstra Corporation Ltd (ASX: TLS)

    Our first ASX 200 share to check out today is blue chip Telstra. This telco has had a notable 11.14 million shares swap hands so far this Monday. There’s been a small announcement out from the company today. Telstra revealed this morning that its new chief financial officer is to be Michael Ackland, who will start in the role on 1 September.

    However, it’s more likely that it is the Telstra share price itself that is responsible for this volume we see. Telstra shares have been whacked today, currently down 1.24% at $3.99 each.

    Qantas Airways Limited (ASX: QAN)

    Another ASX 200 share that used to be a government-owned company is next up today. National air carrier Qantas has seen a hefty 12.6 million of its shares fly to a new home over today’s trading day thus far. In stark contrast to the markets today, Qantas shares have taken off. The company is currently up 2.68% at $5.75 a share.

    This move comes after the company reported some pleasing updates this morning, as well as announcing new long-haul flight paths. It’s this outbreak performance that has probably resulted in Qantas’ appearance on this list today.

    Pilbara Minerals Ltd (ASX: PLS)

    ASX 200 lithium producer Pilbara rounds out our list today, coming in at first place. This Monday has seen a sizeable 15.98 million Pilbara shares bought and sold thus far. Unfortunately for investors, this volume seems to be the direct consequence of a dreadful share price drop. The Pilbara share price is currently down by a nasty 6.14% at $2.675 a share.

    The post Here are the 3 most heavily traded ASX 200 shares on Monday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Qantas right now?

    Before you consider Qantas, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Qantas wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has positions in Telstra Corporation Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has positions in and has recommended Telstra Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    from The Motley Fool Australia https://ift.tt/lTSJexc