Category: Stock Market

  • Top fund manager reveals 2 undervalued ASX shares to buy

    A white and black clock face is shown with three hands saying Time to Buy reflecting Wilson Asset Management's two ASX share picks in its WAM Research portfolioA white and black clock face is shown with three hands saying Time to Buy reflecting Wilson Asset Management's two ASX share picks in its WAM Research portfolio

    Leading fund manager Wilson Asset Management (WAM) has revealed two ASX shares that it rates as buys within its WAM Research Limited (ASX: WAX) portfolio.

    WAM operates a few different listed investment companies (LICs).

    One of the LICs is called WAM Research, which looks at smaller businesses on the ASX.

    WAM describes WAM Research as an LIC that “invests in the most compelling undervalued growth opportunities in the Australian market”.

    The WAM Research portfolio has delivered gross returns (that’s before fees, expenses, and taxes) of 15.3% per annum since the investment strategy changed in July 2010. This has been better than the All Ordinaries Total Accumulation Index (ASX: XAOA) return of 9.6% per annum.

    These are the two undervalued ASX shares that WAM outlined in its most recent monthly update for WAM Research.

    Brickworks Limited (ASX: BKW)

    WAM explained that Brickworks manufactures a diverse range of building products across Australia and North America. It has 2,500 staff around the world.

    The fund manager noted that in March, Brickworks announced a record half-year statutory net profit after tax (NPAT) of $581 million. This represented a 720% increase from the previous corresponding period, which beat market expectations.

    The ASX share’s building material manufacturing division in Australia delivered a significant increase in earnings before interest and tax (EBIT) in the first half of FY22. It rose by 66% to $27 million. WAM said that sales momentum increased after COVID-19 lockdowns.

    Wilson Asset Management believes the joint venture industrial property trust between Brickworks and Goodman Group (ASX: GMG) continues to be undervalued by the market “despite its sustained growth which has been fuelled by the accelerated industry trend towards e-commerce.”

    The fund manager is positive on Brickworks, with expectations that further sales of land into the property trust will lead to a significant uplift in rental income, which “will continue to support double-digit earnings growth in this division”.

    Johns Lyng Group Ltd (ASX: JLG)

    The other ASX share that WAM named was the integrated building services business Johns Lyng, which has operations in Australia and the US. Its main businesses are based on rebuilding and restoring a variety of properties and contents after damage.

    Last month, the business announced that it had been chosen to lead the New South Wales Government’s $142 million recovery response to the February and March flood events across the Eastern seaboard.

    WAM believes this contract win will provide a tailwind of future earnings growth in Australia for the company, which has already been underpinned by a better-than-expected FY22 interim result.

    The fund manager is still positive on Johns Lyng as it continues to grow with acquisitions that add to earnings in both Australia and the US.

    The post Top fund manager reveals 2 undervalued ASX shares to buy appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Brickworks. The Motley Fool Australia owns and has recommended Brickworks. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/4rUhmMj
  • Why this broker tips the Macquarie share price to clip $227 this year

    Two brokers analysing stocks.Two brokers analysing stocks.

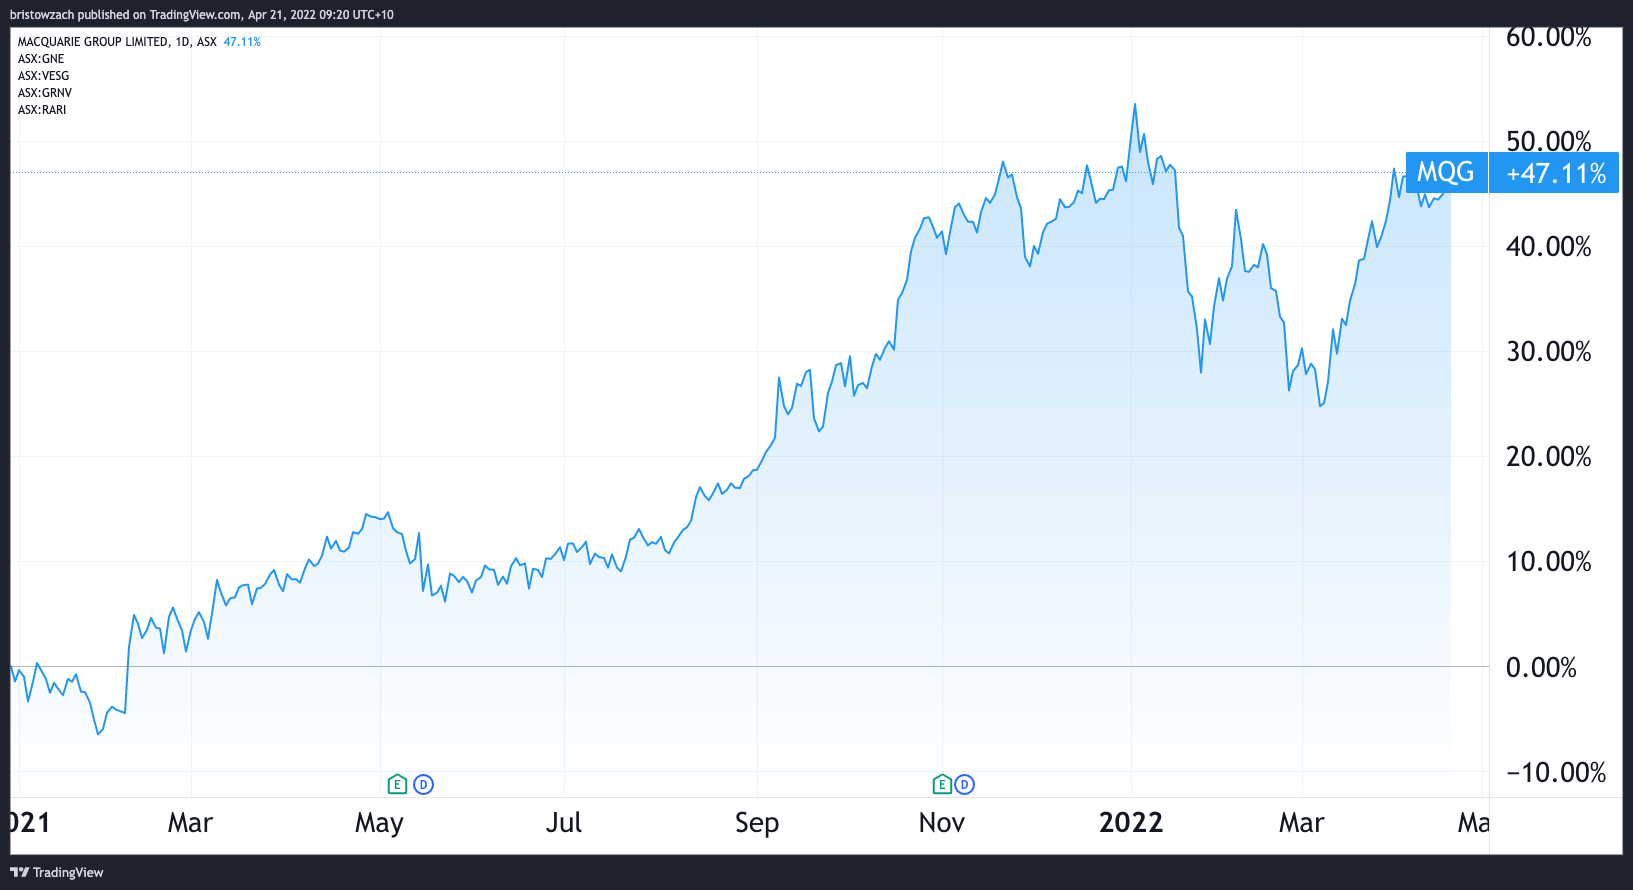
    Shares in Macquarie Group Ltd (ASX: MQG) have leapt higher in recent weeks to trade at $206.67 before the open on Thursday.

    After a rough period of volatility, the investment bank has clawed back gains and is now tracking towards its 52-week high of $215.

    TradingView Chart

    Can Macquarie’s share price run higher?

    One broker has priced in roughly 10% more upside for Macquarie shares this year. JP Morgan values the bank at $227 per share, after revising its price target up from $223/share in a recent note.

    “[Macquarie’s] guidance for commodities income to be “significantly up on FY21” was given prior to the recent spike in energy prices,” the broker shared.

    “Since then, international events have contributed to much higher natural gas price volatility, which should provide strong support to trading income.”

    As such it now projects the bank’s commodities income to spike 27% in FY22 to $3.4 billion, with a slight drop to $2.6 billion the following year.

    All-in-all, the broker tips FY22 to be a bolster year for Macquarie, locking in tidy profits if all goes according to plan.

    Recent acquisitions and structural demand for alternative investments are also catalysts for Macquarie’s various operating segments, it says.

    “Growth should be supported by significant deployment of capital into all operating divisions given a healthy capital surplus,” analysts added.

    “We still see modest upside to our valuation, particularly given our forecast of >15% Return on Equity (ROE) in FY22-24′”.

    At $227 per share JP Morgan’s valuation rests above the consensus price target for Macquarie of $220.54, but Jefferies and Morgan Stanley both value the bank at $245 per share, according to Bloomberg data.

    In the last 12 months the Macquarie share price has climbed 32% and is up 6% this past month.

    The post Why this broker tips the Macquarie share price to clip $227 this year appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Macquarie Group right now?

    Before you consider Macquarie Group, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Macquarie Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3MVuQSX

  • Why are EML shares attracting so much short interest in April?

    A short boy wearing big glasses stands next to a measuring stick with his hand on his head wondering if he'll ever stop being short, similar to the Polynovo share price which is among the most shorted shares on the ASX right nowA short boy wearing big glasses stands next to a measuring stick with his hand on his head wondering if he'll ever stop being short, similar to the Polynovo share price which is among the most shorted shares on the ASX right now

    Shares in EML Payments Ltd (ASX: EML) have levelled off after a short-lived recovery in March. From the beginning of last month, EML shares thrust off a low of $2.20 per share and raced north to touch the ceiling at $3.01 apiece.

    Since, prices have taken a step backward and rest at $2.80 per share before the open of trade on Thursday.

    The shortened week has done nothing to save EML’s stock either, with the share price sliding more than 13% since trading restated in January.

    EML also leads the list of companies with the largest amount of short interest as a percentage of free float, and its been embroiled in a takeover drama with private equity giant Bain Capital.

    Before the open on Thursday, EML has a short interest ratio of 15.2 with more than 34.5 million shares in the hands of short sellers. It hit a high of 33.5 two weeks ago. As such, 9.2% of its shares are under short interest.

    TradingView Chart

    Why are investors bearish on EML?

    Interestingly, bearish wagers on ASX names has increased over the past few weeks, and again week-on-week to Wednesday.

    “Total Australian short interest [was] A$21.5 billion vs. A$21.3 billion last week; [whilst] bearish bets [were] equivalent to approximately 1.08% of equity float,” according to Bloomberg Intelligence, from internal calculations.

    Of the entire market, consumer discretionary and information technology sectors are most shorted, with 2.4% of short interest in each segment, Bloomberg data shows.

    Arguably, both of these industries have spillover into EML, considering its a technology-based payments company that relies on customer transactions to generate operating income.

    In fact a quick check sees that these 3 ‘instruments’, let’s call them, have moved in almost unison since October last year.

    TradingView Chart

    Last week, EML released a statement advising it had been in talks with Bain Capital last year for a purported buyout.

    As TMF reported at the time, Bain walked away “because of the high price tag after looking at the due diligence numbers.”

    “The board of EML said that it would always consider proposals presented to the company and that it’s fully committed to acting in the best interests of shareholders. The goal of EML’s board is to maximise value for shareholders,” it was reported.

    Investors weren’t galvanised by the outcome and refused to allocate more capital to EML shares, meaning the stock remains in the lurch for 2022.

    Ron Shamgar of Tamim Asset Management appeared to see the reasoning behind Bain’s decision, in a post last week.

    “If ASX investors won’t value businesses properly, then others will take them off their hands and reap the rewards over time!” he wrote.

    The EML share price is down more than 49% in the last 12 months despite a 14% surge over the past single month.

    The post Why are EML shares attracting so much short interest in April? appeared first on The Motley Fool Australia.

    These 5 Cheap Shares Could Be Set For Huge Gains (FREE REPORT)

    We hear it over and over from investors, “I wish I had bought Altium or Afterpay when they were first recommended by The Motley Fool. I’d be sitting on a gold mine!” And it’s true.

    And while Altium and Afterpay have had a good run, we think these 5 other stocks are screaming buys. And you can find out the names of these stocks in the FREE stock report.

    *Extreme Opportunities returns as of February 15th 2021

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended EML Payments. The Motley Fool Australia owns and has recommended EML Payments. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/SDk6IO5

  • 2 beaten-up ASX shares with massive upside: experts

    Man drawing an upward line on a bar graph symbolising a rising share price.

    Man drawing an upward line on a bar graph symbolising a rising share price.

    Leading investment experts have identified some ASX shares with lots of growth potential after being heavily sold off.

    It has been a difficult period for businesses that are known for growing at a faster rate.

    There is increased market concern about what the elevated inflation rate will mean for interest rates. The US interest rate is expected to increase significantly in 2022.

    Here are two beaten up ASX shares the experts reckon have big upside potential.

    Hub24 Ltd (ASX: HUB)

    The Hub24 share price has fallen almost 17% this year to date, despite the ongoing growth of the business.

    Hub24 is one of the larger fintechs on the ASX. It operates a few different businesses including the Hub24 platform, the Xplore platform and Class. The ASX share says the Hub24 platform offers advisers and their clients a range of investment options, including managed portfolios and enhanced transaction and reporting functionality.

    The company continues to deliver growth. In its update for the three months to 31 March 2022, its platform net inflows were $2.6 billion, an increase of 36.4%. The financial year-to-date net inflows to 31 March 2022 were $9.3 billion.

    At 31 March 2022, Hub24 had total funds under administration (FUA) of $68.3 million, including $51 billion of platform FUA – that was up 43.3%. The company also said that the Hub24 platform was ranked first for adviser advocacy by Adviser Ratings.

    Broker Credit Suisse currently rates the ASX share a buy. The Hub24 share price target is $36 by the broker. That implies a potential rise of almost 50% over the next year if the broker is right.

    Temple & Webster Group Ltd (ASX: TPW)

    The Temple & Webster share price has dropped around 40% since the beginning of 2022. This business is an online-only retailer of furniture and homewares.

    However, unlike some other ASX online retail shares, the e-commerce ASX share hasn’t reported a sales decline.

    In the first few weeks of the second half of FY22 to 6 February 2022, the ASX share saw revenue grow by another 26%. Growth on growth can lead to much bigger numbers after a few years, thanks to the power of compounding.

    Temple & Webster is investing its revenue into several areas to keep growing. It’s spending on marketing, investing in technology, expanding its private label brand and increasing its operational efficiencies. The company says that increased scale will help with better unit economics.

    One of the company’s selling points for customers is its augmented reality technology, which allows customers to ‘see’ a product in their space.

    The ASX share sees potential for growth in the home improvement segment, selling things like paint supplies, flooring, garden and landscaping, tools and equipment, plumbing fixtures and so on. Temple & Webster says that this is a $16.4 billion market opportunity, with less than 5% of the home improvement sector having gone online.

    It’s currently rated as a buy by Credit Suisse. The Temple & Webster share price target is $13.54. That implies a potential upside of more than 110%. It thinks it can continue to capture a growing market share.

    The post 2 beaten-up ASX shares with massive upside: experts appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Hub24 Ltd and Temple & Webster Group Ltd. The Motley Fool Australia owns and has recommended Hub24 Ltd. The Motley Fool Australia has recommended Temple & Webster Group Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/wFd0kRH

  • Beat inflation with these ASX dividend shares that analysts rate as buys

    While it looks as though interest rates will soon start to rise, it is still likely to be some time until rates return to normal levels.

    So with inflation roaring, dividend shares could remain important for income investors for the foreseeable future.

    But which dividend shares could be top options? Two to consider are listed below. Here’s what you need to know about them:

    Adairs Ltd (ASX: ADH)

    The first ASX dividend share to look at is this furniture and homewares retailer.

    Its shares have fallen hard this year due to a disappointing first half performance. However, it is worth noting that this was driven by COVID lockdowns, which led to Adairs losing almost a third of its trading days during the period.

    One positive is that on a like for like basis (adjusted for closures), its sales were actually up 2.7% year on year. So with COVID lockdowns now a thing of the past, Adairs’ outlook is improving greatly.

    Morgans remains positive on the company and appears to see the sell down of Adairs’ shares as a buying opportunity. It has an add rating and $3.70 price target on its shares.

    As for dividends, the broker is forecasting fully franked dividends of 19 cents per share in FY 2022 and 26 cents per share in FY 2023. Based on the current Adairs share price of $2.94, this will mean yields of 6.4% and 8.8%, respectively.

    HomeCo Daily Needs REIT (ASX: HDN)

    Another ASX dividend share for income investors to look at is the HomeCo Daily Needs REIT. It is a property company investing in neighbourhood retail, large format retail, and health and services.

    Goldman Sachs is a fan of the company. The broker believes it is well positioned to benefit from the shift to omni channel retailing. It also notes that HomeCo Daily Needs REIT has additional external growth opportunities to drive earnings growth over the medium-term.

    The broker currently has a buy rating and $1.70 price target on its shares. As for dividends, Goldman is forecasting dividends per share of 8 cents in FY 2022 and 9 cents in FY 2023. Based on the current HomeCo Daily Needs share price of $1.44, this will mean dividend yields of 5.5% and 6.25%, respectively.

    The post Beat inflation with these ASX dividend shares that analysts rate as buys appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ADAIRS FPO. The Motley Fool Australia owns and has recommended ADAIRS FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/vhygL9E

  • Brokers name 3 exciting small cap ASX shares to buy

    A female stockbroker reviews share price performance in her office with the city shown in the background through her windows

    A female stockbroker reviews share price performance in her office with the city shown in the background through her windows

    Looking for some small cap shares to add to your portfolio? Then have a look at the three listed below.

    Here’s why analysts have named them as buys:

    Airtasker Ltd (ASX: ART)

    The first small cap ASX share to consider is this online marketplace for local services. It has been growing at a rapid rate in recent years and has been tipped to continue this trend in the future by the team at Morgans. This is due to the broker’s belief that the company has a very attractive business model and a significant market opportunity that is in the early stages of ecommerce adoption. Morgans has an add rating and $1.27 price target on the company’s shares.

    MoneyMe Ltd (ASX: MME)

    Another small cap ASX share that is rated as a buy is MoneyMe. It is a financial technology company that leverages artificial intelligence to deliver highly automated credit products and customer experiences. It has also been growing at a solid rate in recent years and appears well-placed for more of the same in the future. Particularly given its recent acquisition of the SocietyOne business for $132 million. Morgans is positive on the company’s future, noting that its diverse product suite now combined with the complementary customer base of SocietyOne has the potential to drive further top line growth. The broker has an add rating and $2.60 price target on its shares.

    PlaySide Studios Limited (ASX: PLY)

    A final small cap ASX share that could be a buy is PlaySide Studios. It is Australia’s largest publicly listed video game developer. The company provides titles in a range of categories, including self-published games based on original intellectual property and games developed in collaboration with studios. The latter includes studios such as Disney, Pixar, Warner Bros, and Nickelodeon. PlaySide has also been dabbling, with big success, with NFTs and announced material work for hire deals with a number of games publishing giants. This went down well with the team at Canaccord Genuity, which has put a buy rating and $1.30 price target on its shares.

    The post Brokers name 3 exciting small cap ASX shares to buy appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended Airtasker Limited. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/0pC1AqG

  • Gambling & explosives: fund reveals 2 ASX shares to buy right now

    A business man in soft-focus holds two fingers in the air in the foreground of the shot as he stands smiling in the background against a clear sky.A business man in soft-focus holds two fingers in the air in the foreground of the shot as he stands smiling in the background against a clear sky.

    With interest rates expected to rise multiple times later this year, high-growth ASX shares for companies that don’t turn a profit are definitely out of favour.

    Current cash flow and earnings have become more important, as investors move away from future to current potential.

    As such, it was interesting to note two stocks that the Investors Mutual Concentrated Australian Share Fund had in focus in its latest memo to clients.

    This ASX share isn’t a gamble, says fund

    Investors Mutual analysts noted that Tabcorp Holdings Limited (ASX: TAH) shares had gained 7.6% during the first quarter.

    But they reckon there are more returns coming.

    “The company delivered a solid result driven by continued positive operating momentum in the core lotteries business.”

    Tabcorp is currently undertaking a separation of its lotteries business.

    “We continue to see long-term value in the lotteries business and believe that post demerger, M&A interest in both the lotteries and wagering businesses could resurface.”

    The share price of Tabcorp is up more than 3% for the year. It has proven resilient against this year’s drop in the general market outside mining and financials.

    The stock closed Wednesday at $5.42.

    The Investors Mutual team isn’t the only one optimistic about the betting company’s fortunes.

    Goldman Sachs Group Inc (NYSE: GS) analysts earlier this month named it as a buy with a price target of $6.20, which is an almost 15% premium to the current level.

    The power of setting your own prices

    The Investors Mutual memo noted that Orica Ltd (ASX: ORI), as “the world’s leading explosives manufacturer”, enjoyed a 16.5% boost in its share price last quarter.

    The team likes the pricing power of Orica during a period of high inflation.

    “Explosive prices have risen for two reasons,” the IM memo read.

    “Firstly, mining volumes have increased due to the higher commodity prices which in turn has led to higher demand for Orica’s explosives. Secondly, supply shortages of explosives have emerged from eastern Europe due to Russia’s invasion of Ukraine.”

    Investors Mutual Concentrated Australian Share Fund remains positive about the company’s future.

    “We continue to hold Orica in the Fund, as the company’s recovery post-COVID is still in its early phases and we remain positive on the company’s capital light growth strategy in the mining software market.”

    The Orica share price finished Wednesday at $16.30.

    Back in February, Investors Mutual director Anton Tagliaferro identified the explosives maker as one of the best examples of current cash flow-positive businesses.

    “As investors begin to appreciate real cash flows generated by companies in the next two to three years, as opposed to hoped-for cash flows in 10 or 20 years’ time.”

    The post Gambling & explosives: fund reveals 2 ASX shares to buy right now appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/gCBbsiw

  • The Cochlear dividend is being paid today. Here’s what you need to know

    a small girl smiles and holds her ears as if listening to a noise in an outdoor setting.a small girl smiles and holds her ears as if listening to a noise in an outdoor setting.

    Cochlear Limited (ASX: COH) shareholders are likely to have something to cheer about today as the company pays out its latest dividend.

    The hearing solutions company is set to reward eligible investors with an unfranked interim dividend of $1.55 per share.

    At Wednesday’s market close, the Cochlear share price finished 1.23% higher at $227.20.

    For context, the S&P/ASX 200 Index (ASX: XJO) also climbed yesterday with a slight gain of 0.05% to 7,569.2 points.

    Let’s look at the details regarding the company’s dividend.

    Cochlear pays interim dividend

    On 22 February, Cochlear reported a robust performance in its half-year results for the 2022 financial year.

    In summary, sales revenue increased 10% to $815 million compared to the prior corresponding period. This was driven by an uneven split between emerging and developed markets.

    On the bottom line, Cochlear recorded a 26% lift in underlying net profit after tax (NPAT) of $158 million. 

    Management noted that the COVID-19 pandemic challenged the results, affecting hospital staffing levels.

    Nonetheless, the board elected to bump up its interim dividend by 35% on the previous year’s first-half distribution of $1.15 per share.

    Based on the current share price, Cochlear is trailing on a forecast dividend yield of 0.62%

    Cochlear share price summary

    Cochlear shares have nudged 5% higher over the last 12 months, buoyed by strong gains after delivering its financial scorecard. The company’s shares are up 4% this year to date.

    The Cochlear share price reached a 52-week low of $178.55 in January but has regained some ground and is now trading around November 2021 levels.

    Cochlear has a price-to-earnings (P/E) ratio of 57.56 and commands a market capitalisation of roughly $14.94 billion.

    The post The Cochlear dividend is being paid today. Here’s what you need to know appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Cochlear right now?

    Before you consider Cochlear, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Cochlear wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Cochlear Ltd. The Motley Fool Australia has recommended Cochlear Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/ZT1fzYx

  • BHP share price on watch following Q3 update

    A Chinese property developer sits in front of his laptop looking pensive and concerned as the Chinese property market wobbles potentially causing problems for ASX 200 mining shares

    A Chinese property developer sits in front of his laptop looking pensive and concerned as the Chinese property market wobbles potentially causing problems for ASX 200 mining shares

    All eyes will be on the BHP Group Ltd (ASX: BHP) share price on Thursday.

    This follows the release of the mining giant’s third quarter update this morning.

    What happened during the quarter?

    For the three months ended 31 March, BHP delivered iron ore production of 59.7Mt. This was flat quarter on quarter and means that year to date production remains down 10%.

    Management notes that this reflects temporary labour constraints due to COVID-19, train driver shortages, and planned maintenance activities at Western Australia Iron Ore (WAIO). This was partially offset by record production from the MAC hub with the continued ramp up of the South Flank.

    BHP’s copper production came in at 369.7kt, which was up 1% quarter on quarter. This was driven by higher volumes at Olympic Dam following the completion of planned smelter maintenance campaign, which was partially offset by lower volumes at Escondida due to COVID-19 workforce impacts and public road blockades following social unrest. Year to date copper production is now down 10%.

    Nickel production was down 13% quarter on quarter to 18.7kt. This means that year to date nickel production is also down 13%. Temporary labour constraints were also to blame.

    BHP’s metallurgical coal production rebounded during the quarter thanks to lower rainfall and a strong operational performance. It rose 20% quarter on quarter to 10.6Mt, which means year to date production is now down only 2%.

    Elsewhere, energy coal production was down 13% to 2.6Mt and petroleum production reduced 6% to 24.1MMboe.

    Management commentary

    BHP’s Chief Executive Officer, Mike Henry, appear pleased with the quarter, all things considered. He said:

    “BHP delivered safe and reliable production in the third quarter. Our WA iron ore business continues to perform strongly as we navigate the state’s first major COVID-19 wave, and we remain on track to achieve full year volume and cost guidance. Amid record high prices, our Queensland metallurgical coal business delivered strong underlying performance and benefited from better weather in the quarter.

    In copper, Spence production is increasing and the Olympic Dam smelter is performing strongly as it returns to full production following planned maintenance. These gains have been more than offset at Escondida by impacts from COVID-19 and public road blockades in Antofagasta, which are reflected in a revision to overall production guidance.”

    Mr Henry also spoke about inflationary pressures that are impacting the sector. He commented:

    “Market volatility and inflationary pressures have increased further as a result of the Russian invasion of Ukraine. We continue our work to mitigate cost pressures through a sharp focus on operational reliability and cost discipline. While we expect conditions to improve during the course of the 2023 calendar year, we anticipate the skills shortages and overall labour market tightness in Australia and Chile to continue in the period ahead.”

    Outlook

    BHP has reaffirmed its FY 2022 production guidance for iron ore, metallurgical coal, and energy coal. However, it has lowered its copper and nickel production guidance.

    It has also reaffirmed its full year unit cost guidance for WAIO, Escondida, and Queensland Coal, but has increased its guidance for New South Wales Energy Coal. The latter reflects a targeted increase in the proportion of higher quality coal to capture more value from the record high prices for higher quality thermal coal.

    The post BHP share price on watch following Q3 update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP right now?

    Before you consider BHP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/7dwgFIt

  • Is the Rio Tinto share price in the buy zone after its quarterly update?

    Female miner smiling while inspecting a mine site with another miner.

    Female miner smiling while inspecting a mine site with another miner.

    The Rio Tinto Limited (ASX: RIO) share price was out of form on Wednesday.

    The mining giant’s shares fell almost 3% to $118.30.

    Why did the Rio Tinto share price tumble?

    Investors were selling down the Rio Tinto share price in response to the release of the mining giant’s first quarter update.

    As you might have guessed from the market’s reaction, that update was softer than analysts were expecting.

    For example, Goldman Sachs commented: “RIO reported a softer 1Q vs. GSe/consensus, with iron ore and copper both down 15%/5% QoQ respectively.”

    This was due to iron ore tie-in and commissioning activities in the Pilbara continuing to be impacted from labour shortages and equipment issues. Copper production was also impacted by lower mill throughput related to labour shortages.

    One positive, though, is that Rio Tinto has reaffirmed its full year production guidance despite its soft start to the financial year.

    Is this a buying opportunity?

    While Rio Tinto’s first quarter update disappointed Goldman Sachs, its analysts remain positive on the company’s outlook.

    So much so, the broker has retained its buy rating, albeit with a slightly trimmed price target of $135.10.

    Based on the current Rio Tinto share price, this implies a potential return of 14% for investors before dividends.

    Goldman said: “Despite ongoing operational issues and concerns over future growth (Pilbara heritage and replacement mines, Simandou, Oyu Tolgoi, Resolution) and uncertainty over decarbonisation capex, we rate RIO a Buy.”

    The broker’s buy rating is based on Rio Tinto’s attractive valuation (~0.9x NAV), strong iron ore outlook, production growth potential, low emission aluminium exposure, and strong free cash flow. Goldman expects the latter to underpin double digit fully franked dividend yields in FY 2022 and FY 2023.

    All in all, this could make Rio Tinto’s shares worth considering if you’re looking for exposure to the resources sector right now.

    The post Is the Rio Tinto share price in the buy zone after its quarterly update? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Rio Tinto right now?

    Before you consider Rio Tinto, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Rio Tinto wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/xi3ezbq