Category: Stock Market

  • 2 ASX dividend shares expected to pay HUGE yields in 2022

    $100 Australian notes on top of each other.

    $100 Australian notes on top of each other.

    Not every business pays a dividend. Not every ASX dividend share has a big yield. But in 2022, the two ASX stocks in this article are expected to pay large dividends.

    However, there is more to consider about a business than just its shareholder payments. Keeping that in mind, here are two ASX dividend shares that are expected to have very large yields this year:

    Dusk Group Ltd (ASX: DSK)

    Dusk describes itself as an Australian specialty retailer of home fragrance products. It has a store network as well as a website.

    Its product range is designed in-house and is exclusive to Dusk. It claims to be Australia’s leading omni-channel specialty retailer focused on home fragrance products. What does it actually sell? It sells items like candles, diffusers, essential oils and fragrance-related homewares.

    According to Commsec, the ASX dividend share is expected to pay a grossed-up dividend yield of 10.25% in FY22 and keep growing that dividend in FY23 and FY24.

    In the first half of FY22, it generated $80 million of sales and $21.3 million of pro forma earnings before interest and tax (EBIT) despite the impact of store closures during the period. But it did manage to increase its pro forma gross profit margin to 68%, up from 67.7%.

    The company continues to grow in other ways. In HY22, its store network had grown to 128 stores, an increase of six new stores. It’s planning to open another four new stores by Mother’s Day. That’s 8th May in 2022. The Dusk rewards active members grew to 718,000.

    Commsec numbers suggest the Dusk share price is valued at less than 10x FY22’s estimated earnings.

    Fortescue Metals Group Limited (ASX: FMG)

    Fortescue is one of Australia’s, and the world’s, biggest iron ore miners.

    When the iron ore price is elevated, Fortescue is able to generate higher profits and pay higher dividends.

    In FY22, Commsec projections indicate that Fortescue is going to pay an annual dividend of $1.85 per share. That translates into a grossed-up dividend yield of 12.2%.

    For the first half of FY22, the ASX dividend share paid an interim dividend of 86 cents per share, representing a 70% payout of first half net profit after tax (NPAT).

    Fortescue is doing a few different things to try to maintain and grow its profit. It’s getting closer to completing its higher-grade Iron Bridge project and it’s pursuing other potential projects including studying the Belinga iron ore project in Gabon, West Africa.

    Another focus for the business is the Fortescue Future Industries (FFI) partnership with E.ON to become Europe’s largest green renewable hydrogen supplier and distributor by 2030. They are partnering to deliver up to five million tonnes per annum of green hydrogen.

    FFI is the division that wants to help the world decarbonise sectors that are hard to decarbonise. It’s investing to create a global portfolio of green energy projects to supply up to 15 million tonnes of renewable green hydrogen by 2030.

    However, the broker Ord Minnett only rates Fortescue as a hold right now. But, it does expect that the FY22 grossed-up dividend yield could be 14% thanks to higher iron ore prices.

    The post 2 ASX dividend shares expected to pay HUGE yields in 2022 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison owns Fortescue Metals Group Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Dusk Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/N3cAJeK
  • Is the ANZ share price too cheap to ignore?

    Cute little child is talking on his smartphone while standing in his business suit near a concrete wall.Cute little child is talking on his smartphone while standing in his business suit near a concrete wall.

    The Australia and New Zealand Banking Group Ltd (ASX: ANZ) share price hasn’t done much in recent months. But some analysts think it could be good value. Are the shares too cheap to ignore?

    It’s one of the biggest banks in Australia along with Westpac Banking Corp (ASX: WBC), National Australia Bank Ltd (ASX: NAB), and Commonwealth Bank of Australia (ASX: CBA).

    On a price-to-earnings (P/E) ratio basis, ANZ shares have recently been the cheapest compared to the other big banks.

    Is the ANZ share price cheap?

    According to Commsec estimates, ANZ shares are valued at 13x FY22’s estimated earnings.

    Projections show profit growth in FY23 and FY24. The ANZ share price is valued at 12x FY23’s estimated earnings and 11x FY24’s estimated earnings, according to Commsec.

    Since the start of 2022, the ANZ share price has dropped by less than 2%. That’s outperformance against plenty of ASX shares that are known for growth. For example, the REA Group Limited (ASX: REA) share price has fallen 25% in 2022 and the Seek Limited (ASX: SEK) share price has fallen by 17%.

    There are plenty of ‘buy’ ratings on the ANZ share price.

    For example, Citi recently called the bank a buy with a price target of $30.75. It thinks the bank will benefit from rising interest rates, which should help with the net interest margin (NIM). There is a possibility that bad debts will increase, but Citi thinks it will be a net benefit for ANZ and the ANZ share price.

    However, Morgan Stanley is less convinced. It is only ‘equal-weight’ on the bank due to concerns regarding a weaker growth outlook and the loss of market share.

    ANZ share price broker valuations

    Citi thinks the big four ASX bank is valued at 13x FY22’s estimated earnings and under 11x FY23’s estimated earnings. The broker likes ANZ because it looks cheap compared to CBA and NAB.

    Morgan Stanley has lower expectations of ANZ profit, putting the ANZ share price at 14x FY22’s estimated earnings and 13x FY23’s estimated earnings.

    Latest profit result

    In FY21, ANZ generated a statutory profit after tax of $6.2 billion, which was an increase of 72% year on year. However, the cash profit from continuing operations, before credit impairment and tax, was $8.4 billion. This was flat compared to the prior year. But this report was released several months ago.

    The latest investors heard from the bank was a market update for the three months to 31 December 2021.

    In that quarter, the group net interest margin was down eight basis points for the quarter, with the continuation of the “structural headwinds” impacting the sector. However, it did say that the impact of rising rates, predominantly in New Zealand, and recent deposit pricing changes were expected to moderate the ongoing headwinds in the second quarter.

    The performance of profitability can affect the ANZ share price.

    It has been working on managing both its attrition and margins. ‘Simple’ home loan application times are now in line with other major lenders. But, the bank continues to work on its complex loan application systems and processes.

    Revenue with ANZ’s ‘markets’ business for the month of October was softer because of trading conditions, which is expected to impact FY22’s first-half performance.

    Costs to run the bank are expected to be broadly flat in the first half. The credit quality environment has remained benign, with a total provision release of $44 million during the quarter.

    The leadership said its capital position continues to provide flexibility to return further surplus capital to shareholders.

    ANZ is due to release its half-year result on 4 May 2022.

    The post Is the ANZ share price too cheap to ignore? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ANZ right now?

    Before you consider ANZ, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ANZ wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended REA Group Limited, SEEK Limited, and Westpac Banking Corporation. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/fC7pl8t

  • Why Tesla stock popped on Monday

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    blue tesla

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    What happened

    Shares of electric cars leader Tesla (NASDAQ: TSLA) stock jumped 2.2% in 11:05 a.m. ET trading Monday, the first day after a long holiday weekend. Most of the Tesla news these past several days has concerned boardroom maneuverings as Elon Musk angles for control over social media company Twitter (NYSE: TWTR).

    But that’s not what’s pushing Tesla stock higher today. 

    So what

    Instead, what’s giving Tesla investors hope today is a story that ran in The Wall Street Journal over the weekend, predicting that Tesla might be able to resume — at least partially — production of cars at its Chinese gigafactory this week.  

    Tesla is expected to begin running one single “shift” per week and then increase that to two shifts by the end of April, reports the paper. Assuming that shifts at the Shanghai plant are run as the company runs them in the U.S. (four shifts per week, 12 hours per shift, operating three days on, three days off), that should bring Tesla back to 50% capacity in China by the end of this month.  

    Now what

    There’s been no confirmation yet that Tesla has actually succeeded in getting its factory restarted in Shanghai as of this writing. Reuters confirmed that the company is “preparing” to reopen, noting also that Tesla’s workers will need to live on site at the factory in order to work there while the city remains under lockdown. And Beijing is said to have approved Tesla for “priority” in reopening — but that falls short of an official confirmation that reopening has happened.  

    Tesla is relying on Shanghai to do much of the heavy lifting toward its goal of producing more than 1 million cars annually worldwide this year, and the longer the Shanghai factory remains shuttered, the harder it will be for Tesla to hit that goal. Eventually, however, Tesla aims to expand Giga-Shanghai to the point where this single factory is able to produce 1 million cars annually on its own.  

    So long as you agree that the Shanghai gigafactory will reopen eventually, it’s probably best to think of this current delay in reopening as just one more bump in the road in a years-long growth story for Tesla. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Why Tesla stock popped on Monday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Tesla right now?

    Before you consider Tesla , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Tesla wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Rich Smith has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Tesla and Twitter. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/guUBM28

  • Syrah Resources share price booms 19% amid show of US support

    Man with rocket wings which have flames coming out of them.Man with rocket wings which have flames coming out of them.

    The Syrah Resources Ltd (ASX: SYR) share price is surging this morning and is now up 18.95% at $1.868 apiece.

    Investors are reacting to a company announcement from Syrah today advising the market it has been offered a conditional loan from the US Department of Energy (DOE).

    TradingView Chart

    What did Syrah announce today?

    The Syrah Resources share price is skyrocketing after the company said it has finalised a non-binding term sheet for a conditional US$107 million loan from the DOE.

    Syrah notes the loan will be used “to fund the initial expansion of its Vidalia active anode material facility in Louisiana to 11.25ktpa AAM production capacity”.

    The facility will be open to the group’s subsidiary, Syrah Technologies. The proposed loan is to be made under DOE’s Advanced Technology Vehicles Manufacturing (ATVM) loan program in support of US President Joe Biden’s critical minerals strategy.

    The loan’s term sheet states it is for a maximum of US$107 million with “a term of up to approximately 10 years from financial close”.

    “[The] DOE has US$17.7 billion in uncommitted loan authority under the ATVM program to support the manufacture of eligible advanced technology vehicles including electric vehicles (EVs), and qualifying components and materials, in the USA,” it said.

    “If finalised, the loan to Syrah Technologies would be the first from the ATVM loan program since 2011 and the first ever from the ATVM loan program to a materials processing facility,” it added.

    “Other recipients of funding from the ATVM loan program include Ford, Nissan, and Tesla.”

    To fund the remaining $165 million of the Vidalia project, Syrah says it will use proceeds obtained from the equity raising completed earlier this year.

    Speaking on the announcement fuelling the Syrah Resources share price, managing director and CEO Shaun Verner said:

    The finalisation of a term sheet and offer of a Conditional Commitment from DOE for a loan under the ATVM program highlights Vidalia’s strategic position in the USA and provides strong validation of Syrah, Vidalia and the Vidalia Initial Expansion. Importantly, the loan will allow Syrah to accelerate its growth strategy in its downstream business and support the rapidly growing EV and battery supply chain in the USA.

    In the last 12 months, the Syrah Resources share price has spiked 78% after some wide-reaching volatility. This year to date, however, it has slipped 3%.

    The post Syrah Resources share price booms 19% amid show of US support appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Syrah Resources right now?

    Before you consider Syrah Resources, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Syrah Resources wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/nHTqgl1

  • Here are the 5 best performing ASX travel shares of 2022 so far

    A group of travellers run excitedly to the airport gate.A group of travellers run excitedly to the airport gate.

    Many Australians have finally retaken to the skies in 2022 — and these ASX travel shares are lapping up the nation’s enthusiasm.

    Australia’s international borders fully reopened in February, with the country welcoming back international tourists for the first time since March 2020.

    And, during the Easter break, airports Australia-wide reportedly saw their highest levels of demand from holidaymakers in two years.

    So, which ASX travel shares are taking advantage of 2022’s positive momentum? Let’s take a look.

    This year’s top-performing ASX travel shares

    A quick note: This list only considers ASX travel stocks with market capitalisations of more than $50 million.

    Flight Centre Travel Group Ltd (ASX: FLT)

    The Flight Centre share price has bested its ASX travel peers over 2022 so far, gaining 21% year to date.

    That’s despite the only news from the company in that time – its half-year earnings – sending its share price 10% lower.

    Additionally, short-sellers are likely irritated by recent gains in Flight Centre’s stock.

    The company remains one of the ASX’s most shorted shares, with an 18.01% short interest as of The Motley Fool Australia’s latest short-selling update.

    At the time of writing, the Flight Centre share price is $21.39, 0.99% higher than its previous close.

    Webjet Limited (ASX: WEB)

    Again, much to the disappointment of short-sellers, another of the ASX’s most shorted shares has come in as one of the top-performing travel stocks of 2022 so far.

    The Webjet share price has gained around 13.93% this year, despite having a short interest of 8.8% at last count.

    It’s currently trading at $5.87, 0.34% higher than its previous close.

    Corporate Travel Management Ltd (ASX: CTD)

    The Corporate Travel Management share price is also performing well in 2022. It’s come in as the third-best ASX travel stock of this year so far.

    The company’s stock has gained 13.73% year to date, having been boosted 7.5% higher on its half-year results.

    Additionally, the company completed a major acquisition earlier this month.

    It’s now home to what was previously Helloworld Travel Ltd (ASX: HLO)’s corporate and entertainment travel businesses.

    Right now, Corporate Travel Management’s stock is trading at $24.89, 0.12% higher than it was at the end of Thursday’s session.

    Helloworld Travel (ASX: HLO)

    The Helloworld Travel share price has lifted 7.97% since the start of 2022.

    In that time, the company has released its half-year results, handed over its corporate and entertainment travel legs, and welcomed the planned return of international cruising.

    In a recent presentation, the company noted it expects the reintroduction of international cruising, which made up more than a third of its pre-pandemic business, and the return to more normal travel patterns will help boost its bottom line.

    The Helloworld share price is currently trading 1.11% higher at $2.73.

    Qantas Airways Limited (ASX: QAN)

    Finally, the iconic kangaroo has come in as the fifth best performing ASX travel share of 2022 so far.

    The Qantas share price has gained 7.78% this year despite plenty of hiccups.

    The airline pushed through COVID-19 outbreaks that saw it cut capacity in January, before its stock nose-dived 5% on its half-year earnings.

    Right now, Qantas’ shares are trading for $5.41 apiece, 0.73% lower than its previous close.

    The post Here are the 5 best performing ASX travel shares of 2022 so far appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Flight Centre right now?

    Before you consider Flight Centre, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Flight Centre wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Helloworld Limited. The Motley Fool Australia owns and has recommended Helloworld Limited. The Motley Fool Australia has recommended Corporate Travel Management Limited, Flight Centre Travel Group Limited, and Webjet Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/gX7ez8V

  • Here’s why the DGL share price is soaring 9% on Tuesday

    A graphic showing a businessman running up a white upwards rising arrow symbolising the soaring Magellan share price todayA graphic showing a businessman running up a white upwards rising arrow symbolising the soaring Magellan share price today

    The DGL Group Ltd (ASX: DGL) share price is racing higher on Monday morning. This comes after the company announced an update on its full year earnings guidance for FY22.

    During early morning trade, the chemical company’s shares are swapping hands at $3.82, up 9.14%.

    DGL eyes strong growth for FY22

    Investors are driving up DGL shares following the release of an upgraded earnings guidance by the company.

    In its statement, DGL advised that favourable trading conditions have continued to run into the new financial year.

    As a result, the company upgraded its earnings guidance for the period ending 30 June 2022. It expects its full year EBITDA (before deducting acquisition costs) of roughly $65 million on sales revenue of $354 million.

    Previously, DGL had forecasted FY22 EBITDA to be around $54 million (before acquisition costs) on revenue of $343 million.

    Management stated that revenue growth and margin expansion have been recorded for the current financial year. This is expected to continue throughout FY22 with results exceeding expectations across the group.

    Whilst all three operating segments are performing well, the company’s manufacturing business has been the star performer. DGL noted that demand for products and services remains high and assets are well utilised.

    DGL CEO, Simon Henry touched on the company’s improved earnings guidance, saying:

    DGL’s performance so far in the financial year 2022 continues to exceed expectations. All three operating segments are performing strongly with increased activity due to market and seasonal factors.

    DGL continues to successfully execute our strategy to sustainably grow through organic growth and acquiring strategically positioned businesses.

    DGL share price summary

    Over the past 12 months, the DGL share price has soared, representing a 279% gain for shareholders.

    Throughout the year, the company’s shares have continued on an upwards trajectory, up 20%.

    It’s worth noting that the DGL share price touched a record high of $3.99 today before slightly retracing.

    Based on today’s price, DGL commands a market capitalisation of roughly $1.06 billion, with approximately 279.12 million shares outstanding.

    The post Here’s why the DGL share price is soaring 9% on Tuesday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in DGL right now?

    Before you consider DGL, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and DGL wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended DGL Group Limited. The Motley Fool Australia has recommended DGL Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/kq6Pxn0

  • What’s happening to the Boral share price today?

    Man in business suit carries box of personal effectsMan in business suit carries box of personal effects

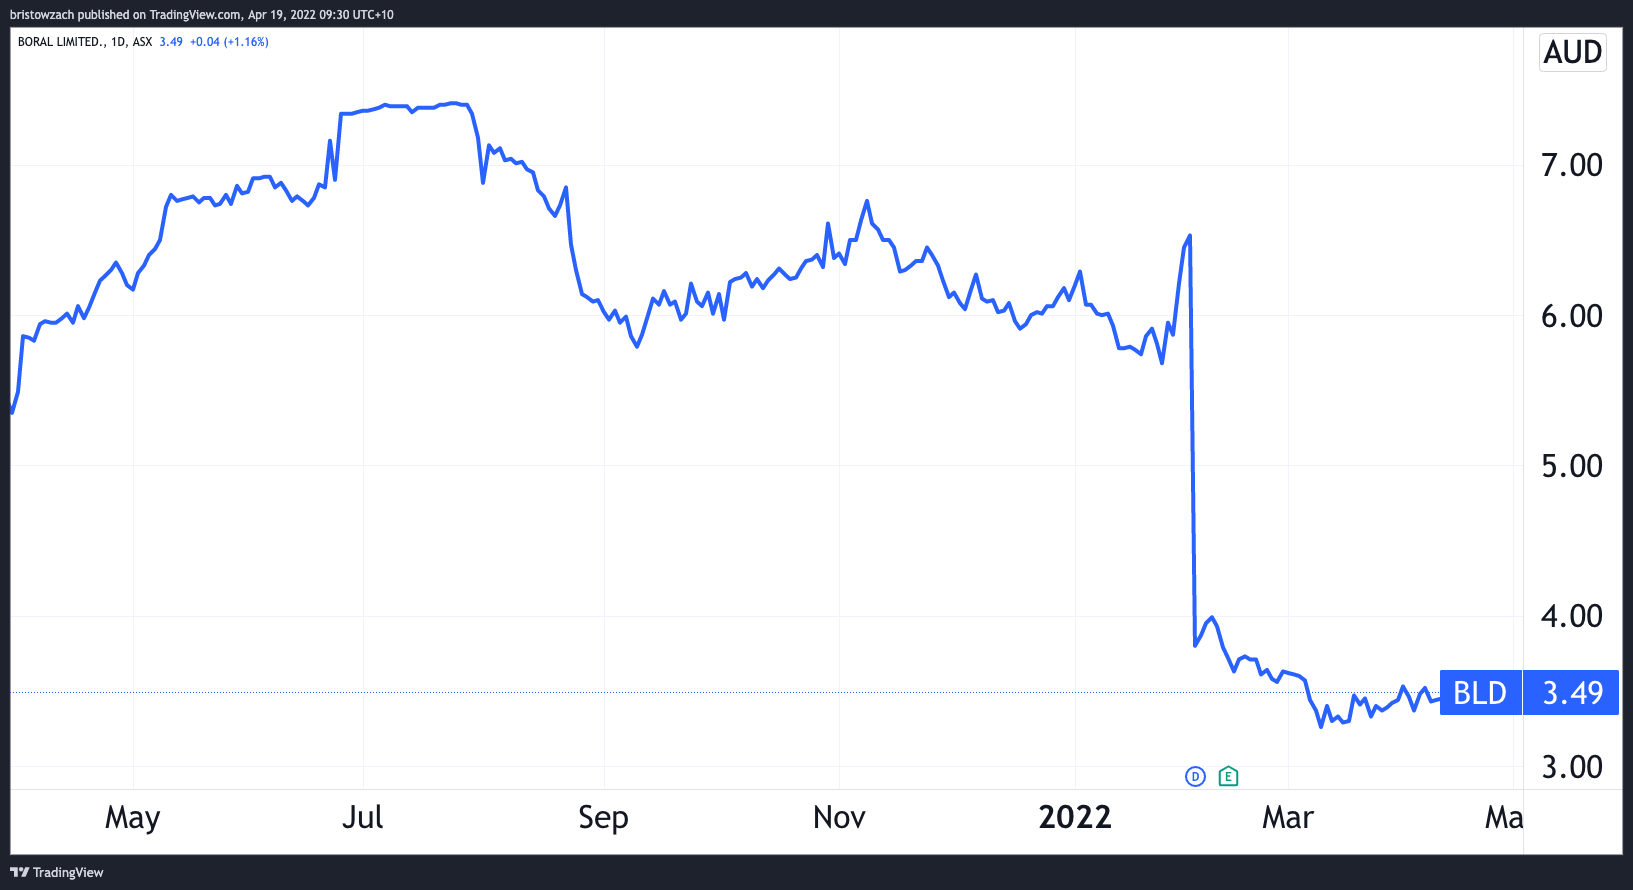
    The Boral Limited (ASX: BLD) share price has slipped into the red today amid reports the company’s CFO and chief strategy officer will leave his position in 2022. The departure adds to a list of executive changes at the company since it was acquired by Seven Group Holdings Ltd (ASX: SVW) last year.

    Boral confirmed the departure in an update provided earlier this morning.

    While the announcement isn’t price sensitive in any way, it is another notch in the growth narrative of the Boral share price.

    Shares in the international building and construction materials group have slipped 0.57% from the open today to currently trade at $3.47 apiece.

    TradingView Chart

    What did Boral announce today?

    The company advised that its chief finance and strategy officer, Tino La Spina, has “ceased” in his role, with the board intending to provide notice of termination on 1 July 2022.

    Boral says its current executive general manager, group finance and property, Jared Gashel, will slide in as acting CFO until new appointments are made.

    Newly appointed chairman, Ryan Stokes, said Boral had been taking a long hard look at what its business “should look like” after the takeover.

    Stokes commented:

    We are committed to the ongoing transformation and operational improvement of Boral. With its focus now in Australia, the Board has been working with management on what the business should look like, given its reduced operational footprint and size.

    In a tough external operating environment, we have decided to accelerate transformational change.

    After the company released an enormous dividend earlier this year, the Boral share price has been trading sideways and is down 43% this year to date. However, it is up almost 2% over the past month.

    It’s rated as a buy from analysts at Macquarie and Barrenjoey, while the consensus price target is $3.69 per share, according to Bloomberg data.

    Meanwhile, analysts at Credit Suisse, Morgan Stanley, Jefferies, and JP Morgan rate it as a hold right now. Only one firm, Barclay Pearce, urges its clients to sell off Boral shares.

    The post What’s happening to the Boral share price today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Boral right now?

    Before you consider Boral, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Boral wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/624eXx5

  • Down 20% in 2022, is the Wesfarmers share price a clear opportunity?

    half a man's face from the nose up peers over a table with a wide eyed, raised eyebrows curious expression while his hands grip either side of the table.

    half a man's face from the nose up peers over a table with a wide eyed, raised eyebrows curious expression while his hands grip either side of the table.

    The Wesfarmers Ltd (ASX: WES) share price has dropped by almost 20% since the start of the year. It begs the question: could the ASX blue chip share now be a buying opportunity?

    A business isn’t necessarily a buy just because it drops in value, but it can help improve the margin of safety. In the investment world, that’s the concept of how much cheaper an investment is compared to what an investor believes the intrinsic/underlying value is. The idea is that a larger margin of safety can reduce the likelihood of a loss with the investment.

    Analysts weren’t exactly excited by the company’s FY22 half-year result, which wasn’t as pleasing as expected.

    For example, UBS noted that COVID-19 hurt the company with elevated costs and multiple store closures. The supply chain was also severely disrupted and this continues.

    What did it report in February?

    Excluding “significant items”, Wesfarmers reported that revenue fell 0.1% to $17.76 billion, earnings before interest and tax (EBIT) dropped 12.3% to $1.9 billion, and the net profit after tax (NPAT) declined 14.2% to $1.2 billion. Some investors use profit as the metric to value the Wesfarmers share price.

    The first half was “the most disrupted period” of COVID-19 for Wesfarmers.

    The company continued to provide paid pandemic leave to team members, including all permanent and many casual employee through periods of prolonged lockdown. This was even when there was no meaningful work for them and when they were required to isolate. This totalled $37 million in the half.

    The company said that sales momentum improved as lockdowns and other restrictions were eased, though the Omicron COVID-19 variant then had a negative impact on foot traffic.

    Wesfarmers also pointed out that ongoing constraints in global supply chains led to delays and additional costs, including higher container shipping expenses during the half. Domestic supply chains were also impacted.

    There was a mixed performance in terms of the underlying earnings before tax (EBT) within different divisions. Bunnings EBT was almost flat, down 1.2% to $1.26 billion. Kmart Group (which includes Kmart, Target and Catch) saw EBT sink 63.4% to $178 million, Officeworks EBT fell 18% to $82 million, Wesfarmers chemicals, energy and fertilisers (WesCEF) EBT jumped 36.3% to $218 million, and the industrial and safety EBT rose 10.8% to $41 million.

    Is the Wesfarmers share price an opportunity?

    Wesfarmers thinks the overall economic conditions in Australia remain favourable, supported by “strong” employment and high levels of accumulated household savings. It’s actively managing increasing inflation pressures and says it will “leverage its scale to mitigate the impact of rising costs”. It’s also going to focus on price leadership for customers.

    The company said that retail trading conditions were subdued in January but trading momentum improved in February.

    Wesfarmers recently completed the acquisition of Australian Pharmaceutical Industries. This will be the foundation of a new health division, which will also look at the wellbeing and beauty sectors.

    The broker Morgans thinks that the Wesfarmers share price is an opportunity, rating it as a buy with a price target of $58.50. Both the broker and management think the company will do well once COVID-19 impacts subside.

    On Morgans’ numbers, Wesfarmers shares are valued at 22x FY23’s estimated earnings with a projected FY23 grossed-up dividend yield of 5.3%.

    The post Down 20% in 2022, is the Wesfarmers share price a clear opportunity? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Wesfarmers right now?

    Before you consider Wesfarmers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Wesfarmers wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Wesfarmers Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/gSvJKn3

  • Why Bitcoin, Ethereum, Dogecoin, and Shiba Inu dropped today

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    bitcoin represented by gold coin with letter b sitting atop circuit board

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    What happened 

    Cryptocurrency investors woke up to a down market on Monday, which just happens to also be tax day in the U.S. In a volatile market like crypto, it seems like every day is either up or down big and today the sellers are winning. 

    Bitcoin (CRYPTO: BTC) had fallen as much as 4.1% as of noon ET, while Ethereum (CRYPTO: ETH) dropped up to 5.8%, Dogecoin (CRYPTO: DOGE) fell 6.9%, and Shiba Inu (CRYPTO: SHIB) fell up to 8%. The selling was widespread so there’s no reason to be especially worried about any particular cryptocurrency. 

    So what 

    It’s hard to ignore that today is tax day in the U.S. Crypto traders may be selling in order to pay taxes due, which can be surprising if this is your first time paying taxes on large trading gains. 

    Over the weekend there was also news of a $182 million hack of the Beanstalk protocol, a stablecoin credit protocol built on Ethereum. This continues a series of hacks of cryptocurrencies across the industry, which undermines investor confidence in the ecosystem. This is an industry wide problem and it doesn’t seem that there’s a great solution right now.

    The stock market overall is down today as well and that has generally meant that more volatile cryptocurrencies will magnify those losses. 

    Now what 

    Volatility is the name of the game in cryptocurrency and that doesn’t seem to be changing anytime soon. Search the internet and you can find analysts and investors who are afraid of inflation, or regulation, or hacking, while others are bullish for reasons that range from innovation to crypto being an inflation hedge. 

    For today, I don’t see anything to be worried about in any of these cryptocurrencies. Given the trends of the industry, I think Ethereum is the best bet given the real utility that can be built in the ecosystem and the projects being built there already. Bitcoin, Dogecoin, and Shiba Inu simply can’t claim the same kind of digital ecosystem. 

    If today’s selling is indeed due to tax season or the down stock market this could be a good buying opportunity for investors. Nothing has fundamentally changed about crypto today and we’re seeing the industry build more and more applications every day. We are also likely to get some regulatory updates in the U.S. and Europe this year, which could be a boost to the industry’s development long-term. 

    When I see moves like this today I tend to brush them off because nothing about cryptocurrencies is fundamentally different than a day ago. It’s just that current portfolios are a little lower for the time being. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Why Bitcoin, Ethereum, Dogecoin, and Shiba Inu dropped today appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Travis Hoium owns Ethereum. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Bitcoin and Ethereum. The Motley Fool Australia owns and has recommended Bitcoin and Ethereum. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/dDIWk32

  • Are these 2 compelling ASX growth shares buys?

    Young boy wearing suit and glasses adds up on calculator with coins on tableYoung boy wearing suit and glasses adds up on calculator with coins on table

    ASX growth shares could be interesting opportunities after such heavy declines in the ASX share market.

    Businesses that are now much cheaper but growing strongly could still be worth looking at.

    While revenue growth isn’t the only important thing, it can help with aspects such as operating leverage and re-investment for more growth.

    Netwealth Group Ltd (ASX: NWL)

    The Netwealth share price has fallen by 27% since the start of 2022.

    This ASX growth share describes itself as a financial technology services company. It’s a superannuation fund trustee and an administration business. It provides superannuation products, investor-directed portfolio services, managed accounts, and managed funds.

    Despite all of the market volatility and disruption, the company continues to experience growth.

    In the quarter for the three months to 31 March 2022, its funds under administration (FUA) reached $57.6 billion, a 37.6% increase year on year. During the quarter, it experienced net inflows of $2.6 billion, an increase of 16%.

    It also had $13.8 billion of funds under management (FUM) at 31 March 2022. The last quarter saw FUM net inflows of $0.5 billion.

    The company boasts of leading the industry for FUA net inflows. It saw the largest FUA net inflows of $13 billion for the 12-month rolling period to 31 December 2021.

    Netwealth said its market share increased to 5.5% at 31 December 2021, “up 1.1%” over the 12 months.

    In terms of the outlook, the company says its pipeline and win rate for new business remains “very strong” across all market segments. In the fourth quarter, which is between April to June, it said it would launch its new non-custodial administration service, further enhancing its capabilities.

    Netwealth still believes its FUA net inflows for FY22 will be more than $13.5 billion.

    The ASX growth share says it’s highly profitable, generates “exceptional” cash flow, has very high levels of recurring revenue, very low capital expenditure, is debt-free, and has “significant” cash reserves.

    Cettire Ltd (ASX: CTT)

    Cettire describes itself as a global online retailer, which sells a large selection of personal luxury goods. It has a catalogue of more than 1,700 luxury brands with more than 200,000 products of clothing, shoes, bags, and accessories.

    The Cettire share price has fallen by 74% since the start of the calendar year.

    In the first half of FY22, the company grew sales revenue by 181% to $113.7 million and the ‘delivered margin’ increased by 118% to $24.7 million. Operating cash flow rose 43% to $12.3 million.

    Its growth continued into the second half of the year, with January 2022 gross revenue growing by 242%.

    The company points to several areas of further growth potential. Its mobile apps “provide scope to improve and optimise the transaction flow and support improved conversion rates over time”.

    It’s expanding into the beauty and children product categories. The ASX growth share is entering the mainland Chinese market and has gone into a partnership with the huge online retailer JD.com.

    The post Are these 2 compelling ASX growth shares buys? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Cettire Limited and Netwealth. The Motley Fool Australia owns and has recommended Netwealth. The Motley Fool Australia has recommended Cettire Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/PFshk1w