Category: Stock Market

  • Why is the Flight Centre share price still the most shorted on the ASX?

    A kid wearing a pilot helmet holds a paper plane up to the sky.A kid wearing a pilot helmet holds a paper plane up to the sky.

    The Flight Centre Travel Group Ltd (ASX: FLT) share price has continued to move in circles since the start of 2022. This is despite the company reporting relatively positive numbers in its FY22 half year results on 24 February.

    While the travel agent’s company’s shares have risen 3% in the last month, it hasn’t been so great of late.

    In fact, Flight Centre shares have now recorded three consecutive trading days of losses, tumbling by almost 5%.

    At the time of writing, its share price is down 0.41% to $19.47 apiece.

    Flight Centre shares take top spot in open ASX short positions

    The negative investor sentiment on the Flight Centre share price can be attributed to the slow recovery of the travel market. This has ultimately attracted a large number of short sellers to the company’s registry.

    Short-selling is a common trading strategy that aims to profit from the fall in the price of a security. The goal is for an investor to borrow and sell the shares, and then buy them back at a lower price for a profit.

    Last week, the Australian Securities & Investments Commission (ASIC) released its short position report revealing the level of short interest within companies.

    As such, Flight Centre remained in the top spot with 17.89% of its shares being heavily shorted by investors.

    In comparison, the government body recorded a short interest of 8.84% in Flight Centre shares last year on 6 April.

    Given the large increase in short positions being taken up, it appears investors believe the company’s performance could be underwhelming. This is due to the COVID-19 pandemic’s ongoing impact on the Flight Centre business.

    What do the brokers think?

    A couple of brokers have rated the company’s share price with varying price points over the last couple of months.

    The team at Bell Potter raised its 12-month price target for Flight Centre shares by 2.5% to $20.50 in March.

    The broker retained its positive view of the company’s outlook and competitive position as global travel begins to improve.

    In addition, Bell Potter highlighted Flight Centre’s growing corporate business and the restructuring of its leisure operations. It believes that the market is underestimating the strength of its corporate business.

    On the other hand, analysts at Citi put out a more bearish tone, slashing its rating by 1.4% to $15.77. It seems that Citi considers that the travel agent’s shares are overvalued for the time being. Based on the current Flight Centre share price, this implies a downside of around 19%.

    Flight Centre share price snapshot

    Over the past 12 months, the Flight Centre share price has risen by about 5%.

    In comparison, the Webjet Limited (ASX: WEB) share price has lost around 2% across the same time frame.

    It’s worth noting that Flight Centre shares hit a multi-year high of $25.28 in October 2021, before treading lower. This is a huge difference from when its shares were trading at the $13 mark in August 2021.

    Flight Centre presides a market capitalisation of about $3.89 billion and has approximately 199.75 million shares outstanding.

    The post Why is the Flight Centre share price still the most shorted on the ASX? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Flight Centre right now?

    Before you consider Flight Centre, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Flight Centre wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Flight Centre Travel Group Limited and Webjet Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/bnVFr2G
  • With oil prices surging in 2022, are Santos shares now ‘significantly undervalued’?

    a man stands in overalls and a hardhat with a clipboard in front of stacked black oil drums at an oil industry site.a man stands in overalls and a hardhat with a clipboard in front of stacked black oil drums at an oil industry site.

    The Santos Ltd (ASX: STO) share price has surged 28% year to date, but could it climb higher?

    Santos shares are currently trading at $8.10, a 1.12% gain. In comparison, the S&P/ASX 200 Index (ASX: XJO) is up 0.07% at the time of writing.

    Let’s take a look at the outlook for Santos.

    Could the Santos share price go higher?

    The Santos share price is climbing today despite sliding oil prices. At the time of writing, the Brent crude oil price has slipped 2.22% to US$100.50 a barrel, according to Bloomberg. Meanwhile, the WTI crude oil price has dropped 2.37% to US$95.93 a barrel.

    Woodside Petroleum Limited (ASX: WPL) shares are also 1.23% in the red at the time of writing.

    However, according to Tribeca Investment Partners, Santos is “undervalued”.

    In fact, Tribeca sees the company as the number one oil company on the ASX. In an interview with Livewire, Tribeca’s lead portfolio manager Jun Bei Liu said Santos is a company that is very attractive in the energy sector:

    We think the business has been significantly undervalued given how much the oil price has gone up.

    And also because of what it’s doing in that whole decarbonization space, that is incredibly valuable. So that’s our number one pick for the oil space. 

    Morgans recently named Santos as a share to add with a $9 price target. The broker expressed positivity on the company’s diversified earnings base and the resilience of the company’s growth profile.

    Share price snapshot

    Santos shares have gained 14% in the past 12 months, while they have climbed almost 6.5% in the past month.

    In contrast, S&P/ASX 200 Index (ASX: XJO) has returned around 7% in the past 52 weeks.

    In the last week, Santos shares are 2.3% higher.

    Santos has a market capitalisation of about $27.3 billion based on the current share price.

    The post With oil prices surging in 2022, are Santos shares now ‘significantly undervalued’? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Santos right now?

    Before you consider Santos , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Santos wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3dO6A5Z

  • Leading brokers name 3 ASX shares to buy today

    ASX shares Business man marking buy on board and underlining it

    ASX shares Business man marking buy on board and underlining it

    With so many shares to choose from on the ASX, it can be hard to decide which ones to buy. The good news is that brokers across the country are doing a lot of the hard work for you.

    Three top ASX shares leading brokers have named as buys this week are listed below. Here’s why they are bullish on them:

    Australia and New Zealand Banking Group Ltd (ASX: ANZ)

    According to a note out of Citi, its analysts have upgraded this banking giant’s shares to a buy rating with an improved price target of $30.75. Citi believes the Reserve Bank’s rate hikes will reshape the banking sector’s earnings profile over the next few years and take net interest margins to levels that are materially higher than consensus estimates. Particularly given its belief that the impact on asset quality won’t be as great as some fear. The ANZ share price is trading at $27.68 on Monday.

    Treasury Wine Estates Ltd (ASX: TWE)

    Another note out of Citi reveals that its analysts have retained their buy rating and $13.78 price target on this wine company’s shares. Citi notes that rival Constellation Brands’ fourth quarter result revealed inflationary pressures adversely impacting earnings, with cost headwinds likely to continue in FY 2023. While the broker expects Treasury Wine to be similarly impacted, it expects price rises, premiumisation, and the re-opening of higher margin on premise channels to offset some of this. The Treasury Wine share price is fetching $11.27 today.

    Whitehaven Coal Ltd (ASX: WHC)

    Analysts at Morgans have retained their add rating and lifted their price target on this coal miner’s shares to $5.20. According to the note, the broker has increased its earnings estimates to reflect higher thermal coal price forecasts. This is expected to underpin big dividends in the near term. In addition, Morgans sees scope for Whitehaven Coal’s shares to rise even further than its price target if coal prices remain stronger for longer. The Whitehaven Coal share price is trading at $4.51 today.

    The post Leading brokers name 3 ASX shares to buy today appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Treasury Wine Estates Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/UzXZj2d

  • The best ASX All Ordinaries shares of the March quarter unmasked

    Three coal miners smiling while underground

    Three coal miners smiling while underground

    After a strong run in 2021, which saw the All Ordinaries Index (ASX: XAO) gain 14%, ASX All Ordinaries shares have had a more difficult time in 2022.

    From the closing bell on 31 December through to the closing bell on 31 March, the All Ords was essentially flat, up a slender 0.1%.

    But not all ASX All Ordinaries shares struggled.

    With rocketing energy prices, you’ll find ASX energy shares dominating the top returns this year. And with coal – yes, the ‘stranded asset’ – hitting all time highs, ASX All Ordinaries shares in the coal sector edged out their rivals in oil and gas to take the lead.

    Below we look at the top three performers over the March quarter.

    The third best ASX All Ordinaries performer of the quarter

    Coming in at number three is Coronado Global Resources Inc (ASX: CRN).

    The ASX All Ordinaries share gained 61% during the quarter.

    Coronado produces high-quality metallurgical coal, which is used in the production of steel.

    And investors rewarded the company for some very strong half year performance figures.

    Highlights include a 47% year-on-year increase in revenue, which hit US$2.15 billion. Net income was also way up, increasing 184% over the prior corresponding half year to $189.4 million. And adjusted earnings before income, taxes, depreciation and amortisation (EBITDA) leapt 804% to $486 million.

    In the early weeks of March, Goldman Sachs lifted its price target on Coronado shares by 33% to $2.80. The ASX All Ordinaries share finished March at $2 per share and is currently trading for $2.14.

    Coming in at number two…

    The second best ASX All Ordinaries share of the March quarter is Yancoal Australia Ltd (ASX: YAL). Yancoal shares gained 71% over the three months, finishing at $4.44 per share.

    Yancoal is Australia’s largest pure-play coal producer. It operates and manages a broad portfolio of coal mines across New South Wales, Queensland and Western Australia.

    The coal producer released some stellar full 2021 financial year results in February, buoying investor enthusiasm.

    Those results included a 56% leap in revenue from continuing operations to an all-time high of $5.4 billion. Net profit after tax (NPAT) rebounded from a $1 billion loss in FY20 to a $791 million gain in FY21.

    Yancoal rewarded shareholders by reinstating its dividend, with the company paying an unfranked 9.7% trailing dividend yield at current share prices.

    And that brings us to…

    The best ASX All Ordinaries performer in the March quarter

    Leading the pack was Stanmore Resources Ltd (ASX: SMR), which gained a whopping 83% over the quarter.

    Until its rebranding in April 2021, Stanmore Resources was called Stanmore Coal. Which gives you a fair indication of how the ASX All Ordinaries share earns its revenue.

    With both thermal coal (mostly used to generate electricity) and metallurgical coal prices rocketing, Stanmore also received some investor attention after releasing its own very strong FY21 results earlier in the quarter.

    Those results included a 125% year-on-year boost in underlying EBITDA, which reached $54 million. The coal producer ended 2021 with operating cash flow of $127 million, up from $28 million the previous year.

    At the current share price, this leading ASX All Ordinaries share pays a 4.3% trailing dividend yield, fully franked.

    The post The best ASX All Ordinaries shares of the March quarter unmasked appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Stanmore Resources right now?

    Before you consider Stanmore Resources, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Stanmore Resources wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/j3tMEDB

  • The Endeavour share price has notched up 4 all-time highs in a week. What’s happening?

    Four people on the beach leap high into the air.Four people on the beach leap high into the air.

    It’s been a bumpy ride for the S&P/ASX 200 Index (ASX: XJO) over the past couple of weeks or so. After a stellar March, April has seen the ASX 200 bounce around a little more. But no one seems to have told the Endeavour Group Ltd (ASX: EDV) share price.

    Put simply, it’s never been better for Endeavour shares. For one, this drinks and pubs share has hit not one, not two, but four all-time highs in the past week alone. Its latest and highest record high came last Friday, when Endeavour shares touched $7.72. As it stands today, Endeavour shares have now reached a five-day gain of 3.2%, and a 12.02% rise over the past month.

    Since Endeavour was spun out of Woolworths Group Ltd (ASX: WOW), housing Woolies’ pub and bottle shop portfolio, last year, its shares have now returned just shy of 27%. Not bad for roughly 10 months of ASX life.

    So what’s gone so right for Endeavour to clock four all-time highs in the past week?

    Why are Endeavour shares hitting all-time record highs?

    Well, the company did put out a notice today that one of its non-executive directors, Catherine West, has resigned from the company. West is departing to “focus on her other responsibilities in ASX and philanthropic organisations”. The company is working through regulatory approvals to name Anne Brennan as her replacement. But since we only found out this news today, it’s unlikely to have had much of an impact on the company’s shares.

    So let’s look at what else has been happening with the Endeavour share price.

    As we covered last week, Endeavour has been receiving a lot of love from some ASX brokers. Goldman Sachs in particular has singled out Endeavour as worthy of being a defensive ASX share. The broker cited Endeavour’s local supply chains and its inflation-resistant business model in justifying its buy rating and 12-month share price target of $8.

    Investors have inflation concerns front of mind right now, so it’s possible that Goldman’s assessment of the company turned some heads. Or it’s possible that investors are just looking for a blue-chip share in the consumer staples sector. Whatever the reason, it’s certainly been a good week for Endeavour shareholders.

    At the current Endeavour share price, this ASX 200 company has a market capitalisation of $13.79 billion, with a dividend yield of 3.27%.

    The post The Endeavour share price has notched up 4 all-time highs in a week. What’s happening? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Endeavour Group right now?

    Before you consider Endeavour Group, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Endeavour Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/oqpV69t

  • Why is the GrainCorp share price leaping 6% today?

    A happy farmers sifts his fingers through grain, indicating a good crop and higher pricesA happy farmers sifts his fingers through grain, indicating a good crop and higher prices

    The GrainCorp Ltd (ASX: GNC) share price is back in the green on Monday, launching 6% higher.

    The agribusiness company’s stock soared 5.75% on Friday on the release of a guidance upgrade. That’s reportedly encouraged one broker to upgrade its outlook for GrainCorp’s financial year 2022 results.

    At the time of writing, the GrainCorp share price is $9.74.

    For context, the S&P/ASX 200 Index(ASX: XJO) is also in the green today, having currently gained 0.12%.

    Let’s take a closer look at what could be driving the GrainCorp share price on Monday.

    Is this boosting the GrainCorp share price today?

    The GrainCorp share price is in the green amid reports the company’s recent guidance upgrade has bolstered bullish sentiment from one broker.

    The company told the market it expects Russia’s invasion of Ukraine will bolster its earnings on Friday.

    The conflict has dampened supply of grain in the Northern Hemisphere, increasing demand for Australian products.

    Additionally, Australia has revelled through a bumper grain season and expects good things from the rest of the year.

    GrainCorp now expects to report earnings before interest, tax, depreciation, and amortisation (EBITDA) of between $590 million and $670 million.

    It also expects its underlying net profit after tax (NPAT) to come to between $310 million and $370 million.

    What did the broker say?

    As a result of GrainCorp’s guidance upgrade, Wilsons has reportedly increased its earnings expectations for the company. According to the Australian Financial Review, the broker noted:

    While global demand is unlikely to diminish quickly, new crop grain price spreads will depend on the size of the Australian winter crop and exporters’ ability to secure supply chain access.

    The outcome of this dynamic will likely have a significant impact on [financial year 2023] earnings. While we continue to assume volumes and margins normalise, GrainCorp’s balance sheet will benefit from the significant cash flow, with core net cash forecast at $333 million in [financial year 2023].

    In what sounds like good news for its share price, the broker believes that happening will see GrainCorp with plenty of cash for investments or acquisitions.

    Wilsons also expects the company’s financial year 2022 to come to $1.52 of earnings per share (EPS) . It also predicts GrainCorp will offer 62 cents per share of dividends.

    Though, it’s reportedly expecting financial year 2023 to bring EPS of 61.9 cents and dividends of 36 cents per share.

    Wilsons is said to have a $7.80 price target on GrainCorp’s shares.

    The post Why is the GrainCorp share price leaping 6% today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in GrainCorp right now?

    Before you consider GrainCorp, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and GrainCorp wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/4InbKSY

  • Why IGO, Lake Resources, Regis Resources, and ResApp shares are charging higher

    Rising green bar graph with an arrow and a world map, symbolising a rising share price.

    Rising green bar graph with an arrow and a world map, symbolising a rising share price.

    In afternoon trade, the S&P/ASX 200 Index (ASX: XJO) has given back its morning gains and has dropped into the red. At the time of writing, the benchmark index is down 0.1% to 7,471.9 points.

    Four ASX shares that are not letting that hold them back today are listed below. Here’s why they are charging higher:

    IGO Ltd (ASX: IGO)

    The IGO share price is up over 3% to $14.12. This follows news that the battery materials miner has increased its takeover offer for nickel producer Western Areas Ltd (ASX: WSA). IGO has agreed to increase its offer to $3.87 cash per share, which is 15.2% higher than its previous proposal of $3.36 per share. This offer has been unanimously recommended by the Western Areas board, subject to a number of customary conditions.

    Lake Resources N.L. (ASX: LKE)

    The Lake share price has jumped 12% to $2.08. Investors have been buying this lithium developer’s shares after it announced a non-binding lithium offtake agreement with auto giant Ford. This is the second agreement Lake has signed in as many weeks, both for 25,000 tonnes per annum of lithium carbonate from the Kachi operation in Argentina.

    Regis Resources Limited (ASX: RRL)

    The Regis Resources share price is up 4% to $2.12. As well as getting a boost from a rise in the gold price, this morning this gold miner was the subject of a bullish broker note out of Credit Suisse. According to the note, the broker has retained its outperform rating and lifted its price target on the company’s shares to $2.60.

    ResApp Health Ltd (ASX: RAP)

    The ResApp share price has surged 22% higher to 11 cents. The catalyst for this was news that healthcare giant Pfizer has tabled a takeover offer. Pfizer has offered 11.5 cents cash per share, which values the digital health company at $100 million. ResApp recently announced positive results for a new novel smartphone-based COVID-19 screening test.

    The post Why IGO, Lake Resources, Regis Resources, and ResApp shares are charging higher appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/9uTWKyl

  • Can the AMP share price finally turn the corner in April?

    calculate earningscalculate earnings

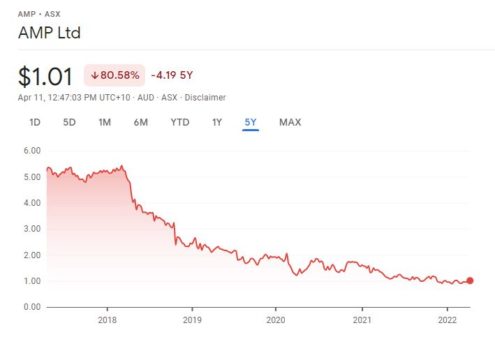
    AMP Ltd (ASX: AMP) shares have started this week in the green, up 0.5% at $1.01. This appears to be the new watermark price for the ASX financials company, according to my Fool colleague Zach.

    During March, the AMP share price climbed 2 cents from 95 cents to 97 cents — a 2.11% gain. By contrast, the S&P/ASX 200 Index (ASX: XJO) moved at triple the pace, up 6.4%.

    The AMP share price has been in a gradual downwards spiral since the Banking Royal Commission in 2018, which uncovered dastardly behaviour within many financial institutions. AMP was amongst the companies exposed for the worst conduct, prompting a restructure of the business that continues to play out today.

    Since then, the AMP share price has consistently fallen and is now about 80% down overall. It appears that AMP might have finally stopped the bleeding around the end of the third quarter of 2021, when the share price hit the $1 mark and seemed to settle there. It has been rangebound since then.

    Image source: Google Finance

    AMP’s restructure continues…

    The latest news on restructuring came on 28 March. AMP announced it had finalised the sale of its Global Equities and Fixed Income division to Macquarie Group Ltd (ASX: MQG).

    As my fellow Fool Sebastian reported, the sale helps set AMP up for the planned demerger of its Collimate Capital division. The sale to Macquarie Asset Management will see roughly $47 billion in assets under management transferred to Macquarie. In return, AMP will receive $63 million in cash, with the possibility of another $75 million down the road, depending on some conditions.

    Boosted profitability ahead?

    Bloomberg Intelligence analysts Matt Ingram and Jack Baxter say AMP’s restructuring efforts should boost profitability in the future.

    In a note last week, Ingram and Baxter said:

    AMP’s extensive restructuring, which should be complete by June 30, may lift 2021’s 9% ROE [return on equity] and 64-basis point margin, particularly given AMP Capital’s below group 40-basis point result in 2021.

    AMP said the bank’s margin would fall to 1.5% this year from 2021’s 1.62%, but we believe 2023 may be better — AMP’s guided cash-rate rise from as early as June may lift returns.

    It needs to fix the Australian wealth management unit which returned just 5.4% in 2021, but capital reallocation to a higher-return business may boost ROE.

    Credit Suisse analysts say consumers are starting to regain confidence in professional advisors.

    “Inflows continue to improve across the industry underpinned by structural growth in the demand for advice and a return of consumer confidence to the advice industry,” they said in a note to clients.

    Outflows at AMP have reduced substantially over the past few weeks, the broker remarked.

    Could AMP embark on a dividend splash?

    Ingram and Baxter speculated that $381 million in total surplus capital (as of 31 December 2021), which AMP generated through capital budgeting initiatives last year, could fund a dividend bonanza for ASX investors.

    “AMP could distribute A$400-$600 million in 2022, lifting dividend yield above 14% and smashing consensus’ 1.5 Australian cent dividend on better profit and up to A$350 million surplus capital,” they noted.

    In fact, the pair reckon AMP’s surplus could “support a 2022 dividend payout of 50%”.

    The post Can the AMP share price finally turn the corner in April? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in AMP right now?

    Before you consider AMP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and AMP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Bronwyn Allen owns Macquarie Group Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/qV4MCpO

  • What’s with the Woodside share price on Monday?

    A young woman looks at something on her laptop, wondering what will come next.A young woman looks at something on her laptop, wondering what will come next.

    The Woodside Petroleum Limited (ASX: WPL) share price had a strong start to the trading week.

    Shares in the S&P/ASX 200 Index (ASX: XJO) energy giant closed on Friday at $32.40 and rocketed up 1.1% to $32.75 in the first 15 minutes of trading today.

    That strength may be based on early morning reports of rising crude oil prices.

    But momentum turned the other way an hour later. At the time of writing the Woodside share price is down 0.9%, at $32.11 per share.

    Crude oil markets in flux

    There are two big and constantly-changing factors impacting crude oil prices over the past week. That is, in turn, impacting the Woodside share price.

    Pressuring oil prices higher is Russia’s ongoing war with Ukraine.

    Among the world’s top oil producers and exporters, Russia has been hit by a series of sanctions from Western nations.

    Some nations have gone so far as to ban imports of Russian oil. And even in countries that still allow Russian crude, which remains the majority, companies are increasingly hesitant to take delivery.

    This came as global supplies were already struggling to keep up with resurgent demand as the world emerged from the pandemic lockdowns and energy use soared.

    Which brings us to the opposing force currently putting downward pressure on oil prices, and the Woodside share price.

    Namely, the events unfolding in China, the world’s most populous nation and second-largest economy.

    While most of the world has moved towards living with the virus, China remains intent on its zero-COVID strategy. A strategy that’s now seeing Shanghai, a city of some 26 million people, placed in lockdown.

    Warren Patterson is the head of commodities strategy at ING Groep in Singapore.

    Commenting on the opposing impacts of curtailed Russian crude oil supplies and diminished demand from China, Patterson said (quoted by Bloomberg):

    There seems to be no end in sight for the current lockdowns, and clearly the longer this goes on, the more of a demand hit we will see. While the amount of impacted Russian supply is smaller-than-expected at the moment, this could change very quickly if the situation in Ukraine deteriorates further.

    Take note of that last line, as it could have ramifications for the Woodside share price.

    Things “could change very quickly”. Depending on which direction they unfold, that could see oil prices retrace or send them sharply higher.

    Woodside share price snapshot

    While Brent crude oil prices have slipped almost 2% over the past 24 hours, the black gold remains up 30% from 1 January.

    That’s helped boost the Woodside share price nearly 42% since the opening bell on 4 January. That’s compared to a 1% loss posted by the ASX 200.

    The post What’s with the Woodside share price on Monday? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Woodside Petroleum right now?

    Before you consider Woodside Petroleum, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Woodside Petroleum wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/nGDC6kg

  • These are the 10 most shorted ASX shares

    Iron ore bear market Fortescue dissapointed man and shadow bear with a tumbling down stock market

    Iron ore bear market Fortescue dissapointed man and shadow bear with a tumbling down stock marketOnce a week I like to look at ASIC’s short position report to find out which shares are being targeted by short sellers.

    This is because I believe it is well worth keeping a close eye on short interest levels as high levels can sometimes be a sign that something isn’t quite right with a company.

    With that in mind, here are the 10 most shorted shares on the ASX this week according to ASIC:

    • Flight Centre Travel Group Ltd (ASX: FLT) continues its long run as the most shorted ASX share after its short interest rose to 18%. Short sellers appear convinced that the market is being too optimistic on the travel market recovery.
    • Betmakers Technology Group Ltd (ASX: BET) has seen its short interest ease slightly to 12.7%. Short sellers appear to have been targeting this betting technology company over valuation concerns.
    • Nanosonics Ltd (ASX: NAN) has short interest of 11.7%, which is down slightly week on week. This infection prevention company’s shares have come under pressure after it made a big change to its sales model in the United States.
    • Webjet Limited (ASX: WEB) has short interest of 10.2%, which is down slightly week on week. As with Flight Centre, short sellers appear to believe the travel market recovery could take longer than expected.
    • Polynovo Ltd (ASX: PNV) has seen its short interest remain flat at 9.5%. Short sellers aren’t giving up on this medical device company even after a solid trading update last week.
    • EML Payments Ltd (ASX: EML) has seen its short interest reduce slightly to 9.4%. Regulatory risks and valuation concerns appear to be behind this high level of short interest.
    • Kogan.com Ltd (ASX: KGN) has seen its short interest rise to 9%. This online retailer has been performing very poorly in FY 2022 and only delivered modest first half growth thanks to an acquisition. Short sellers don’t appear to believe things will improve quickly.
    • Zip Co Ltd (ASX: Z1P) has seen its short interest pullback to 8.3%. Short sellers have been going after this buy now pay later provider amid rising competition, increased marketing costs, and significant cash burn.
    • AMA Group Ltd (ASX: AMA) has 8.3% of its shares held short, which is flat week on week. This crash repair company reported a very disappointing half year loss of $46.3 million in February.
    • Omni Bridgeway Ltd (ASX: OBL) has seen its short interest ease to 8%. Concerns that this litigation funder could be impacted by an overhaul of class action laws may be behind this short interest.

    The post These are the 10 most shorted ASX shares appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Betmakers Technology Group Ltd, EML Payments, Kogan.com ltd, Nanosonics Limited, POLYNOVO FPO, and ZIPCOLTD FPO. The Motley Fool Australia owns and has recommended EML Payments, Kogan.com ltd, and Nanosonics Limited. The Motley Fool Australia has recommended Betmakers Technology Group Ltd, Flight Centre Travel Group Limited, and Webjet Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/PL6AmWM