Category: Stock Market

  • Black gold! Here’s how well ASX energy shares performed over the March quarter

    an oil worker holds his hands in the air in celebration in silhouette against a seitting sun with oil drilling equipment in the background.an oil worker holds his hands in the air in celebration in silhouette against a seitting sun with oil drilling equipment in the background.

    Perhaps more than any other sector, ASX energy shares had a wild ride over the quarter just gone. During the three months to 31 March, global energy prices went on a rollercoaster, largely as a consequence of the disruptions caused by the war in Ukraine and subsequent sanctions levied on the Russian economy.

    As a result, the world has seen record-high oil, gas, and coal prices which, of course, have flowed through to the bowser, the supermarket, and almost every corner of the economy. But how did the companies that drill, pump, and mine oil, gas, and coal out of the ground fare during these tumultuous times?

    Well, let’s first check out the ASX’s largest energy share, Woodside Petroleum Limited (ASX: WPL),

    Woodside started 2022 at $21.93 a share. On 31 March, this energy giant finished up at $32.10. That’s a rather stunning rise of 46.37% for the March quarter. This arguably proves how valuable soaring energy prices can be for an ASX energy share.

    ASX energy shares shoot the moon over March quarter

    But did other energy shares experience similar moves? Beach Energy Ltd (ASX: BPT) is another company in this space worth checking out. Beach shares were priced at $1.26 each on New Year’s Eve. Fast forward to 31 March, and we saw the company shoot up to $1.56. That’s a far less enthusiastic, but still solid, rise of 23.81%.

    Santos Ltd (ASX: ATO) is another ASX energy heavyweight. It was going for $6.31 a share at the start of the quarter ending 31 March. But by the end, we saw this company reach $7.74 — a gain of 22.66%.

    Turning to an ASX coal miner, let’s examine how Whitehaven Coal Ltd (ASX: WHC) shares performed over the same period. Whitehaven ended 2021 at a share price of $2.61. But three months later, the company had reached $4.15 a share. That’s a whopping gain of 59% in three months.

    So, all in all, it has been a very lucrative quarter for ASX energy shares. Whitehaven was the clear winner, followed by Woodside, with both companies clocking gains of more than 45%. But all of these companies managed to appreciate by more than 20% over the first quarter of 2022. No doubt ASX energy investors will be hoping for a repeat performance during the current quarter ending 30 June. But we shall have to wait and see.

    The post Black gold! Here’s how well ASX energy shares performed over the March quarter appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/cNon2W3
  • 3 charts that show why Amazon is an unstoppable growth stock

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    man on an iPad looking at chart of an increasing share price

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    It’s easy to look at a stock like Amazon (NASDAQ: AMZN) and think that at $1.7 trillion, it can’t possibly go much higher in value than where it is today. But as long as a company has ways to continue growing, there’s no reason its valuation won’t also increase. And there’s no danger for this cash-rich business to run out of opportunities anytime soon. 

    In just three charts, investors can see why, despite its massive size, Amazon can still be an excellent long-term investment.  

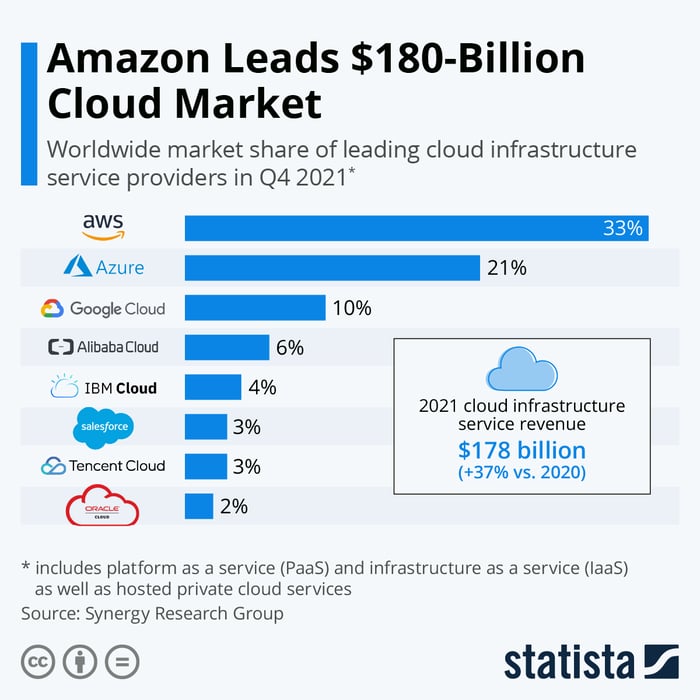
    A leader in the cloud market

    Although Amazon is primarily known for being a top online retailer, its cloud business, Amazon Web Services (AWS), has also made a name for itself in the industry. Many top companies use AWS, including software company Intuit, top bank HSBC, and COVID-19 vaccine maker Moderna. And as a leader in the cloud market, it’ll undoubtedly continue to be a top choice for many businesses that expand their presence online. 

    Statista chart showing the leader in the cloud market.

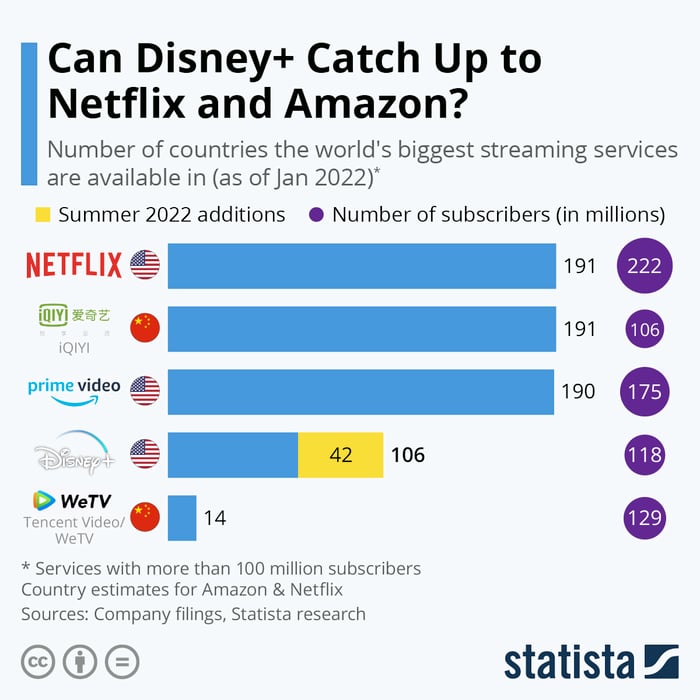
    Its streaming service is among the top in the industry

    Amazon Prime Video has over 175 million subscribers and is among the top streaming services in the world. An important caveat here is that Amazon Prime Video is included within an Amazon Prime subscription, and so these numbers likely would be lower if the company were only offering it as a stand-alone service the way Netflix and Walt Disney do their services. But it’s another example of how Amazon has room to grow in another area — streaming.

    Statista chart showing the world's largest streaming services.

    Last year, the company secured a deal with the NFL where it would spend a reported $1 billion per year for exclusive rights for Thursday Night Football games. It’s a 10-year deal that starts next year and will help diversify its streaming services; Netflix, for comparison, does not have any live sports available for subscribers to watch. Amazon can spend a lot more money to expand into its streaming business to make it more robust and possibly lure subscribers away from other services. 

    Amazon has been investing in various industries

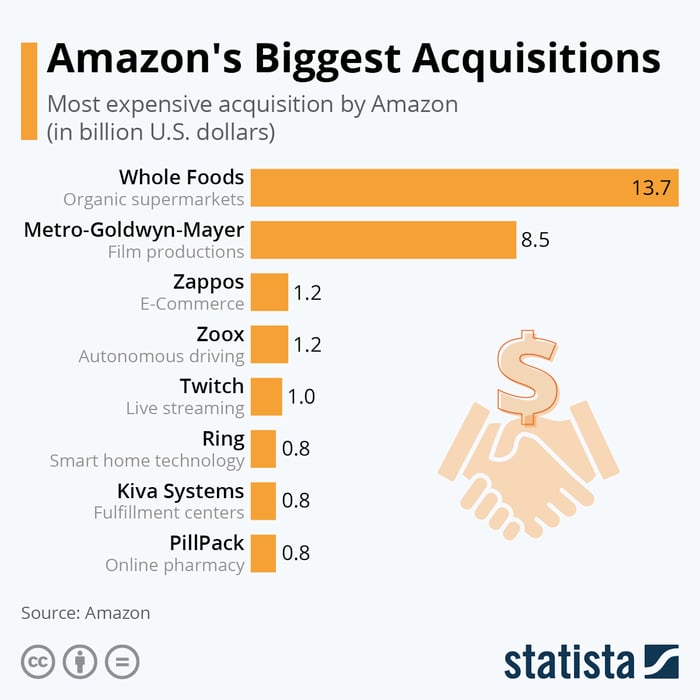
    In 2021, Amazon generated $46 billion in cash from its day-to-day operating activities. The year before that, its cash from operations was north of $66 billion. The company is bringing in truckloads of cash every year and that puts it in an excellent position to spend on acquisitions to expand its business even further. Here are the biggest deals the company has made in recent years:

    Statista chart showing Amazon's largest acquisitions.

    From autonomous driving to supermarkets to an online pharmacy, Amazon has been expanding its reach into various sectors. It can grow deeper into any one of these sectors or it can pursue yet another new one altogether. Either way, given the cash that Amazon generates each year, it won’t struggle to find a new growth avenue to pursue.

    Should you invest in Amazon today?

    Amazon just continues to get bigger over the years. In 2021, revenue of $469.8 billion was more than 67% higher than the $280.5 billion that the company reported in 2019, before the pandemic emerged. Online shopping is more popular than ever before and even if that slows down in a return to normal, the company can simply shift to other areas of its business, such as pumping more money into Whole Foods or developing its telehealth capabilities. 

    For buy-and-hold investors, Amazon is one of the safer growth stocks to hang on to over the long term. The business is a beast when it comes to cash flow, and with so many opportunities for growth, this is an unstoppable company to invest in. Up just 6% in the past year, while the S&P 500 has climbed 14%, the stock has underperformed the markets of late — but that isn’t a trend investors should expect to continue. It may only be a matter of time before this growth stock starts rallying again, and now may be as good a time as any to load up on it. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post 3 charts that show why Amazon is an unstoppable growth stock appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Amazon right now?

    Before you consider Amazon , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Amazon wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    David Jagielski has no position in any of the stocks mentioned. John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Amazon, Netflix, and Walt Disney. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended HSBC Holdings, Intuit, and Moderna Inc. and has recommended the following options: long January 2024 $145 calls on Walt Disney and short January 2024 $155 calls on Walt Disney. The Motley Fool Australia has recommended Amazon, Netflix, and Walt Disney. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/nKwYROt

  • Why Ardent Leisure, GQG, Magellan, and Melbana shares are charging higher

    Green arrow going up on stock market chart, symbolising a rising share price.

    Green arrow going up on stock market chart, symbolising a rising share price.

    In afternoon trade, the S&P/ASX 200 Index (ASX: XJO) is on course to record its second successive daily decline. At the time of writing, the benchmark index is down 0.5% to 7,450.2 points.

    Four ASX shares that are not letting that hold them back are listed below. Here’s why they are charging higher:

    Ardent Leisure Group Ltd (ASX: ALG)

    The Ardent Leisure share price is up 7% to $1.39. This follows news that the entertainment company has signed an agreement to sell its Main Event business in the United States for A$1.1 billion. Ardent plans to return approximately A$430 million or A$0.90 per share to shareholders following completion of the transaction. The company will now be solely focused on its Australian Theme Parks business.

    GQG Partners Inc (ASX: GQG)

    The GQG Partners share price is up 5% to $1.47. Investors have been buying the fund manager’s shares following the release of its latest funds under management (FUM) update. GQG had a decent month, with its FUM growing 3.5% over the period to US$92.9 billion. This brought its quarterly net inflows to US$3.4 billion.

    Magellan Financial Group Ltd (ASX: MFG)

    The Magellan share price has jumped 11.5% to $17.26. This also follows the release of a FUM update. According to the release, Magellan reported another $1.1 billion of net fund outflows for the period between 11 March and 31 March. However, this is a big improvement on recent trends, which investors appear to believe could be a sign that the worst is now over. Furthermore, thanks to favourable market movements, Magellan’s total FUM actually increased by $0.9 billion

    Melbana Energy Ltd (ASX: MAY)

    The Melbana Energy share price has surged 26% higher to 17 cents. This morning the energy explorer revealed that a significant oil pay has been defined in the Marti structure. The release also highlights that the volume of oil in place from the first (Amistad) structure has been independently estimated to contain 2.5 billion barrels of oil in place with a combined prospective resource of 119 million barrels of oil.

    The post Why Ardent Leisure, GQG, Magellan, and Melbana shares are charging higher appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/y8BPf6Z

  • Here’s why the Galan Lithium share price is defying today’s ASX sell-off

    Smiling man sits in front of a graph on computer while using his mobile phone.Smiling man sits in front of a graph on computer while using his mobile phone.

    The Galan Lithium Ltd (ASX: GLN) share price has been enjoying a day in the green today.

    In early trade, this ASX lithium share surged 7% to $2.29 before pulling back to the current share price of $2.17. This is 1.4% higher than yesterday’s close. In contrast, the S&P/ASX 200 Index (ASX: XJO) is sliding 0.53% today.

    Let’s take a look at what might be driving the Galan Lithium share price today.

    Lithium drilling result

    Galan reported “drilling success” at the company’s Hombre Muerto West lithium project in Catamarca Province, Argentina. The announcement before market open saw the Galan Lithium share price shoot up in the first hour of trading.

    The company revealed it has completed the first diamond drill hole, known as PP-02-22, at the project. Drilling at the site, within the Pata Pila licence area, reached a depth of 450m.

    Galan said the result extends the lithium brine potential an additional 800m from existing drill hole PP-01-19 to within 1km of the adjacent Livent tenement boundary.

    The results will be included in the company’s project mineral resource update, due for completion in the third quarter of 2022.

    Commenting on the results which appear to have spurred the Galan Lithium share price, managing director Juan Pablo Vargas de la Vega said:

    This exploration diamond hole has further unlocked the potential of the world-class lithium brine resource held at the HMW Project.

    The results have enhanced our hydrogeological modelling, a key to confirmation of Reserve estimates, and delivered further Mineral Resource upside at HMW.

    Following the new exploration target areas identified by the recent TEM geophysical survey, we now look forward to aggressively drilling these additional potential HMW Mineral Resource expansion zones from this quarter through the rest of 2022.

    Galan also advised it has filled the pilot plant S1 pond with brine. Evaporation testing is ready to start soon. The company said this is a “major milestone” marking the start of large-scale piloting activities at the project.

    Galan Lithium share price snapshot

    The Galan Lithium share price has exploded almost 240% in the past year while it is climbing nearly 11% year to date.

    For perspective, the benchmark ASX index returned nearly 8% in the past year.

    Galan Lithium has a market capitalisation of about $657 million.

    The post Here’s why the Galan Lithium share price is defying today’s ASX sell-off appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Galan Lithium right now?

    Before you consider Galan Lithium , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Galan Lithium wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/wSPYola

  • Why not all ASX lithium shares are winners from surging commodity prices

    ASX lithium shares are among the hottest recent investment trends thanks to the looming supply deficit for the battery-making material.

    But not all of these miners are set to be winners from surging prices for lithium, according to UBS.

    This is despite the spot price for the commodity hitting record highs due to projected demand for electric vehicles (EVs) and green energy projects.

    Upgraded lithium forecasts

    A number of experts have warned that supply is not keeping up with demand, and even UBS has been forced to upgrade its lithium price forecasts.

    “We revise our near-term lithium prices reflecting continued tightness in the market and with no signs yet of easing,” said the broker.

    “We lift our 22E spodumene forecast approximately 17% to $4485/t…. Our [long-term] prices remain under review.”

    Not all ASX lithium shares are built the same

    The surging Liontown Resources Limited (ASX: LTR) share price, Allkem Ltd (ASX: AKE) share price, and Pilbara Minerals Ltd (ASX: PLS) share price may give investors the impression the rising lithium tide will lift all boats equally.

    But the broker warned that not every ASX lithium share will necessarily benefit from price rises. This is because there is often a difference between the “spot price” and the “realised price” that a producer receives.

    There are several reasons for the gap in the prices. The first is the composition of the ASX lithium miner’s order book. This means the proportion of sales done on a fixed-price agreement compared to those that reference the spot market, explained UBS.

    Another factor is the significant discount applied to ASX lithium miners that produce brine versus technical grade carbonate.

    A similar issue exists for lithium producers that sell spodumene below the industry’s SC6% benchmark. It’s worth noting that the discount applied to lower grade spodumene is not as great as brine.

    Finally, there’s a timing issue. The reported sales by ASX lithium producers reflect realised prices from the previous period. The lag can exaggerate the differences between realised prices and spot prices.

    The type of ASX lithium shares that do best in this market

    But UBS believes the lithium market will evolve much like the iron ore market, where the industry gravitates closer to spot pricing.

    “We draw analogies to the breakdown of the annual iron ore contract where market dynamics evolved to a point where the price difference between spot and contracted pricing made long-term fixed-price agreements untenable,” said UBS.

    “There has been clear messaging by (some of) the producers to shift closer to pricing based off spot.”

    From this perspective, Allkem may be better placed than others to benefit from rapidly rising spot prices. The miner recently changed its annual contracts that previously had fixed prices. It contracts now use indices to set realised prices with an average bimonthly adjustment.

    The post Why not all ASX lithium shares are winners from surging commodity prices appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Brendon Lau owns Orocobre Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/I3r7T4h

  • Why has the De Grey share price tumbled 14% in a month?

    plummeting gold share priceplummeting gold share price

    The De Grey Mining Limited (ASX: DEG) share price has been heading south over the course of the past month.

    Lately, the depreciation in the price of gold has weakened investor sentiment, causing a sell in the gold miner’s shares.

    Since this time last month, De Grey shares have lost around 14% in value, making it one of the worst performers across the sector.

    In retrospect, fellow miner, Regis Resources Ltd (ASX: RRL)’s share price has fallen by 3% across the same timeframe.

    At the time of writing, De Grey shares are swapping hands for $1.17, down 3.31%.

    What’s happened to De Grey shares lately?

    A common theme with gold mining companies, the De Grey share price has been sold off following the decline in gold prices.

    Traditionally, investors flock to the yellow metal as a safe-haven asset when there is uncertainty in the market.

    However, with the world slowly moving past COVID-19, and the Russian/Ukrainian war in its second month, it appears investors have regained confidence in the market.

    The S&P/ASX 200 Index (ASX: XJO) is up 4.7% in a month, rebounding from its March low of 6,968 points.

    This has sent the price of gold to trade around US$1,922 per ounce, down almost 4% since 7 March.

    In contrast, when the war was still relatively new, the precious metal soared above the psychological US$2,000 barrier.

    As such, De Grey shares were trading at $1.365 at that time.

    De Grey share price snapshot

    Over the past 12 months, the De Grey share price has repaid relatively flat returns to investors, up 2%.

    However, when looking at year to date, its shares have travelled in circles, with a loss of 3% for the period.

    On valuation grounds, De Grey commands a market capitalisation of about $1.66 billion, with over 1.4 billion shares on hand.

    The post Why has the De Grey share price tumbled 14% in a month? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in De Grey Mining right now?

    Before you consider De Grey Mining, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and De Grey Mining wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/v5NI1EB

  • Why this broker is bearish on the A2 Milk share price

    a woman stands with her hand to the side of her head and a sad, slightly distressed look to her expression while holding a large glass of milk in her other hand.

    a woman stands with her hand to the side of her head and a sad, slightly distressed look to her expression while holding a large glass of milk in her other hand.The A2 Milk Company Ltd (ASX: A2M) share price is pushing higher on Thursday.

    In afternoon trade, the struggling infant formula company’s shares are up 1% to $5.06.

    While this gain is positive, it is little consolation for shareholders who have watched the A2 Milk share price fall 36% over the last 12 months.

    Where next for the A2 Milk share price?

    Unfortunately for shareholders, the small number of brokers that are bullish on the A2 Milk share price just got even smaller.

    Up until recently, the team at Citi were positive on A2 Milk and had maintained a buy rating on its shares since the release of the company’s full year results for FY 2021 in August.

    At that point, the broker had a buy rating and $7.20 price target on its shares and was encouraged by improvements in its inventory levels and the strength of its brand in China.

    However, Citi has now become bearish on the company’s prospects and has downgraded its shares to a sell rating and slashed the price target on them to $4.80.

    Based on the current A2 Milk share price, this implies potential downside of 5.1%.

    Why is Citi bearish?

    Citi made the move largely on concerns that COVID lockdowns impacting Chinese ports could cause supply issues in the country. It also highlights that recent reseller pricing on Chinese ecommerce platforms has been weak, which could be an indication of softening demand.

    In addition, Citi has recently noted that dairy processor Synlait Milk Ltd (ASX: SM1) released its half year results recently. Within its presentation, A2 Milk’s partner advised that an onsite audit will be conducted by the Ministry for Primary Industries on behalf of China’s SAMR in June/July. This is later than previously expected and Citi has warned that there is no certainty that A2 Milk will secure approval again.

    If approval were not granted, it would be a huge blow given that it would shut out A2 Milk’s China label products from mother and baby stores and domestic online channels. These make up over a third of sales at present. The broker also fears that it would damage its brand and potentially sales of its English label product.

    Though, Citi concedes that should it gain approval, it could position it to win a greater share of the Chinese market.

    Time will tell what happens, but Citi isn’t willing to hold its shares while it waits to find out.

    The post Why this broker is bearish on the A2 Milk share price appeared first on The Motley Fool Australia.

    Should you invest $1,000 in A2 Milk right now?

    Before you consider A2 Milk, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and A2 Milk wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended A2 Milk. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/ktPvEG7

  • 2 ASX dividend shares expected to pay mega income yields

    ASX 200 shares santa rally a group of three people reach to the sky with both hands as money rains down on top of them.ASX 200 shares santa rally a group of three people reach to the sky with both hands as money rains down on top of them.

    ASX dividend shares that are paying high-income yields to investors may be attractive in the current environment.

    Interest rates are expected to go higher this year. But the dividend yields could still be much higher than bank interest rates.

    According to analyst forecasts, some businesses are expected to pay particularly high dividend yields over the next year or two. Here are two:

    Adairs Ltd (ASX: ADH)

    Adairs describes itself as Australia’s largest specialty retailer of home furnishings and home decoration products. It operates three brands – Adairs, Mocka, and Focus on Furniture. Mocka is a home and living products designer and retailer.

    It’s currently rated as a buy by the broker Morgans, with a price target of $3.50. That implies a potential rise of around 21% over the next year on its current share price of $2.88. The broker noted there continues to be good demand for its products.

    Since the start of 2022, the Adairs share price has fallen by almost 30%. This has boosted the estimated future dividend yield from the ASX dividend share.

    At the current Adairs share price, Morgans thinks Adairs could pay a grossed-up dividend yield of 9.4% in FY22 and 12.9% in FY23.

    Adairs plans to open more stores, upsize some existing stores, grow its online sales and become more efficient. The company points to the growth of its overall floorspace and its membership as positives that can help sales.

    Morgans thinks the Adairs share price is valued at 9x FY22’s estimated earnings and 7x FY23’s estimated earnings.

    Accent Group Ltd (ASX: AX1)

    Accent Group is one of the largest retailers of shoes in Australia. It has a mixture of its own brands and also acts as the distributor for many other global shoe brands.

    Some of this ASX dividend share’s brands include The Athlete’s Foot, Dr Martens, Glue Store, Hoka, Hype, Kappa, Nude Lucy, Merrel, Platypus, Skechers, Stylerunner, and Reebok.

    The company’s first half of FY22 was impacted by mandated store closures. But, after the wave of the Omicron variant, the company said that like for like sales in the four weeks between 24 January and 20 February “improved significantly” and were in line with last year.

    It also continued to drive full price, full margin sales. Over the first eight weeks of the second half, the gross profit margin percentage was “in line with expectations and ahead of the prior year”.

    The ASX dividend share is working on expanding its store network, growing its online sales, and adding more quality brands.

    UBS currently rates it as a buy, with a price target of $2.50. That implies a potential rise of 59% on its current price of $1.57. The broker notes the high level of store openings that the company is undertaking.

    On the broker’s numbers, the Accent share price is valued at 11x FY23’s estimated earnings, with a potential grossed-up dividend yield of 11.7% in FY23.

    The post 2 ASX dividend shares expected to pay mega income yields appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ADAIRS FPO. The Motley Fool Australia owns and has recommended ADAIRS FPO. The Motley Fool Australia has recommended Accent Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/wNFTxDc

  • The Core Lithium share price is tumbling again. What’s going on?

    A surprised man sits at his desk in his study staring at his computer screen with his hands up while he watched the Sezzle share price fall despite the company accepting a takeover offer from Zip CoA surprised man sits at his desk in his study staring at his computer screen with his hands up while he watched the Sezzle share price fall despite the company accepting a takeover offer from Zip Co

    The Core Lithium Ltd (ASX: CXO) share price is in the red again today, bringing its losses this week so far to almost 14%.

    While the stock surged higher on Monday and in early trade on Tuesday – reaching a new all-time high of $1.68 – it has been plunging lower since.

    The lithium developer’s stock closed 8% lower on Tuesday before sliding another 6% on Wednesday.

    At the time of writing, the Core Lithium share price is $1.32, 3.99% lower than its previous close. That’s also 21% lower than its shiny new all-time high.

    For context, the broader market is also in the red on Thursday. Right now, the All Ordinaries Index (ASX: XAO) and S&P/ASX 200 Index (ASX: XJO) are both down almost 0.6%.

    Let’s take a look at how the ASX lithium share is trading compared to its peers today.

    What’s happening with the Core Lithium share price?

    The Core Lithium share price is slumping alongside many of its peers on Thursday.

    Right now, shares in Liontown Resources Limited (ASX: LTR) and IGO Ltd (ASX: IGO) are also in the red, down 4.27% and 3.1% respectively. Additionally, AVZ Minerals Ltd (ASX: AVZ) slumped by 4% in morning trade before staging a recovery.

    Interestingly, each of the above-named lithium-focused stocks hit all-time highs on Friday. Thus, today’s falls could be the result of extended price taking.

    The falls also come despite good news about lithium demand hitting the market on Tuesday.

    Then, Mineral Resources Limited (ASX: MIN) announced that, due to “unprecedented” demand for the battery-making material, it will be upping its production.

    It follows an update from Allkem Ltd (ASX: AKE) on its lithium outlook for the June quarter, released last week.

    The company expects the price of both lithium and spodumene to continue rocketing this quarter, reaching around US$35,000 per tonne and US$5,000 per tonne respectively.   

    Despite the recent positive news from its peers, the Core Lithium share price has tumbled almost 14% so far this week.

    Though, it’s still 111% higher than it was at the start of 2022. It’s also 478% higher than it was this time last year.

    The post The Core Lithium share price is tumbling again. What’s going on? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Core Lithium right now?

    Before you consider Core Lithium, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Core Lithium wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/OqoK3ET

  • The Wesfarmers share price tumbled 15% in the March quarter. What’s next?

    man grimaces next to falling stock graph

    man grimaces next to falling stock graphThe S&P/ASX 200 Index (ASX: XJO) ended up having a positive, if spectacularly volatile, first quarter of 2022. For the three months to 31 March, the ASX 200 gained 0.7%. But the same cannot be said of the Wesfarmers Ltd (ASX: WES) share price. 

    Wesfarmers shares had a quarter to forget. This ASX 200 industrial and retail conglomerate started the year at $59.30 a share. But by 31 March, Wesfarmers had fallen to just $49.59 a share. That represents a steep loss of 14.99%. This is a rather unusual performance for Wesfarmers, which has traditionally been rewarded with a strong and steady share price performance from investors, not to mention a healthy price-to-earnings (P/E) multiple.

    But since the owner of Target, OfficeWorks, Kmart, and Bunnings hit a new all-time high of just over $66 a share in August last year, we have now seen investors shave more than a quarter off of the Wesfarmers share price.

    So after these rather steep falls, what does the market have in store for Wesfarmers going forward? Well, we can’t of course know for sure. But let’s take a look at what some top ASX brokers reckon.

    Is the Wesfarmers share price a buy today?

    As we covered yesterday, Morgans is one broker who is bullish on Wesfarmers shares right now. Morgans currently rates Wesfarmers as an add, with a 12-month share price target of $58.50. That implies a potential upside of almost 19% over the coming year. 

    Morgans loves the company’s “highly regarded management team”, and reckons Wesfarmers has “one of the highest quality retail portfolios in Australia”. The broker assesses the company’s balance sheet as healthy and has told investors that the recent weakness in the Wesfarmers share price is a “good entry point for long-term investors”.

    It is also foreseeing strong dividend growth from the ASX 200 share over the next few years. It has pencilled in dividends worth $1.62 per share for FY2022 and $1.81 per share for FY2023.

    No doubt that will be music to existing Wesfarmers shareholders’ ears. But we’ll have to wait and see if these optimistic projections indeed come to pass. 

    In the meantime, the Wesfarmers share price currently gives this ASX 200 share a market capitalisation of $56 billion, with a dividend yield of 3.45%. 

    The post The Wesfarmers share price tumbled 15% in the March quarter. What’s next? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Wesfarmers right now?

    Before you consider Wesfarmers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Wesfarmers wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Wesfarmers Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/HB5E9QN