Category: Stock Market

  • Why is the A2 Milk (ASX:A2M) share price falling today?

    a woman with a sad face looks to be receiving bad news on her phone as she holds it in her hands and looks down at it.

    a woman with a sad face looks to be receiving bad news on her phone as she holds it in her hands and looks down at it.

    The A2 Milk Company Ltd (ASX: A2M) share price is trading lower on Tuesday morning.

    At the time of writing, the embattled infant formula company’s shares are down 0.5% to $5.40.

    Why is the A2 Milk share price dropping?

    Today’s decline by the A2 Milk share price appears to have been driven by the release of an announcement out of smaller rival, Bubs Australia Ltd (ASX: BUB)

    According to the release, Bubs is going head to head with A2 Milk by launching Bubs Supreme infant formula and toddler milk with natural A2 beta-casein protein.

    The release notes that the Bubs Supreme formula range will be on shelf in 500 Coles Group Ltd (ASX: COL) supermarkets from May. This expands the company’s shelf presence in Coles stores, which already includes Bubs easy-digest goat milk formula and Bubs Organic grass-fed cow’s milk formula.

    Bubs estimates that the global A2 beta-casein protein milk market is valued at US$1.23 billion and is forecasting it to reach US$2.6 billion by 2026.

    Is this bad news for A2 Milk?

    Whether Bubs will ever win a decent share of the A2 beta-casein protein milk market is difficult to say.

    It has launched countless new products in recent years, diluting its original unique selling point as being a goat milk infant formula company.

    For example, in 2020 the company talked up its launch of a Vita Bubs vitamins range. It appointed Jennifer Hawkins as its brand ambassador and spoke about its $2.3 billion opportunity in the Australian vitamin and mineral supplements category.

    However, almost two years later, despite being ranged in 400 Chemist Warehouse stores at launch, the Vita Bubs product didn’t even get a mention with its first half results.

    So, just like Blackmores Limited (ASX: BKL) probably wasn’t quaking in its boots over that launch, chances are that A2 Milk won’t be over this launch. Which may explain why there has only been a reasonably subdued response by the A2 Milk share price today.

    But time will ultimately tell what happens.

    The post Why is the A2 Milk (ASX:A2M) share price falling today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in A2 Milk right now?

    Before you consider A2 Milk, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and A2 Milk wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended A2 Milk and BUBS AUST FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/SKYdnVC

  • Why Tesla shares are up ahead of ‘Delivery day’

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

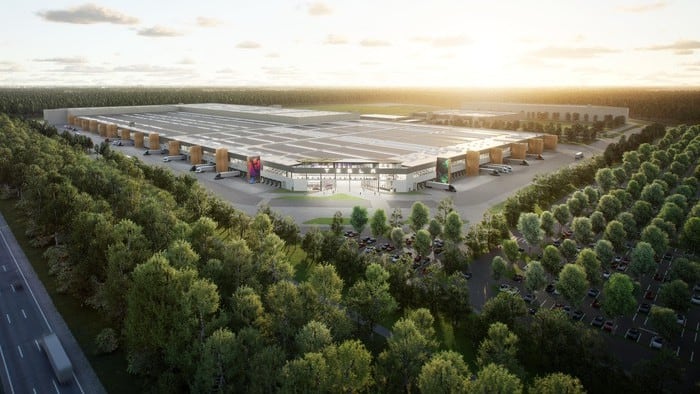
    Berlin Tesla

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    What happened

    Tesla (NASDAQ: TSLA) stock jumped 4% to start the week on Monday morning with the initial deliveries from the company’s new gigafactory near Berlin imminent. The early pop settled back to a gain of 3% as of 11:40 a.m. ET. 

    So what

    Tesla CEO Elon Musk has reportedly arrived in Germany ahead of a big opening ceremony for the company’s new Berlin-Brandenburg gigafactory. According to Twitter users who follow Musk’s travel and other Tesla-related news, Musk landed at the Berlin airport about 10 hours after leaving Austin, Texas. Pictures of preparations outside the factory for the grand opening ceremony event have also been posted on social media. German Chancellor Olaf Scholz will also attend Tuesday’s “Delivery Day” opening, according to Yahoo! Finance. 

    Now what

    Earlier this month, the facility received its final environmental permits, which listed several conditions the company needed to achieve. That has apparently been accomplished, and Musk will reportedly be there for the initial 30 Model Y Performance customer vehicle deliveries. 

    The German factory will play a key role in Tesla’s overall growth plans. Along with China, Europe is one of the largest global electric vehicle markets. With the Berlin factory in operation, the company’s Shanghai factory can focus more on sales within China. Currently, the Shanghai plant exports much of its production to Europe and elsewhere. 

    Tesla reported $5.5 billion in net income in 2021 and expects to be able to sustain annual production growth of more than 50% for several years. The new factory in Germany, as well as one in Austin, Texas, will help drive that growth. 

    Tesla shares are down about 12% year to date but have jumped more than 20% in the last week leading up to the openings of the two new factories. That upward move has continued today as Tesla followers highlight the events near Berlin. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Why Tesla shares are up ahead of ‘Delivery day’ appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Tesla right now?

    Before you consider Tesla, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Tesla wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Howard Smith has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Tesla and Twitter. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/wb4Xn7p

  • The Core Lithium (ASX:CXO) share price just keeps climbing. What’s the deal?

    The Core Lithium Ltd (ASX: CXO) share price is on a roll lately, surging 57% over the past month alone.

    The company’s shares surged nearly 10% on Monday to close at $1.235.

    So what is the deal with Core Lithium shares? Let’s have a look…

    What’s happening at Core Lithium?

    Core Lithium shares have surged 109% year to date and 201% in the past six months.

    One major announcement that had a huge impact on the company’s shares early this month was the signing of a deal with electric vehicle world leader Tesla Inc (NASDAQ: TSLA).

    Tesla and Core Lithium have entered a binding term sheet for the supply of 110,000 tonnes of spodumene concentrate during the next four years, as my Foolish colleague Mitch reported.

    Core Lithium will source this mineral from the Finniss Lithium Project, near Darwin Port in northern Australia. The Core Lithium share price soared 15% on the day of the announcement.

    Also in early March, Core Lithium advised the company had received results from nine diamond drill holes at the Carlton deposit of the Finniss Lithium Project.

    Eight of these drill holes intersected with spodumene bearing pegmatite mineralisation. The company plans to provide a further update on this project in the second quarter of 2022.

    Additionally, lithium shares including Core Lithium soared on Monday amid “bullish sentiment in the sector”, my colleague James reported yesterday.

    The lithium carbonate price has surged nearly 266% in a month, according to data from trading economics.

    Core Lithium is one of the top-performing lithium stocks on the ASX in 2022. The Core Lithium share price also hit record highs in 2021, exploding 300%.

    Core Lithium share price snapshot

    The Core Lithium share price has rocketed by 18% in the past week and a mammoth 449% in the past year.

    In comparison, the S&P/ASX 200 Index (ASX: XJO) has climbed roughly 8% in the last year.

    The company has a market capitalisation of about $2.1 billion based on the current share price.

    The post The Core Lithium (ASX:CXO) share price just keeps climbing. What’s the deal? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Core Lithium right now?

    Before you consider Core Lithium , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Core Lithium wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/mucOzrR

  • If you’d sank $10,000 into AMP (ASX:AMP) shares 10 years ago, this is what you’d be left with today

    A disappointed female investor sits in front of her laptop and puts her hand to her forehead and closes her eyes in disappointment over share price fallsA disappointed female investor sits in front of her laptop and puts her hand to her forehead and closes her eyes in disappointment over share price falls

    The AMP Ltd (ASX: AMP) share price has travelled lower over the past decade, while the S&P/ASX 200 Index (ASX: XJO) has surged.

    Nonetheless, we wind the clock back and see how much an investor would have made if they had invested $10,000 in AMP shares a decade ago.

    How much would your initial investment be worth now?

    If you spent $10,000 on AMP shares exactly 10 years ago, you would have picked them up for $4.26 each. The purchase would deliver approximately 2,347 shares without reinvesting the dividends.

    Looking at Monday’s closing price, the AMP share price finished at $94.5 cents. This means those 2,347 shares would be worth a measly $2,217.91.

    In percentage terms, the initial investment implies a loss of around 77.8% or a yearly average negative return of 13.98%. Comparing that to the ASX 200, the benchmark index has given back 5.52% over a 10-year period.

    And the dividends?

    Over the course of the last decade, AMP has made a total of 16 dividend payments from 2012 to 2020. Its most recent dividend distributions were halted due to the pandemic severely affecting its operations and bottom line.

    Adding those 16 dividends payments gives us a total amount of $1.97 per share. Calculating the number of shares owned against the total dividend payment gives us a figure of $4,623.59.

    When putting both the initial investment gains and dividend distribution, an investor would have $6,841.50.

    This means that not only your investment would have lost a considerable amount, but also it would be worth less today. This is because of inflationary movements in which the value of $1 is worth less than the price tomorrow.

    Another factor to take in would be the time and opportunity cost in which an investor could have grown their money elsewhere. In particular, the ASX 200 over a 10-year period with the same initial investment would have netted $17,108.57.

    AMP share price snapshot

    Over the past 12 months, the AMP share price has moved 32% lower and is down 6% year to date.

    AMP has a price-to-earnings (P/E) ratio of 18.17 and commands a market capitalisation of roughly $3.09 billion.

    The post If you’d sank $10,000 into AMP (ASX:AMP) shares 10 years ago, this is what you’d be left with today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in AMP right now?

    Before you consider AMP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and AMP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/q0sREjK

  • Bubs (ASX:BUB) share price on watch amid A2 product launch

    A woman with bright yellow hair wearing a brightly patterned blouse reacts to big news that she's reading on her phone.

    A woman with bright yellow hair wearing a brightly patterned blouse reacts to big news that she's reading on her phone.

    The Bubs Australia Ltd (ASX: BUB) share price will be one to watch on Tuesday.

    This follows the release of an announcement out of the infant formula company this morning.

    Why is the Bubs share price on watch?

    All eyes will be on the Bubs share price today after the company announced that it will be taking on A2 Milk Company Ltd (ASX: A2M) with its own A2 protein-based infant formula product.

    According to the release, the company is launching Bubs Supreme infant formula and toddler milk with natural A2 beta-casein protein.

    This allows the company to access the global A2 beta-casein protein milk market, valued at US$1.23 billion and estimated to reach US$2.6 billion in global market size by 2026. Furthermore, it highlights that it will leverage on the category growth and consumer trend towards premiumisation in China, where the A2 beta-casein protein segment is growing strongly.

    Bubs Founder and CEO, Kristy Carr, said: “Innovation is inherent in Bubs’ culture and a key driver behind our high growth strategy. With the launch of Bubs Supreme A2 beta-casein protein range in our most profitable business segment, we are now able to cater to a more significant share of the addressable infant formula and toddler milk market, thereby strengthening our position in the total category to build widespread recognition of Bubs as a brand synonymous with clean, high quality infant nutrition.”

    The release notes that the Bubs Supreme formula range will be on shelf in 500 Coles Group Ltd (ASX: COL) supermarkets from May. This expands the shelf presence of existing product lines, including Bubs easy-digest goat milk formula and Bubs Organic grass-fed cow’s milk formula already sold in Coles stores nationally.

    Management believes the addition of Bubs Supreme A2 beta-casein protein milk formula will broaden its brand appeal to a new domestic market segment.

    Sales order

    Also potentially boosting the Bubs share price today is news that its recently announced deal with Willis Trading has led to an opening purchase order valued at $32.9 million.

    These products will be delivered in Q4 FY 2022 and Q1 FY 2023 and distributed to the daigou channel.

    The post Bubs (ASX:BUB) share price on watch amid A2 product launch appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Bubs right now?

    Before you consider Bubs, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Bubs wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended COLESGROUP DEF SET. The Motley Fool Australia has recommended A2 Milk and BUBS AUST FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/21r8DCw

  • 2 former ASX darlings are ready to buy again now: experts

    A tattoed woman holds two fingers up in a peace sign.A tattoed woman holds two fingers up in a peace sign.

    Stocks have taken a battering this year, and this has meant many ASX shares that made investors wealthy in the past have recently dragged portfolios down.

    But maybe it’s time to buy some of those stocks again, to take advantage of any return to past glory.

    A couple of experts this week had some ideas about which ASX shares might be ready for a revival.

    ‘Highly profitable’ and low PE ratio

    Software maker Hansen Technologies Limited (ASX: HSN) handsomely rewarded long-term investors in the past.

    The ASX stock returned more than 550% in the 10 years ending November 2021.

    But unfortunately it has dropped 18% in just four months since. 

    Spotee Connect analyst Chris Batchelor reckons this presents a buying opportunity for those willing to hang on for the long haul.

    “Target is to grow forecast revenue from about $300 million in fiscal year 2022 to $500 million by fiscal year 2025, partially via strategic acquisitions,” he told The Bull.

    “Hansen is highly profitable and was recently trading on an attractive price/earnings multiple of 17 times.”

    The company, which makes billing and customer data software, is not monitored by many analysts. But those that do seem to like it.

    According to CMC Markets, two of three analysts rate Hansen shares as a “strong buy”, while the third one labels it as “hold”.

    The ASX share closed Monday at $5.31 each, up 1.14% on the day.

    ‘Attractive investment’

    Fruit and vegetable producer Costa Group Holdings Ltd (ASX: CGC) has taken investors on a couple of wild rides.

    Its share price quadrupled from 2015 to 2018, then doubled from end of 2019 to April last year.

    Unfortunately, unfavourable guidance to the annual general meeting saw Costa shares fall 22% in one day last May.

    Yikes.

    But Bell Potter Securities investment advisor Chris Watt reckons it’s time to take another look at the produce wholesaler.

    “Costa Group is the largest fresh produce company in Australia, with an estimated market share above 15%,” he said.

    “It supplies fresh fruit and vegetables to the major Australian supermarkets.”

    The current depressed stock price presents a major buying opportunity, Watt’s team has calculated.

    “We view Costa Group as an attractive investment, given international berry expansion to China is running according to Costa’s original five-year plan, and appears set for significant growth,” he said.

    “Further, Costa is well positioned to capitalise on high growth in emerging product categories, such as blackberries.”

    Other analysts are fairly positive on the ASX stock, with nine of 13 analysts surveyed on CMC Markets rating it as either a “strong” or “moderate” buy.

    Costa shares finished Monday at $2.99 apiece, a gain of 1.36% yesterday.

    The post 2 former ASX darlings are ready to buy again now: experts appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Hansen Technologies. The Motley Fool Australia has recommended COSTA GRP FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2BXRiSy

  • Broker tips TechnologyOne (ASX:TNE) share price to rise 26% amid SaaS growth

    The TechnologyOne Ltd (ASX: TNE) share price was out of form on Monday and dropped into the red.

    This means the enterprise software company’s shares are now down 15% since the start of the year.

    Is the TechnologyOne share price weakness a buying opportunity?

    One leading broker that sees the recent weakness in the TechnologyOne share price as a buying opportunity is Bell Potter.

    According to a note this morning, the broker has retained its buy rating but trimmed its price target on the company’s shares to $14.00.

    Based on the current TechnologyOne share price of $11.11, this implies potential upside of 26% for investors over the next 12 months.

    What did the broker say?

    Bell Potter notes that it has been several months since TechnologyOne advised that it would stop providing new functionality to its on-premise software before ultimately ceasing support in October 2024. This is in an effort to switch customers over to its software-as-a-service (SaaS) solution.

    The broker believes the switch could be going well, which bodes well for Technology One’s growth.

    It commented: “Several months on from this announcement we expect the impact is an acceleration of customer flips from on-premise to SaaS especially given government and local government departments cannot be on unsupported software so need to move.”

    “We expect this acceleration will be evident in the upcoming 1HFY22 result to be released in late May and will be apparent from a large increase in SaaS ARR. In our view SaaS ARR is now the key metric for Technology One given the transition of the company to SaaS so we would regard a large percentage increase as positive,” it added.

    And while the broker is not making any changes to its estimates at this stage and continues to “forecast strong SaaS ARR growth of 30% in FY22,” it believes there “may be upside risk to this forecast if the SaaS flips are greater than we have allowed for.”

    The post Broker tips TechnologyOne (ASX:TNE) share price to rise 26% amid SaaS growth appeared first on The Motley Fool Australia.

    Should you invest $1,000 in TechnologyOne right now?

    Before you consider TechnologyOne, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and TechnologyOne wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/cl3xIUR

  • Why should we choose between Super and a house?

    A man looking happy whilst holding up two little wooden housesA man looking happy whilst holding up two little wooden houses

    Some Monday mornings, I sit down to write, feeling refreshed, energised and philosophical.

    Other Monday mornings, I sit down with proverbial steam coming out of my ears.

    This morning?

    Both.

    I wrote on both Twitter and Facebook about the (reasonable) lionisation of the ‘artist’ and the (unfortunate) underappreciation of the ‘craftsperson’.

    (Spoiler alert: I love artists, but they are few and far between. We’d be better off celebrating and committing ourselves to craftspersonship.)

    That was the ‘energised and philosophical’ bit.

    The steam coming out of the ears?

    Another misguided effort, by a government inquiry, to make housing ‘more affordable’ by letting people use Superannuation to buy a house.

    Now, the easy (and tempting) option at this point is to engage in a long monologue of well-directed invective, aimed at those usual suspects.

    And that would make me feel a lot better.

    But given this is about you, our members and readers, and not me, I’ll refrain, and set out my case a little more carefully.

    Now, I’m going to assume that the vast bulk of us can see the problem with ever-escalating house prices.

    A 24% increase, in 2021, is both unaffordable and unsustainable for those hoping to be able to afford a property.

    Yes, I’m on the record as saying ‘sticker shock’ is less important than ‘affordability’, measured by repayments, so I’m staying away from the easy tabloid (and wrong, at least for the most part) assessments of ‘house prices up = bad’.

    But – and there’s a but – there are a couple of important reasons to believe that housing is off-kilter, right now.

    If you believe, as I do, that house price gains are a logical result of the ‘financialisation’ of housing, then you’ll agree with me that lower interest rates will lead to higher prices, at a given level of repayments.

    If the maths isn’t instinctive for you, try this: If you can afford to pay, say, $750 per week in repayments, a quick look at a mortgage calculator will show you that you can afford to borrow much more at, say, a 3% interest rate, compared to a 5% interest rate.

    Which, funnily enough, is precisely what’s happened over the past decade: falling interest rates have fuelled higher house prices.

    Now, that’s not a surprise. And in the investing world, not even a bad thing. It’s just the way the maths works. Share prices will be higher – all else being equal – when interest rates are lower, and lower (again, using the same assumptions) when interest rates are higher.

    If – and I think we can say ‘when’, using the past tense – housing became financialised, it moved from being priced predominantly as ‘shelter’ to predominantly as a financial asset, we should expect more extreme moves, correlated to interest rates.

    And – and this is the kicker – in both directions.

    Is it reasonable – logical, even – for a financial asset to increase meaningfully in price as rates fall? Yep, sure is.

    And is it reasonable – again, logical – to expect house prices to run the very real risk of falling, maybe even meaningfully, as rates rise?

    Again – and unfortunately for those buying today – I think the answer is ‘yes’.

    Not guaranteed, of course, because people aren’t robots. But possible. I think even probable.

    Now, is that the market we want young people to be buying into, today?

    I don’t think so, which is part of the problem.

    Second, and more immediately, the other problem with fast-rising house prices is the equally fast-rising deposit requirements.

    If you had to save, say, $150,000 for a deposit at the beginning of 2021, that number had ballooned to $186,000 by the end of the year.

    And stamp duty increased at around the same percentage rate.

    Which young person, without help from the Bank of Mum & Dad, can save that fast?

    Hint: it rounds to zero.

    So, I’m going to assume you’re with me on the contention that house prices – as a function of a healthy society, not just as financial assets – are a problem.

    So is it a good thing that governments are looking at that very problem?

    You bet.

    And, given the growing lump sums in Super, logical, even a good thing, that people should be allowed to use that money for a deposit?

    No. Bloody. Way.

    See, I want you to imagine an aircraft, in significant difficulty. It’s down to one engine, and the plane is too heavy to keep flying on just that single engine.

    The aircrew realise they have to jettison some weight.

    They look around.

    There’s a cargo hold full of freight.

    The seats are heavy, and 75% of them are unoccupied.

    It’s carrying way more fuel than is – even conservatively – needed to land.

    They radio the ground for help, and the government announce a swift enquiry, which reports back in a matter of minutes:

    “We think you should detach and jettison the landing gear” is their recommendation.

    There is stunned silence. The committee’s recommendation goes on:

    “Clearly the plane is too heavy. If you toss the the landing gear out, you can keep flying”

    “Isn’t that better than crashing?”

    Of course, given that binary option – keep the wheels attached and crash, or jettison them and keep flying – no sane person chooses to crash.

    But then the junior third officer pipes up: “Umm, Captain… don’t we have more than just those two options?”

    “Couldn’t we, maybe, consider other choices? We have a lot of potential alternatives, and some smart people. I’m sure the choice isn’t just ‘crash now, or abandon the landing gear!”

    Let’s come back from analogy-land.

    I tweeted about the housing versus Super issue on the weekend.

    A couple of my correspondents suggested that retiring with a house and less Super is better than having more Super and without a house to call one’s own.

    And hey, questions of the relative returns of each notwithstanding (and they should be factored in!), I understand that point.

    But…

    Surely, I suggested, raiding Super to make housing actually affordable is a false binary choice.

    Maybe… just maybe… there are some other options we could put on the table?

    And in the world of policy-making, where there are literally dozens of different things a government could do, surely raiding Super isn’t the best way to fix the problem of housing affordability?

    Because not only is a further cash injection into the housing market actually likely to push prices up (which should be enough to kill the idea, anyway), but making people choose between a house and a comfortable retirement has to be a pretty good sign we’ve let policy settings get way out of whack.

    See, I think we should aspire to be a country where both are possible for the vast majority of people.

    We have one of the highest levels of both average wealth and average income in the entire world, and we can’t find a way to solve both problems simultaneously?

    And our government would give up on that effort without even trying, just inviting people to choose between expensive housing and comfortable retirement?

    Seriously?

    And in case you’re wondering, the housing affordability issue isn’t party-political.

    I see no good options being put forward to fix it from either side.

    But, equally clearly, it’s also fair to say that some on the Treasury benches are actively pushing the ‘raid Super to buy a house’ line, and I’m not sure I’ve heard anyone on the other side of the house doing the same.

    (I say that not to make a political point, per se, but I’m also not going to pretend the ‘raid Super’ idea is a bipartisan one. You don’t need to be biased to simply report the facts. But equally, if I’ve missed it, let me know.)

    So where does that leave us?

    Well, we can swallow the line that ‘Housing is better than Super’, as if we have only a binary choice.

    We can, to return to our analogy, believe that either keeping the landing gear and crashing, or jettisoning the landing gear and not crashing — until we try to land, that is — are our only two options.

    Or, we can say, loudly and clearly, that we think both should be fundamentally accessible and achievable for the vast bulk of us, in a prosperous and caring country.

    Put me down for the latter.

    We’ve gotta do a better job of helping our young people afford housing, should they want it.

    And we’ve gotta say, full-throatedly, Hands Off Super!

    With all of the policy options available to our parliament, I don’t think it’s too much to ask.

    Fool on!

    The post Why should we choose between Super and a house? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Randi Zuckerberg, a former director of market development and spokeswoman for Facebook and sister to Meta Platforms CEO Mark Zuckerberg, is a member of The Motley Fool’s board of directors. Motley Fool contributor Scott Phillips has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Meta Platforms, Inc. and Twitter. The Motley Fool Australia has recommended Meta Platforms, Inc. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/gzrldmK
  • How close is Fortescue (ASX:FMG) Future Industries to making green hydrogen?

    a man dressed in a green superhero lycra outfit stands in a crouched pose with arms outstretched as if ready to spring into action with a blue sky and oil barrels lying in the background.

    a man dressed in a green superhero lycra outfit stands in a crouched pose with arms outstretched as if ready to spring into action with a blue sky and oil barrels lying in the background.

    Fortescue Future Industries (FFI), the green division of Fortescue Metals Group Limited (ASX: FMG), is working on producing green hydrogen. But how close is that to becoming reality?

    First of all, let’s look at what ‘green hydrogen’ actually is. Some forms of hydrogen are produced with fossil fuels used in the process.

    However, the idea behind green hydrogen is that only renewable energy is used to split water molecules, creating hydrogen.

    Fortescue Future Industries is aiming to decarbonise its trucks, drill rigs, planes, and industrial processes with green hydrogen. The hydrogen can also be turned into green ammonia which can be used as a fuel for shipping and rail, as well as creating green fertiliser for agriculture.

    How much green hydrogen does Fortescue Future Industries want to make?

    FFI wants to become a global leader in green energy and technology, including leading the effort to decarbonise sectors that are difficult to decarbonise.

    Fortescue Future Industries is investing to create a global portfolio of green energy projects to supply 15 million tonnes per year of renewable green hydrogen by 2030. From there, the plan is to accelerate production to 50 million tonnes per year over the following decade.

    Green hydrogen production plans

    In December 2021, FFI announced that it had made hydrogen using an electrolyser designed and built by the Fortescue Future Industries team. This process produced industrial-grade hydrogen for the first time.

    FFI is now looking at multiple new electrolyser technologies that will form part of the electrolyser patent family. The outcomes of these projects will inform its electrolyser technology selection going forward.

    At present, FFI is in the process of installing solar panels at its Dawson Road facility in Western Australia. This will see its electrolyser being able to produce green hydrogen in 2022.

    However, to reach the company’s longer-term goals, there are plans for a number of projects around the world.

    In November 2021, FFI received planning approval from the Queensland government for the global green energy manufacturing (GEM) centre in Gladstone, Queensland. The first stage of development is to build an electrolyser manufacturing facility with an initial capacity of two gigawatts per annum. This entails an investment of up to US$83 million with construction starting last month.

    The GEM has several growth stages already planned into its factory footprint, including green manufacturing technology such as cables, batteries, wind turbines, and solar panels.

    It also has a number of agreements with various countries about the potential for creating green hydrogen production facilities, including Indonesia, Canada, PNG, Jordan, India, and Brazil.

    Fortescue also recently announced an agreement with Airbus to create a plane that can run on green hydrogen.

    Who will its customers be?

    While Fortescue Future Industries is building its portfolio of production facilities, it is also building a client base for its future production.

    Covestro, a world-leading, Germany-based supplier of high-tech polymer materials, is planning on formalising an agreement where FFI will supply it with the equivalent of up to 100,000 tonnes of green hydrogen a year.

    In October 2021, Fortescue Future Industries signed an agreement with JCB and Ryze Hydrogen to become the United Kingdom’s largest supplier of green hydrogen. JCB and Ryze will purchase 10% of FFI’s global green hydrogen production.

    Under the partnership, FFI will lead the green hydrogen production and logistics to the UK market, and JCB and Ryze will manage green hydrogen distribution and development of customer demand in the UK, according to FFI.

    Green hydrogen to become cheaper?

    The cost to produce green hydrogen is seen as one of its drawbacks to it becoming more widely used.

    Various media, including The Guardian, recently reported on how Australian researchers from technology company Hysata claim to have increased the efficiency of electrolysers. The company says its technology could reduce the cost of producing hydrogen to as low as $2 per kilo.

    Hysata CEO Paul Barrett said that the efficiency levels achieved were the best in the world:

    We’ve gone from 75% [efficiency] to 95% – it’s really a giant leap for the electrolysis industry.

    For hydrogen producers, this will significantly reduce both the capital and operational costs to produce green hydrogen.

    The post How close is Fortescue (ASX:FMG) Future Industries to making green hydrogen? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Fortescue right now?

    Before you consider Fortescue, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Fortescue wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison owns Fortescue Metals Group Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Y58iDeF

  • Potential opportunities: 2 compelling ASX shares

    A surprised and curious male investor drinks black coffee while reading the latest news on rising ASX shares in the newspaper

    A surprised and curious male investor drinks black coffee while reading the latest news on rising ASX shares in the newspaper

    There are some ASX shares pointing to potential industry trends that may lead to compelling growth over the coming years.

    One of the below ASX shares provides exposure to the ever-growing need for protection against cybercrime.

    The other ASX share is benefiting from the desire for improved technology in the audio industry.

    Betashares Global Cybersecurity ETF (ASX: HACK)

    This is an exchange-traded fund (ETF) that gives investors access to the global cybersecurity sector.

    As Betashares says, “With cybercrime on the rise, the demand for cybersecurity services is expected to grow strongly for the foreseeable future.”

    Statista expects the global cybersecurity market to grow to $248.26 billion by 2023. That would be an 80% increase from 2017.

    There are 35 businesses in the portfolio. Each of them provides a particular set of services that helps businesses and individuals stay safer in the cyber world.

    The ETF’s largest holdings at the latest disclosure are: Cisco Systems, Palo Alto Networks, Crowdstrike, Accenture, Mandiant, Check Point Software Technologies, Leidos, Thales, Juniper Networks, and Cloudflare.

    The investment comes with an annual management cost of 0.67%.

    Of course, past performance is not a reliable indicator of future performance. In the three years to 28 February 2022, the HACK ETF produced an average return per annum of 21.2%.

    Audinate Group Ltd (ASX: AD8)

    Audinate is an ASX share that provides the Dante offering to the audio sector.

    Dante is an audio over internet protocol (IP) networking solution, which Audinate claims as the worldwide leader in its field. The company says it is used “extensively” in the professional live sound, commercial installation, broadcast, public address, and record industries.

    It is seeing a recovery from the worst of the effects of COVID-19 on events.

    The ASX share reported that in the first-half of FY22, revenue jumped 32% to $20.2 million and the earnings before interest, tax, depreciation and amortisation (EBITDA) rose 11% to $2 million. Despite COVID-19 impacts, it made a positive operating cash flow of $0.5 million in the first half of FY22.

    It’s seeing record levels of demand, but supply has been hurt by the current component shortages.

    Audinate says the AV sector is just starting digital networking conversion. The company is also entering the fragmented video market. Management noted the company has the balance sheet for strategic acquisitions. It recently completed the acquisition of the Silex Insight video business, which produces video networking products for manufacturers of AV equipment.

    The company estimates that its total addressable market exceeds A$1 billion.

    Some areas of focus include improving Dante adoption by non-English speakers and implementing business scalability initiatives. It also wants to launch new Dante video software and cloud services products.

    The post Potential opportunities: 2 compelling ASX shares appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended AUDINATEGL FPO and BETA CYBER ETF UNITS. The Motley Fool Australia owns and has recommended AUDINATEGL FPO and BETA CYBER ETF UNITS. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/jfwVCgn