Category: Stock Market

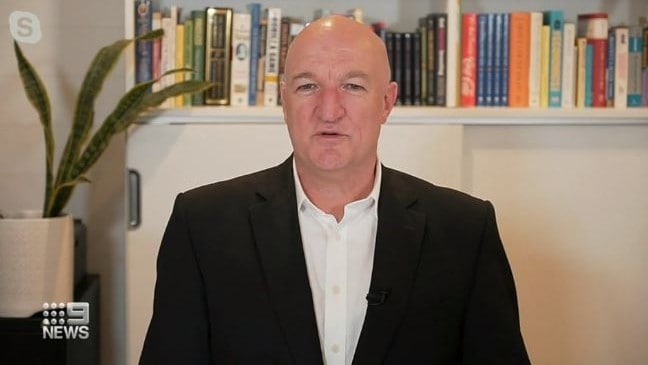
  • Suncorp surprises, and 4 rate rises on the cards. Scott Phillips on Nine’s Late News

    Scott Phillips on Nine Late News 9February 2022Scott Phillips on Nine Late News 9February 2022Scott Phillips on Nine Late News 9February 2022

    Motley Fool Australia Chief Investment Officer Scott Phillips joined Nine’s Late News on Tuesday night to discuss the market’s pleasant surprise from Suncorp Group Ltd (ASX: SUN) earnings, the ongoing inflation battle for costs that will take time to fall, and an ex-RBA board member’s expectation for 4 rate rises in 2022.

    The post Suncorp surprises, and 4 rate rises on the cards. Scott Phillips on Nine’s Late News appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Suncorp right now?

    Before you consider Suncorp, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Suncorp wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Scott Phillips has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/9XCUgbj

  • Could climbing costs crash the ASX lithium share party?

    Galan Lithium share price falling asx share price represented by a sad and flat batteryGalan Lithium share price falling asx share price represented by a sad and flat batteryGalan Lithium share price falling asx share price represented by a sad and flat battery

    A shot has been fired across the bow of ASX lithium shares today following a concerning admission from Mineral Resources Limited (ASX: MIN).

    Troubling high costs for lithium exportation were revealed in the mining company’s half-year results this morning. Consequently, the lithium producer took a wrecking ball to its profits during the period. The outcome was a 96% reduction in net profits.

    What could this mean for ASX lithium shares more broadly?

    Inflation takes its pound of flesh from ASX lithium shares

    Investors have been quick to pile into the growth opportunity presented by ASX lithium shares. This has been driven by an underlying native of attractive supply and demand dynamics. Many estimates put supply ahead of demand over the coming years.

    This investment thesis has left lithium investors smitten during the last 18 months, as the projections have played out in real-time. In the last year alone, the price of spodumene concentrate has increased by nearly six-fold. Unsurprisingly, many ASX-listed lithium shares have moved multiples higher in response.

    However, today’s news from Mineral Resources reminds the market that there’s more to consider than the sale price of a commodity. The other piece of the financial puzzle takes shape in the form of costs.

    Ultimately, the difference between these two variables is what determines the success of a mining company. In a worrisome development, one of the biggest Aussie lithium producers has indicated a drastic change to its cost structure.

    According to its results, Minerals Resources experienced a 60% increase in lithium production costs year on year. The company’s spodumene mine, Mt Marion, recorded costs of $570 to $615 per tonne during the period. Additionally, increased shipping costs constituted 40% of the increase in costs.

    Evidently, the pressure of beefed expenses paired with a reduction in overall revenue has hit this ASX lithium share’s price today.

    No doubt investors will be watching with bated breath over the coming weeks as more lithium shares reveal whether inflationary pressures have been taking a bite out of mining profits.

    The post Could climbing costs crash the ASX lithium share party? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Mineral Resources right now?

    Before you consider Mineral Resources, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Mineral Resources wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Mitchell Lawler has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Lmp6Scz

  • What to expect when Treasury Wine (ASX:TWE) uncorks its results next week

    rising ASX share price represented by cork popping out of wine bottle

    rising ASX share price represented by cork popping out of wine bottlerising ASX share price represented by cork popping out of wine bottle

    Next week the Treasury Wine Estates Ltd (ASX: TWE) share price will come into focus when it releases its half year results.

    Ahead of the release of Wednesday 16 February, let’s take a look to see what the market is expecting from the wine giant.

    What should you expect from Treasury Wine’s half year results?

    At present, the market consensus estimate is for the Penfolds owner to report revenue of $1,251 million and EBITS of $259 million for the first half of FY 2022. This will be down 11.3% and 7.9%, respectively, over the prior corresponding period.

    According to a note out of Goldman Sachs, while it is still expecting a decline year on year, it believes the company will outperform the market’s expectations.

    On the top line, the broker is forecasting a 7.7% reduction in revenue to $1,301.9 million. This comprises a 2.8% decline in Penfolds revenue to $444.5 million, a 13.5% decline in Americas revenue to $440.5 million, and a 6% fall in Premium Brands revenue to $416.8 million.

    Goldman also expects Treasury Wine’s EBITS to come in ahead of consensus estimates at $265.3 million. This represents a 6% decline over the prior corresponding period and is largely being driven by weaker earnings from its Penfolds business, which it expects to offset strong earnings growth in the Americas segment.

    What else should you watch out for?

    Goldman has named three key items that it will be watching out for. These are Penfolds sales outside of Australia, the Americas business post commercial transition, and its inventory.

    In respect to Penfolds, it explained: “This is as a key indicator of longer-term progress, in our view. Management noted strong growth on this front during the FY21 results. The sustainability and acceleration of this progress will be key towards meeting longer-term expectations for the brand.”

    As for the Americas, it commented: “The sustainable growth in Americas in the focus portfolio, following the divestment of commercial brands and acquisition of FFV, will be another key focus area for us in the 1H22 results.”

    “We expect inventory to remain elevated at >70% of sales till end of FY23. While intake has been managed to take into account the shift in sales mix in Asia following the closure of the Chinese market, we expect intake to be an indicator of the longer-term outlook for sales growth,” Goldman concludes.

    Is the Treasury Wine share price in the buy zone?

    Despite expecting the company to outperform expectations during the first half, Goldman only has a neutral rating on the Treasury Wine share price.

    Though, it is worth noting that its price target of $11.80 implies decent upside from current levels.

    The post What to expect when Treasury Wine (ASX:TWE) uncorks its results next week appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Treasury Wine right now?

    Before you consider Treasury Wine, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Treasury Wine wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Treasury Wine Estates Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/TXLl23U

  • Is the ASX value shares party just getting started?

    A group of people at a party look upwards to the camera as they celebrate the rise of ASX value sharesA group of people at a party look upwards to the camera as they celebrate the rise of ASX value sharesA group of people at a party look upwards to the camera as they celebrate the rise of ASX value shares

    After underperforming growth shares for the better part of 10 years, value shares are shining bright in the new year.

    Since the opening bell on 4 January, the S&P/ASX 200 Growth Index is down 7%. Meanwhile, the S&P/ASX 200 Value Index has gone the other way, up 6%.

    All together the S&P/ASX 200 Index (ASX: XJO) is down 5% in 2022.

    Why are value shares outperforming growth shares?

    Much of the shift in investor sentiment has come following the realisation that inflation is running higher than most economists had forecast last year. That’s leading to inevitable interest rate rises, which hits growth shares harder, as they’re more dependent on future earnings.

    The prospect of rising interest rates helped propel the steep losses among tech shares last month. And in turn, it’s seen ASX value shares benefit.

    In The Australian Financial Review, Perennial Value portfolio manager Stephen Bruce said:

    Now that better growth and higher inflation seem to have become entrenched, the rate tightening cycle has finally started. This has meant the de-rating of the expensive parts of the market. How far this continues will be a function of growth, inflation and rates.

    Is the ASX value shares party just getting started?

    While ASX value shares have well-outpaced growth shares in 2022, what can investors expect going forward?

    Dougal Maple-Brown, head of Australian equities at Maple-Brown Abbott, believes there’s a long way to go yet:

    We’ve had a pretty good run. Value has underperformed for almost a decade, but the one-year numbers are now looking really good. We think there’s still something left in the tank because while the extremes have been hit, there are some stocks out there with a lot of excess still. The valuation dispersion is still very wide even though it’s come back a fair bit, so we think there’s a long way to go.

    Bruce also believes the brighter run for ASX value shares is a long way from over:

    Given how historically low rates are and how extreme valuation dispersion in market has become, there could potentially be a long way for this to run yet.

    Flows are definitely starting to improve, but there hasn’t been any massive shift back towards value yet. I think investors, both retail and institutional, have all become very underweight value over the last number of years. So potentially, there could be a significant reallocation if this rotation continues.

    By the numbers

    To give you some idea of how leading ASX growth shares have stacked up against value shares, Pointsbet Holdings Ltd (ASX: PBH) – a growth share favourite that gained 1,137% from 20 March 2020 through to 19 February 2022 – is down 28% in the new year.

    Fellow growth share, Appen Ltd (ASX: APX) has struggled as well, down 22% so far in 2022.

    Then there’s leading ASX value share, QBE Insurance Group Ltd (ASX: QBE), which has seen its shares gain 7% year-to-date.

    The post Is the ASX value shares party just getting started? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in QBE right now?

    Before you consider QBE, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and QBE wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Appen Ltd and Pointsbet Holdings Ltd. The Motley Fool Australia owns and has recommended Appen Ltd. The Motley Fool Australia has recommended Pointsbet Holdings Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/zFaqobM
  • Here are the 3 most heavily traded ASX 200 shares this Wednesday

    a young girl cries at an airport with planes lining up in the backbround.a young girl cries at an airport with planes lining up in the backbround.

    a young girl cries at an airport with planes lining up in the backbround.The S&P/ASX 200 Index (ASX: XJO) has doubled down on yesterday’s gains so far this Wednesday. At the time of writing, the ASX 200 has risen a pleasing 0.8% and is currently sitting at 7,244 points.

    But let’s dig a little deeper and have a look at the ASX 200 shares that are currently sitting at the top of the share market’s trading volume charts, according to investing.com.

    The 3 most traded ASX 200 shares by volume so far on Wednesday

    Telstra Corporation Ltd (ASX: TLS)

    Telstra is our fisrt share up today. So far, a hefty 15.1 million shares of this ASX 200 telco have found a new home. That’s despite the Telstra share price doing a whole lot of not much so far this Wednesday.

    Telstra is currently flat at $4.06 a share after going as high as $4.10 a share and as low as $4.03 earlier this morning. There have been no other pieces of news out of Telstra, so we have to assume it is this volatility, as well as Telstra’s relatively low share price compared to its market capitalisation, that is behind this volume.

    AMP Ltd (ASX: AMP)

    ASX 200 financial services company AMP is our next share to check out today. This wealth manager has seen an impressive 19 million of its shares bought and sold on the markets thus far this Wednesday.

    There’s been no major news or announcements out of AMP thus far. As such, we can probably put this high volume down to the movements of the AMP share price itself. The company is currently up a pleasing 3.89% to around $1 a share at the time of writing. It’s this decisive move that is almost certainly behind this elevated volume we see.

    Sydney Airport (ASX: SYD)

    For the last time, Sydney Airport is our most traded ASX 200 share of the day, with a whopping 40.35 million shares having traded owners on the markets. I say for the last time because today is the final day that Sydney Airport will call the ASX home.

    The company is scheduled to delist from the ASX boards this afternoon after the successful takeover bid from the Sydney Aviation Alliance was accepted by both regulators and shareholders over the past month or two. So today’s volume is probably a consequence of this, er, imminent departure.

    The post Here are the 3 most heavily traded ASX 200 shares this Wednesday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Telstra right now?

    Before you consider Telstra, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Telstra wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen owns Telstra Corporation Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Telstra Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/KGOsxm3

  • We bought. EPA:STM, EBR:MELE

    ST Microelectronics
    Code EPA:STM bought for 42.1 EUROS
    ST Microelectronics is a French chip maker. It is backed by several european countries (including France) to ensure Europe’s sovereignty in the chip supply. Chips are used everywhere they are at the center of a lot of industries: electric cars, planes, sub marines, IOT, etc… STMicroelectronics is pretty robust. Covid has introduced supply chains disruption all around the world and STM managed to deliver steadily those last 2 years. It is positioned to see good days ahead.

    MELEXIS
    Code EBR:MELE – bought for 90.64 EUROS
    Melexis is also a chip maker. They are positioned to do wonders in the electric cars space. For every car produced worldwide, they had on average 13 chips onboard. The number has increased to 18 chips at the end of last year with revenue progressing 27% year on year. Those are great signs that they are on top of the game.

  • Own AMP (ASX:AMP) shares? This could be the next blow for the company’s demerger plans

    A group of disappointed board members.A group of disappointed board members.A group of disappointed board members.

    Watchers of the AMP Ltd (ASX: AMP) share price will likely be gearing up for the release of the company’s full year results tomorrow.

    However, on the eve of their release, reports have emerged claiming investors in its $7 billion office fund – the crowning jewel of soon-to-be-demerged AMP Capital – are considering withdrawing from the fund.

    At the time of writing, the AMP share price is $1, 3.83% higher than its previous close.

    For context, the S&P/ASX 200 Index (ASX: XJO) is currently up 0.3%. Meanwhile, the All Ordinaries Index (ASX: XAO) has gained 0.2%.

    Let’s take a closer look at the drama that could be unfolding within AMP’s newly re-secured AMP Capital Wholesale Office Fund (AWOF).

    Is the ‘crown jewel’ of AMP’s demerger still in danger?

    According to the Australian Financial Review (AFR), a letter written by AWOF investors cites concerns that the fund’s managers could have conflicted interests.

    A recent review resulted in the fund’s trustee board finding that AMP is the best entity to manage AWOF.

    However, it seems the finding hasn’t eased the concerns of institutional investors – the same investors reportedly responsible for the review.   

    The AFR has previously reported that the fund’s trustee board is comprised of 3 AMP executives. They were advised by an independent advisory committee during the review process.

    But according to today’s reporting, the fund’s investors are irked by the trustee board’s makeup and concerned it will be incentivised by AMP’s successful demerger.

    The AMP share price gained 2.9% when it released its latest update on its demerger plans.

    If all goes to plan, they will see AMP Limited split from AMP Capital’s Private Markets business, referred to as ‘Private Markets Co’.

    The demerger is expected to go ahead during the current half.

    The AFR quoted AWOF’s investors’ letter:

    There is a concern that the trustee has prioritised the interest of its shareholders ahead of the interest of AWOF’s investors.

    We are concerned this leads to a very clear conflict with their ability to independently assess whether an AMP entity, or another manager, should retain the management mandate for AWOF and make a recommendation to investors.

    The retention of the management rights of AWOF has clear and direct benefit to Private Markets Co and therefore the directors personally via their participation in the incentive arrangements.

    AWOF’s investors’ concerns follow AMP Capital’s loss of the $5 billion AMP Capital Diversified Property Fund last year.

    AMP share price snapshot

    2022 has seen the AMP share price outperforming the market.

    It has gained 0.2% year to date while the ASX 200 has slipped 4.5%.

    However, AMP’s stock is still trading for 34.5% less than it was this time last year.

    The post Own AMP (ASX:AMP) shares? This could be the next blow for the company’s demerger plans appeared first on The Motley Fool Australia.

    Should you invest $1,000 in AMP right now?

    Before you consider AMP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and AMP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/zBRn1vh

  • Broker says buy Webjet (ASX:WEB) instead of Flight Centre (FLT) shares

    plane flying across share markey graph, asx 200 travel shares, qantas share priceplane flying across share markey graph, asx 200 travel shares, qantas share price

    plane flying across share markey graph, asx 200 travel shares, qantas share priceGiven the improving outlook for the travel sector, investors may be wanting to gain exposure to this side of the market.

    And while there are a number of options to choose from, two of the most popular ASX travel shares are Flight Centre Travel Group Ltd (ASX: FLT) and Webjet Limited (ASX: WEB). But which one should you buy?

    Should you buy Flight Centre of Webjet shares?

    According to a note out of Goldman Sachs this morning, its analysts believe investors should skip Flight Centre and buy Webjet shares for travel sector exposure.

    The note reveals that the broker has retained its buy rating and $6.90 price target on Webjet’s shares. Based on the current Webjet share price of $6.06, this implies potential upside of 14% for investors over the next 12 months.

    Whereas Goldman has put a neutral rating and $20.40 price target on Flight Centre’s shares, which is broadly in line with where its shares are trading at present.

    What did the broker say?

    Goldman notes that the Omicron outbreak appears to be past its peak in most key markets. This has led to travel activity continuing to progress positively. In light of this, it is sticking with its original view that Omicron will only be a temporary speed bump in the sector’s recovery.

    Goldman said: “CY22 began slowly due to Omicron, but we note strong progress in flight search data into early February. TSA passenger traffic numbers have largely stabilized as a percentage of the same metrics as in 2019. We reiterate our expectations that Omicron causes a temporary drop in travel interest but returns quickly.”

    In respect to Webjet, Goldman Sachs believes it will be a stronger player post-pandemic.

    The broker said: “We are Buy rated on WEB, which we expect to come out stronger on the other side of the pandemic with growth potential both in the B2B and B2C spaces. WEB also maintains a strong balance sheet with c. 24 months of runway (from September 2021) at zero activity levels.”

    And while the broker has a positive view of Flight Centre post-pandemic and expects a 100% increase in revenue for the first half, it feels its shares are fully valued at the current level and thus holds firm with its neutral rating.

    Time will tell if the broker makes the right call.

    The post Broker says buy Webjet (ASX:WEB) instead of Flight Centre (FLT) shares appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Webjet right now?

    Before you consider Webjet, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Webjet wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Flight Centre Travel Group Limited and Webjet Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/WIhr16n

  • Sparc Technologies (ASX:SPN) share price rallies 7% on green hydrogen news

    a man stands at a green blackboard where a scientific equation is written in chalk. He looks over his shoulder and holds two fingers of each hand in the air as he smiles, trying to illustrate the formation of hydrogen atoms.a man stands at a green blackboard where a scientific equation is written in chalk. He looks over his shoulder and holds two fingers of each hand in the air as he smiles, trying to illustrate the formation of hydrogen atoms.a man stands at a green blackboard where a scientific equation is written in chalk. He looks over his shoulder and holds two fingers of each hand in the air as he smiles, trying to illustrate the formation of hydrogen atoms.

    The Sparc Technologies Ltd (ASX: SPN) share price is jumping today amid an update on the company’s green hydrogen project.

    The South Australian company’s shares are currently swapping hands at $1.22, a 6.55% gain, after trading at a high of $1.30 earlier in the session.

    Let’s delve into what the company revealed today.

    Joint venture

    Sparc provided an update on its joint venture with Fortescue Metals Group Limited‘s (ASX: FMG) hydrogen-focused renewable energy subsidiary Fortescue Future Industries (FFI) and the University of Adelaide.

    The project aims to produce commercially viable green hydrogen via a process known as photocatalysis. This involves making hydrogen from water using radiation from the sun.

    Sparc reported the transaction is complete and all conditions have been met. Fortescue Future Industries has already made a stage 1 payment to Sparc Hydrogen of $1.8 million. In stage 1 of the project, Sparc will hold 52% of the venture while the university will hold 28% and Fortescue 20%.

    As my Foolish colleague Brooke reported last week, both Fortescue and Sparc will eventually own 36% of the venture in stage 2 while the University of Adelaide will hold the remaining 28%.

    In today’s announcement, Sparc said work on the project has commenced and key equipment has been ordered. An initial techno-economic assessment of the technology is also underway.

    Management comment

    Commenting on the announcement, executive chairman Stephen Hunt said:

    It is pleasing to now have satisfied all conditions to complete the transaction and to work with Fortescue Future Industries and University of Adelaide to further progress this exciting project.

    Furthermore, the inclusion in the joint venture of world leading green energy company, Fortescue Future Industries, adds enormous value to the joint venture, both in terms of project development, technology and commercialisation capabilities.

    Share price snapshot

    In the last 12 months, the Sparc Technologies share price has soared 321%. For perspective, the S&P/ASX 200 Index (ASX: XJO) has returned nearly 6% over the past year.

    However, year to date, the Sparc share price has dropped 26%, losing more than 27% in the past week alone.

    Sparc Technologies has a market capitalisation of about $80 million based on its current share price.

    The post Sparc Technologies (ASX:SPN) share price rallies 7% on green hydrogen news appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Sparc Technologies right now?

    Before you consider Sparc Technologies , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Sparc Technologies wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/h5c92ye

  • How far off is BHP (ASX:BHP) from producing ‘green steel’?

    The planet earth floats in light about an outstrecthed hand, indicating sustainability

    The planet earth floats in light about an outstrecthed hand, indicating sustainabilityThe planet earth floats in light about an outstrecthed hand, indicating sustainability

    BHP Group Ltd (ASX: BHP) could be getting closer to ‘green steel’.

    There is a growing focus to try to decarbonise operations and industries where possible. But some areas are easier to decarbonise than others. Typically, producing steel can be fairly carbon-intensive and pollutive because of the process involved.

    According to the International Energy Agency, the iron and steel industry accounts for approximately 6.7% of total world CO2 emissions. Around 1.9 tonnes of CO2 are emitted for each tonne of steel produced.

    Green steel could be the answer. What’s green steel? It’s the idea that steel can be made with zero emissions using some sort of green or renewable energy for the process.

    Is BHP getting closer to green steel?

    BHP is one of the world’s biggest producers of iron ore. BHP’s iron ore division makes billions of dollars, so it is an important segment. What part can BHP do in a decarbonising world?

    The ASX’s resources giant is reportedly in discussions with a business called Boston Metal about bringing some new technology to Australia “very shortly” according to reporting by the ABC.

    Boston Metal is aiming to deliver commercial quantities of green steel by 2025 without using hydrogen, coal or a blast furnace. The technique is called molten oxide electrolysis which utilises renewable electricity to transform iron ore into liquefied metal which can then be used for the next step like casting or rolling.

    The ABC reported that when Boston Metal raised $50 million last year, BHP was one of the entities that was involved, along with Bill Gates’s Breakthrough Energy Ventures.

    Is green steel realistic?

    It has reportedly already happened. The Swedish company SSAB has shipped some green steel, made using hydrogen, to the carmaker Volvo.

    There are several different businesses and organisations trying to get involved with green steel.

    The race is on

    Boston Metal is obviously one of the contenders. Fortescue Metals Group Limited (ASX: FMG) is one ASX share that’s working on green steel.

    BlueScope Steel Limited (ASX: BSL) is another business that is thinking about green steel, as Australia’s biggest steel producer. It is working on a plan to make green steel by using green hydrogen by utilising an electrolyser (powered by renewable energy) to split water into hydrogen and water. However, this uses a lot more electricity.

    Rio Tinto Limited (ASX: RIO) and BlueScope are working together to explore low-carbon steelmaking using Pilbara iron ore. Last year, the two businesses signed a memorandum of understanding (MOU) to research and design low-emissions processes for the steel value chain, including iron ore processing, iron and steelmaking and related technologies.

    Rio Tinto and BlueScope will prioritise studying the use of green hydrogen at the Port Kembla Steelworks in Australia.

    BHP is looking to reduce its carbon emissions across its operations. It has also decided to divest its petroleum operations.

    The post How far off is BHP (ASX:BHP) from producing ‘green steel’? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP right now?

    Before you consider BHP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison owns Fortescue Metals Group Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Fc3r5xX