Category: Stock Market

  • 2 medical tech ASX shares for turbulent times

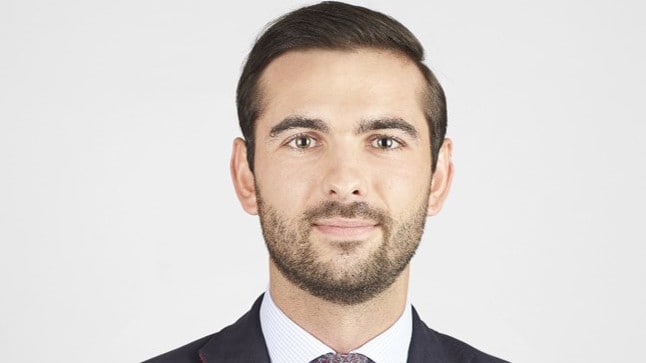
    ASX shares fund manager Rory HunterASX shares fund manager Rory HunterASX shares fund manager Rory Hunter

    Ask A Fund Manager

    The Motley Fool chats with fund managers so that you can get an insight into how the professionals think. In this edition, SG Hiscock portfolio manager Rory Hunter reveals the 2 medical tech businesses that are the perfect ballast for small caps during these volatile times.

    Investment style

    The Motley Fool: How would you describe your SGH Medical Technology Fund to a potential client?

    Rory Hunter: I’ve been running SG Hiscock’s small companies fund for about 3 years. And we’ve had some very good success with that fund and seen strong performance. I’ve been working with Adrian Di Mattina, who runs the emerging companies fund, which is a micro-cap strategy, so there’s a bit of a crossover in the funds. We work in the same team and it’s a collaborative research effort. 

    We’ve had some pretty decent success in the healthcare space. In addition to that, one of our board members, a lady by the name of Brenda Shanahan, has recently received an Order of Australia for her services, not just in finance, but also to the healthcare industry and academic institutions. 

    So bringing that all together, and especially with Brenda’s network in mind and her expertise, we felt for quite some time that we’re better equipped than our competitors to do a specifically focused strategy which addresses the healthcare space. 

    Obviously, the pandemic came along and we realised that… the healthcare industry has always been amazingly laggard to other industries globally in terms of technological adoption. The healthcare industry has been very, very slow to adopt technology and there’s always been a lot of regulatory inertia and a lack of desire amongst the participants to actually change and adopt technology. 

    We had half-an-eye on the fact that you’ve got ageing Western world demographics, more ageing demographics in developed economies and the strain that that’s actually putting on healthcare services and the healthcare system. You’ve got the need for healthcare institutions to eke out efficiencies and drive down costs and increase capacity.

    The best way for them to do that is to adopt medical technology. 

    Then obviously there’s the advent of the pandemic. About 18 months ago… we took the view that the pandemic had actually acted as our necessary catalyst to get the healthcare sector up to speed with other industries and sectors around the world, in terms of technological adoption.

    Australia has always punched above its weight when it comes to innovation in medical technology. The likes of CSL Limited (ASX: CSL), Cochlear Limited (ASX: COH), Resmed CDI (ASX: RMD), Pro Medicus Limited (ASX: PME), Nanosonics Ltd (ASX: NAN) — these are all global businesses, and then you look at the likes of CSIRO [and] research centres of excellence as well. 

    Australia’s just a great place to find good opportunities in medical technology. And we feel that we have the expertise in order to do that. And we feel that moving forward over the next 10 years, this will be the dominant growth rate that’s available to global equity investors. 

    MF: Cynics of the medical technology sector might say those companies have binary outcomes. What would you say to that?

    RH: I’d absolutely agree, however, with the caveat that you have to throw biotech companies into that bucket, rather than medtech companies. 

    It was something that came to us immediately when we launched this strategy, which was the fact that biotechnology companies do have binary outcomes. 

    And typically those binary outcomes take up to 10 years to evolve. So you’ve got that time erosion on capital, but they’re also very, very capital intensive. They’re funding clinical trials, incredibly capital intensive. So the path from drug discovery into the commercialisation of the drugs can take 10 years. And require hundreds of millions of dollars of capital, which highly dilute shareholders who’d been there from early on. 

    As a result of that, we are predominantly focused on medical technology as opposed to biotechnology. And so it doesn’t mean that we won’t look at biotechnology opportunities, but we’re just far, far more selective. Typically we’ll have a skew of probably at least 80% of the portfolio in medtech rather than biotech. 

    Biggest convictions

    MF: What are your two biggest holdings?

    RH: The two biggest holdings currently are CSL and Resmed.

    It’s actually more of a strategic positioning with the macroeconomic backdrop in mind. When we came to setting up the fund, we wanted to set it up with a small companies bias, but [with] the ability to invest across the life cycle spectrum and the ability to hold large companies as well, mainly because we recognised that you get a lot of volatility at this end of the tail. 

    The small companies, the innovative companies that are in early commercialisation, or at concept phase and who aren’t generating cash flows, aren’t generating profits.

    We wanted to provide some balance to the portfolio. As part of our equities research team, Hamish Tadgell, who runs our high-conviction broad-cap strategy, worked as a healthcare analyst at Goldman Sachs for a number of years. So we recognised that our resources were quite well suited for that as well. So we brought Hamish into the team for this strategy. 

    Our thinking there is just that there are actually few people on the buy side that actually understand those businesses as well as Hamish does, given his credentials. 

    We’ve always said that we’ll look at closing this strategy when it gets to about $100 million. And whilst large companies provide us with balance, they also provide us with the ability to shift the weight in between small and larger companies, depending on the macroeconomic backdrop. 

    We actually had a lot of pushback from early investors, or seed investors, on that front. They said they only wanted exposure to the innovative, early-stage, smaller companies. And we actually explained to them that depending on the macro backdrop, depending on sentiment, it can get very, very turbulent at that end of the market. 

    It turned out that since we launched this strategy about 6 to 8 months ago, the macroeconomic backdrop had deteriorated. We are thankful that we took that position because, otherwise, it would have been very painful for those investors. 

    We also feel that the larger companies in this space are exposed to the same tailwinds as those I’ve already spoken about as well. And so we think that there’s still very good growth in these businesses.

    The post 2 medical tech ASX shares for turbulent times appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tony Yoo owns CSL Ltd., Cochlear Ltd., and ResMed Inc. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended CSL Ltd., Cochlear Ltd., Nanosonics Limited, and Pro Medicus Ltd. The Motley Fool Australia owns and has recommended Nanosonics Limited and Pro Medicus Ltd. The Motley Fool Australia has recommended Cochlear Ltd. and ResMed Inc. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/8mJAenO

  • The Beach Energy (ASX:BPT) share price is outperforming the ASX 200 by 23% in 2022

    Key points

    • The Beach Energy share price has gained 18% in 2022, compared to the ASX 200’s 4% tumble
    • The energy producer’s gains might have been spurred by soaring oil prices
    • Beach released its quarterly report last month

    The new year has been good to the Beach Energy Ltd (ASX: BPT) share price.

    As of Friday’s close, the Beach Energy share price is $1.49 – 18.65% higher than its closing price of $1.26 on 31 December.

    For comparison, the S&P/ASX 200 Index (ASX: XJO) has slipped 4.36% over that timeframe.

    That leaves the energy producer’s share price outperforming the ASX 200 by 23% since the final close of 2021.

    So, what’s been boosting the company’s shares lately? Let’s take a look.

    Why is the Beach Energy share price surging in 2022?

    The Beach Energy share price has had a brilliant start to 2022, surging alongside the price of oil.

    The oil price has been the topic of many conversations this year, and it caused another round of excitement on Friday.

    Then, West Texas Intermediate crude oil was trading for more than US$90 per barrel, surpassing the milestone figure for the first time since 2014, according to CNBC.

    Meanwhile, prior to the ASX’s close on Friday, the price of Brent crude oil reached an intraday high of US$91.64.

    Bolstering oil prices – appearing alongside troubles among OPEC+ member states – likely helped Beach Energy’s stock to surge 4.2% last week.

    However, it hasn’t all been sunny for the company in 2022. Its stock slid 7.7% on the release of its quarterly update in late January.

    Over the three months ended 31 December, Beach Energy’s production slipped 7% compared to the prior quarter. Its sales volume also dropped 5% quarter-on-quarter. Though, rising oil prices leant themselves to lifting its sales revenue by 3%.

    Interestingly, the energy producer isn’t even the best performing ASX 200 energy share of 2022 so far.

    That title goes to the Woodside Petroleum Limited (ASX: WPL) share price and its 19.7% gain.

    Despite the Beach Energy share price’s strong gains over the beginning of 2022, its longer term performance is still in the red.

    Since this time last year, the company’s stock has slipped 17%.

    The post The Beach Energy (ASX:BPT) share price is outperforming the ASX 200 by 23% in 2022 appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Beach Energy right now?

    Before you consider Beach Energy, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Beach Energy wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/O4K5F6b

  • ANZ (ASX:ANZ) share price on watch following first quarter update

    city building with banking share prices, anz share price

    city building with banking share prices, anz share pricecity building with banking share prices, anz share price

    The Australia and New Zealand Banking Group Ltd (ASX: ANZ) share price will be on watch on Monday.

    This follows the release of the banking giant’s first quarter market update this morning.

    ANZ has tough start to FY 2022

    ANZ’s market update revealed that the bank has had a tough start to FY 2022.

    According to the release, revenue within the bank’s Markets business for the month of October was softer than expected given tough trading conditions. And while subsequent months have performed more in line with FY 2021 revenue trends, management warned that the softer start in October will likely impact its first half performance.

    In addition, just like rival Westpac Banking Corp (ASX: WBC), ANZ revealed a reduction in its net interest margin (NIM) during the quarter. The bank reported an 8 basis points decline in its NIM (5 basis points on an underlying basis). This was largely driven by a lower exit rate at the full year and a continuation of the structural headwinds impacting the sector.

    Rising rates offer some relief

    Positively, the impact of rising rates, predominantly in New Zealand, and recent deposit pricing changes are expected to moderate these ongoing headwinds in the second quarter.

    Another positive is that the bank has made solid progress in Australia to improve systems and processes for simple home loans. It advised that application times are now in line with other major lenders. In addition, efforts continue to improve response times for more complex home loan applications.

    Speaking of home loans, ANZ’s Australian home loans balance sheet grew slightly in the first quarter. And given the high levels of refinancing activity in the sector, the bank revealed that its management of both attrition and margins remain key areas of focus.

    Though, one thing the bank is willing to take a hit on is the package offered within its Australian Retail & Commercial business. It is making changes from March that will provide customers with simpler and lower fee options. While it notes that this is better aligned to positive customer outcomes, the changes will have a negative transitional impact on other operating income in FY 2022 of ~$140 million. This will be spread evenly across the two halves.

    Outside this, run-the-bank costs are expected to be broadly flat in the first half with investment spend higher as it invests in its business at a faster rate.

    Credit quality opens the door to further capital returns

    ANZ had a positive quarter in respect to credit quality. It advised that the credit quality environment has remained benign with a total provision release of $44 million during the quarter. This comprises a collective provision release of $122 million and an individually assessed provision of $78 million.

    All in all, this led to the bank ending the period with a CET1 ratio of 11.65%. Management advised that this strong capital position continues to provide it with flexibility to return further surplus capital to shareholders. As a result, it is considering increasing the size of the current on-market buy-back. Though, any decision will balance the importance of capital efficiency against maintaining an appropriately strong balance sheet and continued monitoring of the economic situation.

    The post ANZ (ASX:ANZ) share price on watch following first quarter update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ANZ right now?

    Before you consider ANZ, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ANZ wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro owns Westpac Banking Corporation. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Westpac Banking Corporation. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/kH7APy9

  • 2 ASX shares to guide you through a torrid 2022

    Two women hold up their biceps in a show of strength.Two women hold up their biceps in a show of strength.Two women hold up their biceps in a show of strength.

    If you’ve been following US and ASX shares even casually this year, it would be apparent markets have been in turmoil.

    After dropping 10% during January, a slight reprieve the past few days has seen the S&P/ASX 200 Index (ASX: XJO) still shave almost 7% off since the year started.

    Across the Pacific, the NASDAQ-100 (NASDAQ: NDX) has tumbled a horrible 12.3% over the same five weeks.

    Yikes.

    And that’s just on the fear of interest rate rises. Rates actually haven’t gone up yet.

    So with further volatility expected in 2022, what are the ASX shares that might be able to minimise the grey hairs this year?

    A couple of experts answered that very question this week.

    Packaging life’s essentials

    Elston Asset Management portfolio manager Bruce Williams nominated Amcor CDI (ASX: AMC) as the stock that could endure a stormy 2022.

    “It’s a packaging business that is dominant in what it does, in each of the markets in which it participates,” he told Livewire.

    “It generates excellent cash flow. It’s building its technology around sustainable and recyclable packaging.”

    Williams likes the essential nature of its clientele.

    “The basis of its business is consumer staples, so things like healthcare, food, those sorts of things,” he said.

    “We think it’s just a terrific defensive position that — through a combination of capital growth, dividends and buybacks — will generate consistent returns for investors for the foreseeable future.”

    Amcor shares have gained almost 15% over the past 12 months. The stock closed Friday at $16.66.

    No matter what the stock market does, Australians still have to eat

    The operator of the IGA supermarket brand, Metcash Limited (ASX: MTS), is Investors Mutual senior portfolio manager Simon Conn’s tip.

    “We think it’s an underappreciated franchise, and a business that’s no doubt benefited from COVID, but I think that’s delivered enduring benefits to their food business,” he said.

    “The liquor business has been growing and is a very resilient business. But really it’s the hardware business — where they position themselves as the second player in the hardware, retail and wholesale markets — that we think is underappreciated by investors.”

    Metcash shares have performed nicely over the past year, gaining more than 21% while handing out a 4.8% dividend yield.

    However, the stock has plummeted in excess of 7% to start this year, perhaps opening up a nice buying opportunity.

    “Local consumers are spending more in their local communities, and we think that will continue to a large extent, going forward,” Conn said.

    “It’s really attractively priced on [a PE ratio of] 13 times… with a really strong balance sheet. For us, it looks like a standout in the market, where a lot of stocks look pretty fully priced.”

    The Metcash share price closed Friday at $4.17.

    The post 2 ASX shares to guide you through a torrid 2022 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Amcor Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/g4Ya6C5

  • Blimey: Macquarie (ASX:MQG) share price in focus on possible £10 billion UK deal

    piggy bank at end of winding roadpiggy bank at end of winding road

    piggy bank at end of winding roadThe Macquarie Group Ltd (ASX: MQG) share price is in focus on news that the global bank may be on track for a UK £10 billion investment.

    That’s according to the reporting by Sky News.

    What’s Macquarie’s potential UK deal?

    Australia’s leading international investment bank is talking with the UK leadership in Downing Street about a potential £10 billion investment into British infrastructure. If the deal were to go ahead, it would be one of the largest investments by an overseas company in the UK.

    This reportedly isn’t just an idea at the early stages. Macquarie and Downing Street have been discussing things for a “number of weeks”.

    Macquarie is one of the world’s biggest infrastructure investors. If the £10 billion deal were to go ahead, it will comprise a range of renewable energy investments. Some of these have already been publicly announced by Macquarie. But there are several new projects that are reportedly in the energy and the communications infrastructure sectors.

    The Aussie investment bank already has a significant presence in the UK, including with its Green Investment Group.

    Some of the current Macquarie investments in the UK include a fibre network in northern England and a large stake in Southern Water.

    The investment could be a combination of capital from its own balance sheet and the funds it manages.

    Why is the UK keen for Macquarie’s involvement?

    Politically, the UK is looking for business partnerships, investment, trade deals and so on in this post-Brexit world it now finds itself.

    At the end of last year, Australia and the UK signed a trade deal.

    Sky News also reported that the UK Prime Minister wants to show that he can act as a post-Brexit “magnet for overseas capital”.

    How likely is it to happen?

    The British PM sees the potential for Macquarie’s investment to help increase investment in regions of the UK a time when many of the headlines in the UK are about COVID rules being broken, according to reporting.

    It’s expected that Boris Johnson will visit Australia in the coming weeks and the announcement will be planned for that trip.

    In a statement to Sky News, Macquarie said:

    The UK is one of the best places in the world to invest in, and from.

    It’s our hub for operations across Europe, the Middle East and Africa and we’ve been proud to invest over £50bn in critical UK infrastructure in recent years.

    Over the next few years, we’ll progress important new investments in communities from Southampton to Orkney, in vital new infrastructure from offshore wind to ultra-fast broadband.

    Maquarie share price snapshot

    Over the last year the Macquarie share price has risen more than 40%. However, since the start of the year it is down around 9%.

    The post Blimey: Macquarie (ASX:MQG) share price in focus on possible £10 billion UK deal appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Macquarie right now?

    Before you consider Macquarie, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Macquarie wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/ZmhK7ek

  • This strategy for investing in ASX shares has an 82% success rate

    Man puts hands in the air and cheers with head back while holding phone and coffeeMan puts hands in the air and cheers with head back while holding phone and coffeeMan puts hands in the air and cheers with head back while holding phone and coffee

    The old investment adage of “buy low, sell high” is an odd concept.

    Most experts will tell you timing the market is fraught with danger. No one, professional or amateur, has a crystal ball.

    So how are you supposed to buy low and sell high when you don’t ever truly know when the S&P/ASX 200 Index (ASX: XJO) is “low” and “high”?

    With that caveat in mind, it is still interesting to see historical patterns in market movements.

    January to April seems to be a golden period for shares

    There is the famous Santa Rally, which sees ASX shares go up in December more often than not.

    But prominent Bell Potter adviser Richard Coppleson has dug up another interesting ASX 200 trend that is especially relevant right now.

    “Over the last 29 years, one of the best buying opportunities has been to buy during the sell-off that the market has most Januarys and holding for 3.5 months until the end of April,” he posted on Livewire.

    “This strategy has had a phenomenal winning success rate of 82%.”

    Out of the 29 years, this philosophy has seen positive returns 24 times.

    The average return over just those 3.5 months has been a huge 5.75%. Before the March 2020 COVID-19 crash, that average was running at 6.57%.

    “Considering the average gain in the ASX 200 each year over 12 months since 1993 has been +6.56%, this is significant,” said Coppleson.

    “While the 24 times it was UP the return was a massive +7.8%.”

    Even in bad years, this strategy can help

    Remarkably, even in the 8 years that the ASX 200 lost money for investors, the January to April strategy mostly performed better than the yearly return.

    Those 8 years saw an average of 0.34% positive return for Coppleson’s 3.5-month tactic, while the yearly losses averaged 11.64%.

    “Every year bar just one — 2020 where COVID stuffed it all up — all the others OUTPERFORMED significantly… by a massive margin vs where the market closed for that year.”

    This is all to say historically it seems to be wise to be fully invested in ASX shares during the first few months of the year.

    “If you are worried about the year then reducing net long positions at the end of April can be a very good strategy.”

    The post This strategy for investing in ASX shares has an 82% success rate appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/0wXCfgt

  • 2 ASX dividend shares with big yields to buy

    a woman with a huge happy smile on her face eyes a jar of coins next to her on a table.

    a woman with a huge happy smile on her face eyes a jar of coins next to her on a table.a woman with a huge happy smile on her face eyes a jar of coins next to her on a table.

    If you’re wanting to boost your income with some dividend shares, then you might want to consider the ones listed below.

    Both of these dividend shares are expected to provide investors with attractive yields in 2022. Here’s what you need to know about them:

    Adairs Ltd (ASX: ADH)

    The first ASX dividend share for investors to look at this week is Adairs. It is one of Australia’s leading furniture and homewares retailers. As well as the core Adairs brand, it owns the online-only Mocka brand and recently acquired the Focus on Furniture brand.

    And while FY 2022 has been tough so far due to COVID-19 headwinds, this weakness is only expected to be temporary. Which could make the recent selloff of its shares a buying opportunity for patient income investors.

    Morgans certainly believes this to be the case. In response to the update, the broker has retained its add rating but cut its price target to $3.70. In addition, it is now forecasting fully franked dividends of 19 cents per share in FY 2022 and 26 cents per share in FY 2023.

    Based on the current Adairs share price of $3.25, this will mean yields of 5.8% and 8%, respectively, over the next couple of years.

    Centuria Industrial REIT (ASX: CIP)

    Another ASX dividend share to look at is this leading property company with a focus on high quality industrial assets.

    Thanks to strong demand for its properties, Centuria Industrial recently reported a weighted average lease expiry (WALE) of 8.9 years with a 99.2% portfolio occupancy rate. This is underpinning stronger than expected funds from operations (FFO) growth in FY 2022. So much so, last month management upgraded its FFO guidance to no less than 18.2 cents per share.

    This is expected to underpin a distribution of 17.3 cents per share in FY 2022. Based on the current Centuria Industrial share price of $3.87, this will mean a yield of 4.5%.

    Morgan Stanley is a fan of the company. In response to its guidance upgrade, the broker retained its overweight rating and lifted its price target to $4.35.

    The post 2 ASX dividend shares with big yields to buy appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ADAIRS FPO. The Motley Fool Australia owns and has recommended ADAIRS FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/5XnIYJ3

  • 5 things to watch on the ASX 200 on Monday

    Smiling man with phone in wheelchair watching stocks and trends on computer

    Smiling man with phone in wheelchair watching stocks and trends on computerSmiling man with phone in wheelchair watching stocks and trends on computer

    On Friday the S&P/ASX 200 Index (ASX: XJO) finished the week in a positive fashion. The benchmark index rose 0.6% to 7,120.2 points.

    Will the market be able to build on this on Monday? Here are five things to watch:

    ASX 200 expected to fall

    The Australian share market looks set to start the week in the red despite a positive finish on Wall Street on Friday. According to the latest SPI futures, the ASX 200 is expected to open the day 41 points or 0.6% lower this morning. On Wall Street, the Dow Jones fell 0.05%, the S&P 500 rose 0.5%, and the Nasdaq stormed 1.6% higher.

    Oil prices push higher

    Energy producers such as Santos Ltd (ASX: STO) and Woodside Petroleum Limited (ASX: WPL) could have a strong start to the week after oil prices pushed higher on Friday. According to Bloomberg, the WTI crude oil price rose 2.25% to US$92.31 a barrel and the Brent crude oil price rose 2.4% to US$93.27 a barrel. Oil prices hit seven-year highs after a winter storm in Texas heightened supply concerns.

    ANZ Q1 update

    The Australia and New Zealand Banking Group Ltd (ASX: ANZ) share price will be on watch this morning when it becomes the latest big four bank to release its first quarter update. All eyes will be on the bank’s net interest margin (NIM) amid the aggressive competition for home loans. Also worth looking out for will be ANZ’s cost growth. Goldman expects the bank’s costs to grow 0.9% over the 12 months.

    Gold price edges higher

    Gold miners Newcrest Mining Limited (ASX: NCM) and Northern Star Resources Ltd (ASX: NST) could start the week in the green after the gold price rose on Friday night. According to CNBC, the spot gold price rose 0.2% to US$1,807.8 an ounce. The gold price pushed higher after inflation concerns offset higher US treasury yields.

    Pro Medicus shares upgraded to buy rating

    The Pro Medicus Limited (ASX: PME) share price could be in the buy zone according to the team at Bell Potter. This morning the broker has upgraded the health imaging technology company’s shares to a buy rating with a $55.00 price target. Bell Potter believes recent weakness has created a buying opportunity.

    The post 5 things to watch on the ASX 200 on Monday appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Pro Medicus Ltd. The Motley Fool Australia owns and has recommended Pro Medicus Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/29PTLoO

  • 3 top ETFs for ASX investors to look at this month

    a business person in a suit traces the outline of an upward arrow in a stylised foreground image with the letters ETF and Exchange Traded Funds underneath.

    a business person in a suit traces the outline of an upward arrow in a stylised foreground image with the letters ETF and Exchange Traded Funds underneath.a business person in a suit traces the outline of an upward arrow in a stylised foreground image with the letters ETF and Exchange Traded Funds underneath.

    Are you looking for some exchange traded funds (ETFs) to add to your portfolio? If you are, it could be worth taking a closer look at the three ETFs listed below.

    These ETFs include some of the highest quality companies on offer globally across the banking, healthcare, and tech sectors. Here’s what you need to know about them right now:

    BetaShares Asia Technology Tigers ETF (ASX: ASIA)

    If you’re wanting to gain exposure to the growing Asian economy, then the BetaShares Asia Technology Tigers ETF could be a way to do this. This ETF gives investors access to a number of the most promising tech shares in the Asian market. These are the Apples, Googles, and Amazons of Asia such as e-commerce leaders Alibaba and JD.com, search engine company Baidu, and WeChat owner Tencent.

    iShares Global Healthcare ETF (ASX: IXJ)

    Another ETF to look at is the iShares Global Healthcare ETF. This ETF provides investors with easy access to many of the biggest and brightest healthcare companies in the world. This includes Australia’s CSL Ltd (ASX: CSL) and Ramsay Health Care Limited (ASX: RHC), as well as a host of global giant such as Astra Zeneca, Johnson & Johnson, Moderna, Novartis, Pfizer, and Sanofi.

    VanEck Vectors Australian Banks ETF (ASX: MVB)

    Finally, if you’re wanting exposure to the banking sector, then you might want to look at the VanEck Vectors Australian Banks ETF. This ETF allows you to own a slice of all the big four banks, the regionals, and investment bank Macquarie Group Ltd (ASX: MQG) through a single investment. As these bank shares are traditionally big dividend payers, this ETF could prove to be a good source of income for investors.

    The post 3 top ETFs for ASX investors to look at this month appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended BetaShares Asia Technology Tigers ETF. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/oNPdn7O

  • Got money to invest for dividends? Here are 2 ASX shares that could be buys

    two children dressed in business attire with joyous, wide-mouthed expressions count money at a desk covered in cash and sacks of money either side.two children dressed in business attire with joyous, wide-mouthed expressions count money at a desk covered in cash and sacks of money either side.two children dressed in business attire with joyous, wide-mouthed expressions count money at a desk covered in cash and sacks of money either side.

    Key points

    • ASX dividend shares can be very effective at boosting investment income
    • Adairs is a retail stock that sells homewares and furniture. Rolling out more stores and increasing online sales are key strategies
    • GQG is steadily growing its FUM and has committed to a fairly high dividend payout ratio

    ASX dividend shares could be an excellent place to look for income for investors wanting to boost their investment yield.

    When a share price drops, it can have the added bonus of increasing the prospective dividend yield for investors that buy shares.

    The recent ASX share market correction could make these two options very attractive for dividends

    Adairs Ltd (ASX: ADH)

    Adairs is a retail stock that sells a wide range of furniture and furnishings. It has the Adairs network of stores, but it also has online furniture business Mocka, and also Focus on Furniture after making an acquisition.

    The business is working hard at ensuring customers can buy however they want to – online or in-store. It has recently invested in a new national distribution centre which is expected to save costs as well as being able to ensure it can fulfil orders faster and provided stores with better stock flow.

    Another of the ASX dividend share’s key profit-boosting tactics is to open more large-format stores. They are substantially more profitable than smaller ones as it allows the company to sell more of its products in a single location. An upsized store is approximately 60% more profitable according to Adairs.

    With Focus, Adairs also has plans to roll-out a national store network, expand its product offerings and grow online sales. It also increases Adairs’ exposure to the ‘bulky furniture’ category.

    It’s currently rated as a buy by Morgans with a projected grossed-up dividend yield of 8.3% in FY22 and 11.4% in FY23.

    GQG Partners Inc (ASX: GQG)

    GQG is one of the largest fund managers on the ASX. It is a US-based fund manager, though it does have ambitions of growing funds under management in different places like Australia.

    This fund manager offers a few different investment strategies such as US share funds, international share funds and dividend share funds.

    One of the main ways that GQG Partners, and any fund manager, can grow profit, is by growing funds under management (FUM). On 30 September 2021, the FUM was US$85.8 billion. By 31 December 2021, FUM had grown to be $91.2 billion. In the three months to December 2021, quarterly net inflows were US$3 billion.

    The ASX dividend share seeing business momentum across multiple geographies and channels. Its recently launched strategies and products continue to achieve “strong adoption”.

    Not only are GQG’s management fees lower than many active fund managers, but its management fees comprise the vast majority of its net revenue, as opposed to performance fees.

    The management team is “highly aligned” with all shareholders as the largest shareholders in GQG. Management are “acutely focused on and committed” to GQG’s future.

    It’s currently rated as a buy by Morgans, with a price target of $2.40. The broker thinks it has compelling long-term potential with solid earnings.

    The broker projects that GQG will pay a dividend yield of 7.4% in FY22 and 8.6% in FY23.

    The post Got money to invest for dividends? Here are 2 ASX shares that could be buys appeared first on The Motley Fool Australia.

    Should you invest $1,000 in GQG Partners right now?

    Before you consider GQG Partners, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and GQG Partners wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ADAIRS FPO. The Motley Fool Australia owns and has recommended ADAIRS FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/RTVWU1P