Category: Stock Market

  • Wesfarmers (ASX:WES) threatens to fly the WA coop. Here’s the latest

    AMP share price fall represented by illustration of large boot almost trampling three businessmen

    AMP share price fall represented by illustration of large boot almost trampling three businessmenAMP share price fall represented by illustration of large boot almost trampling three businessmen

    Wesfarmers Ltd (ASX: WES) is one of Australia’s biggest employers.

    With a market cap of some $60 billion, the S&P/ASX 200 Index (ASX: XJO) listed retail giant’s subsidiaries include the likes of Bunnings Warehouse, Kmart Australia, Officeworks and more.

    While Wesfarmers’ corporate headquarters is located in Perth, Western Australia, the bulk of the company’s operations take place in the more populace eastern states.

    In ordinary times that’s worked fine. But with the Omicron COVID variant seeing Western Australia Premier Mark McGowan delay his state’s reopening to the rest of the nation, Wesfarmers’ management has had enough.

    Packing their bags

    Wesfarmers’ CEO Rob Scott and his management team have been operating in the isolated city of Perth, waiting for the state border to reopen as promised.

    Now that the border reopening looks to be again delayed, The Australian reports that Scott and some of his top executives “are this week preparing to relocate to the east coast for an extended period – the first time in Wesfarmers’ 108-year history this has happened”.

    Scott said it’s “virtually impossible” to run a national business from Perth under the current travel restrictions.

    He said his company is supportive of “a cautious and risk-based approach” to keep the pandemic in check. However, Western Australia’s delay in lifting its border restrictions “is out of step with the rest of the country, and most of the world”.

    According to Scott (quoted by The Australian):

    We really look forward to the WA government announcing a plan which addresses these issues in the coming weeks. The lack of consideration for national businesses and extended delays is also damaging WA’s reputation with talent.

    We’ve benefited in the past from attracting some great talent to WA, with families relocating to create a life here. This is becoming increasingly difficult and is currently almost impossible, and I am concerned that this sentiment will linger.

    How has Wesfarmers been performing?

    Over the past 12 months the Wesfarmers’ share price is down 4.5%. That compares to a gain of 4.8% posted by the ASX 200.

    So far in 2022, Wesfarmers’ shares are down 12%.

    The post Wesfarmers (ASX:WES) threatens to fly the WA coop. Here’s the latest appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Wesfarmers Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/VqF9Rrwxv

  • ASX 200 (ASX:XJO) midday update: Ansell crushed, ResMed upgraded

    Man looks shocked as he works on laptop on top a skyscraper with stockmarket figures in graphic behind him.

    Man looks shocked as he works on laptop on top a skyscraper with stockmarket figures in graphic behind him.Man looks shocked as he works on laptop on top a skyscraper with stockmarket figures in graphic behind him.

    At lunch on Monday, the S&P/ASX 200 Index (ASX: XJO) has fought back from early weakness and is trading broadly flat. The benchmark index is currently down 1.5 points to 6,986.6 points.

    Here’s what is happening on the ASX 200 today:

    Ansell shares crushed

    The Ansell Limited (ASX: ANN) share price is crashing lower today after it downgraded its earnings guidance. The health and safety products company revealed that it expects its earnings per share to be between 125 US cents to 145 US cents in FY 2022. This is down materially from its previous guidance of 175 US cents to 195 US cents. Management blamed this on softening demand and COVID-related operational challenges.

    Pilbara Minerals’ mixed quarterly update

    The Pilbara Minerals Ltd (ASX: PLS) share price is pushing higher today following the release of a mixed second quarter update. Although the lithium miner fell short of its downgraded production guidance, which was given as late in the quarter as 21 December, and hinted that a downgrade to its guidance could be coming, investors have been buying its shares. This appears to be due to its expectations for the already sky high lithium prices to keep rising in the third quarter.

    ResMed rises on broker upgrade

    The ResMed Inc (ASX: RMD) share price is pushing higher today in response to a bullish broker note out of Goldman Sachs. According to the note, the broker has upgraded the sleep treatment company’s shares to a buy rating with a $35.80 price target. Goldman notes that near-term challenges have created a long-term opportunity for ResMed.

    Best and worst ASX 200 performers

    The best performer on the ASX 200 on Monday has been the Zip Co Ltd (ASX: Z1P) share price with a 7% gain on no news. The worst performer by some distance has been the Ansell share price with a 17% decline. This follows the release of its trading update and guidance downgrade.

    The post ASX 200 (ASX:XJO) midday update: Ansell crushed, ResMed upgraded appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ZIPCOLTD FPO. The Motley Fool Australia has recommended Ansell Ltd. and ResMed Inc. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/z4M6PBIc5

  • Energy One (ASX:EOL) share price gains 6% on acquisition news

    Workers at a wind farm in front of wind turbinesWorkers at a wind farm in front of wind turbinesWorkers at a wind farm in front of wind turbines

    Key points

    • The Energy One share price is rising 6.2% today
    • Energy One has entered a share purchase plan to take over CQ Energy Group
    • The total cost of the acquisition is $36 million

    The Energy One Ltd (ASX: EOL) share price is soaring today amid news the company has entered an agreement to take over an energy services company.

    The company’s shares are trading at $6 in morning trade, up 6.2%. Meanwhile, the S&P/ASX 200 Index (ASX: XJO) is down 0.39% at the time of writing.

    Sydney-based Energy One supplies software and services to energy, environment and carbon trading markets in Australia, the United Kingdom and Europe.

    Let’s take a look at what the energy company revealed to the market today.

    Energy One share price rises on acquisition

    The company announced it will take over CQ Energy Group based in Adelaide. Energy One said it has entered a share purchase agreement to acquire 100% of CQ Energy Group.

    CQ Energy provides 24-hour operational energy services to the Australian gas and electricity sector and has 20 staff and more than 30 customers, including wind farms, solar farms and industrial gas providers. Energy One describes the new addition as its “largest acquisition to date”.

    The acquisition is the latest in a string of takeovers by Energy One. The company took over Belgium-based Egssis in December 2021 and French-based eZ-nergy in June 2020.

    Commenting on the latest takeover, group chief executive officer Shaun Ankers said:

    The acquisition of CQ Energy builds on our strategy of developing a global 24/7 energy software and services business.

    CQ enhances our capability and now provides us with the opportunity to establish a global energy services operation with control rooms in both the northern and southern hemispheres.

    Energy One said the $36 million purchase includes cash and equity over 12 months. The initial outlay involves $26.4 million in cash and $6 million in Energy One shares.

    Speaking on the new team, Ankers added:

    CQ Energy is a very sophisticated business providing high quality operational services to the Australia [sic] energy trading market (West Coast and East Coast). And we are very excited to welcome them into the family.

    I’d like to welcome Reza Evans, Ian Tannebring & Lino Fusco to our leadership team.

    Energy One predicts the CQ acquisition will add about $7 million revenue and $4.5 million in earnings before interest, taxes, depreciation and amortisation (EBITDA) in the first financial year after consolidation. Overall, it is expected to grow its current EBITDA by about 50%.

    Share price snapshot

    Shares in Energy One have slipped 3.07% in the past 12 months. In the past month they have fallen 1.15%, while they’ve dropped 2.44% in the past week.

    For perspective, the ASX 200 has returned 5.18% in the last 12 months.

    Energy One has a market capitalisation of about $159 million based on its current share price.

    The post Energy One (ASX:EOL) share price gains 6% on acquisition news appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Energy One right now?

    Before you consider Energy One, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Energy One wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Monica O’Shea has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Energy One Limited. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/IG7KVCnjt

  • VGI Partners (ASX:VGI) share price surges 10% as merger deal sealed

    two people in business attire rise above the graphic image of a cityscape as if to join hands.two people in business attire rise above the graphic image of a cityscape as if to join hands.two people in business attire rise above the graphic image of a cityscape as if to join hands.

    Key points

    • VGI Partners share price is lifting on new of a proposed merger with an alternative investments manager
    • The proposed merger is with specialist alternative investment manager Regal Funds Management
    • The merger would involve VGI acquiring 100% of Regal
    • The company says it has the “potential to deliver several attractive benefits for VGI shareholders”

    Shares in global equity manager VGI Partners Ltd (ASX: VGI) are surging higher today and now trade 10% in the green at $4.81 apiece.

    The bulls have it today with VGI’s share price following a company announcement regarding a proposed merger with an alternative investments manager.

    According to VGI, the proposed merger would “combine two of Australia’s most recognised and successful hedge fund managers and create a market-leading provider of alternative investment strategies”.

    A joining of titans

    VGI advised it has entered exclusivity and signed a non-binding term sheet with specialist alternative investment manager Regal Investment Fund (ASX: RF1).

    It states that Regal Funds Management is a specialist alternatives investment manager “with a heritage built on long/short fundamental investing”.

    Regal was founded in 2004 and has offices located in Sydney and Singapore, whilst managing more than $3 billion in capital.

    The merger would involve VGI acquiring 100% of Regal in consideration for the issue of new ordinary shares in VGI to existing Regal shareholders, the company says.

    Collectively, a newly-amalgamated entity would see an alternative investment manager with a bolus of funds under management totalling more than $6 billion.

    The anticipated shareholding of the merged entity would be approximately 60% current Regal shareholders and 40% current VGI shareholders (after adjustments) according to the announcement.

    It is understood that VGI will be renamed and have a new ticker assigned to reflect the combined businesses once the transaction is completed.

    The deal is still subject to a number of conditions, notwithstanding shareholder vote and the approvals of each of VGI and Regal’s board of directors.

    What are the benefits, according to VGI?

    The company says a merger of the two companies has the “potential to deliver several attractive benefits for VGI shareholders”.

    For instance, it notes investors will have “exposure to a diversified and growing platform of hedge fund, private market and real asset investment strategies” both domestically and abroad.

    VGI can also “leverage additional resources from the merged group, including Regal’s extensive investment capability and track record investing in Asian equity markets and private unlisted investments”.

    The newly-formed entity will have a board of six directors, with two nominated by each of VGI and Regal in addition to the appointment of two external independent directors, per the release.

    VGI shareholders are not currently required to take any action in relation to the Proposed Merger. It is understood that VGI has appointed Jefferies Australia as financial advisor and Allens as legal advisor for the deal.

    “VGI has granted Regal a period of six weeks of exclusivity on customary binding terms which include no shop,
    no talk, and no due diligence restrictions…and an obligation for VGI to notify Regal if it receives a competing proposal”.

    The VGI share price has gained 4% in the last month, however is trading less than 2% in the red since January 1.

    The post VGI Partners (ASX:VGI) share price surges 10% as merger deal sealed appeared first on The Motley Fool Australia.

    Should you invest $1,000 in VGI Partners right now?

    Before you consider VGI Partners, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and VGI Partners wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Qp4YAbteH

  • Here’s why BHP shares are in the spotlight today

    A kangaroo stands on a sandy beach with vivid white sand and blue sea in the backgroundA kangaroo stands on a sandy beach with vivid white sand and blue sea in the backgroundA kangaroo stands on a sandy beach with vivid white sand and blue sea in the background

    Key points

    • Today is the first day the ‘unified’ BHP is trading on the ASX
    • The Big Australian now only calls Australia home after ditching London listing
    • What does a unified BHP mean for the ASX?

    It’s a big day on the ASX for the ‘Big Australian’… BHP Group Ltd (ASX: BHP) has today claimed its place as the largest ASX company on the share market. Yes, BHP was always a heavy hitter in terms of ASX market capitalisation.

    But because of this company’s dual-listing structure, its size was split between the ASX listing and its old listing on the London Stock Exchange.

    The ‘Big Australian’ now only calls the ASX home

    No more. Last year, BHP announced that it would be ending the 20-year status quo that was initially triggered by the old BHP buying the London-listed Billiton back in 2001. Today is the culmination of this ‘unification’ process.

    Ditching its London listing means that the company now only lists primarily on the ASX. There will still be secondary BHP listings in London, New York and Johannesburg. But these will only represent ownership of the ASX-listed shares.

    This comes after BHP announced earlier this month that the company has received the approval of all groups of shareholders to unify BHP’s dual-listed share structure. The British government also gave the proposal the green light earlier this month, which cleared the way for unification to take place today.

    So today is the first day that all BHP shares trade on the ASX.

    This morning, the company released an ASX announcement confirming this process. BHP  told investors that anyone who held the London-listed BHP plc (LON: BHP) shares will have them replaced with new BHP shares on the ASX. These will trade on a deferred settlement basis until 2 February. Until then, the replacement shares will trade under the ticker code ‘BHPN’. But after 2 February, all BHP shares on the ASX will revert to the standard ‘BHP’ ticker.

    So how has the BHP share price reacted to unification today? By falling 2.51% at the time of writing to $45.74 a share, that’s how. But even so, expect to see a lot of BHP shares trading on the markets today.

    What does a unified BHP mean for the ASX 200?

    So how will a unified BHP affect the S&P/ASX 200 Index (ASX: XJO)? Well, it is a fairly dramatic change.

    For starters, Commonwealth Bank of Australia (ASX: CBA) has had to relinquish its crown as the ASX’s largest share, perhaps permanently. Before today, CBA was the largest ASX share on the markets by quite a large margin, commanding an 8.2% or so weighting in the ASX 200 as opposed to BHP’s 6.9%.

    But now that BHP’s London shares have come back to the ASX to roost, we can flip this equation. For example, the BetaShares Australia 200 ETF (ASX: A200) has already updated its holdings and now lists BHP as its largest share with a weighting of 11.6%. CBA is a distant second with its 8% weighting.

    That makes sense. BHP’s ASX-listed market capitalisation now stands at $237.21 billion, whereas CBA remains at $162.35 billion.

    So from today, any ASX exchange-traded fund (ETF) covering the ASX 200 Index will now have a lot more exposure to BHP shares than it did last week. For an index known for its bank-and-miner dominance, we just got a whole lot more ‘miner’.

    The post Here’s why BHP shares are in the spotlight today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP right now?

    Before you consider BHP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/aY3C01695

  • Here’s why the Pointerra (ASX:3DP) share price is leaping 8% today

    two colleagues high five each other as they sit side by side at a long desk in front of their laptop computers in an office environment.two colleagues high five each other as they sit side by side at a long desk in front of their laptop computers in an office environment.two colleagues high five each other as they sit side by side at a long desk in front of their laptop computers in an office environment.

    Key points

    • The Pointerra share price is currently up 8.22%, trading at 39.5 cents
    • The gain follows the company’s announcement that its annual contract revenue increased 23% last quarter
    • Pointerra also plans to expand into the US and UK, as well as boost its Australian operations

    The Pointerra Ltd (ASX: 3DP) share price is surging this morning after the company updated the market on its enterprise sales and annual contract value (ACV).

    The company’s ACV increased 23% over the December quarter as Pointerra3D apparently becomes a “must-have” platform for the United States’ energy utility sector. As of today, its ACV stands at US$14.4 million.

    At the time of writing, the Pointerra share price is 39.5 cents, 8.22% higher than its previous close.

    Let’s take a closer look at the news driving the technology company’s stock.

    Pointerra share price soars on US$2.7m ACV growth

    The Pointerra share price is in the green after the company announced its ACV increased by US$2.7 million last quarter.

    The boost was driven by an increase in both customer numbers and spending, as the company continued to branch into sectors including surveying and mapping, architecture, engineering and construction, utilities, transport, mining, and oil and gas.

    Over the course of the December quarter – the results of which were released in the last fortnight – Pointerra was awarded between US$3.12 million and US$4.75 million of contracts within the US energy utility sector.

    Additionally, Pointerra says its customers in the sector are pushing their peers to adopt the company’s digital twin solution. That’s expected to drive growth in the future.

    As well, the company welcomed a record number of new customers over the December quarter.

    The buoyant Pointerra share price is also likely being impacted by its growth plans.

    The company will open its first office in the United States and begin operating in the United Kingdom. It’s hoped its UK base will drive growth in Europe, the Middle East, and Africa.

    Pointerra is also on the lookout for mergers and acquisitions to add knowledge of people and product in key industries.

    Finally, the company will be looking to bolster its personnel in Australia to support customer demand.

    As the company’s portfolio of customers matures in coming quarters, it will start reporting ACV totals by target sector.

    Its disclosure metrics will also evolve. It plans to start reporting such measures as average revenue per subscription, customer churn, net incremental ACV, and gross margin in the future.

    The post Here’s why the Pointerra (ASX:3DP) share price is leaping 8% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Pointerra right now?

    Before you consider Pointerra, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Pointerra wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Pointerra Limited. The Motley Fool Australia has recommended Pointerra Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Svsn7cCrh

  • Has the case for Bitcoin as an inflation hedge crumbled?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    A bitcoin sits on a graph with red arrow going down

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    It wasn’t all that long ago that many investors viewed Bitcoin (CRYPTO: BTC) as an ideal hedge against inflation. They reasoned that the cryptocurrency was like gold — long considered to be a solid inflation hedge — in one important way. Bitcoin was a limited resource, with a maximum of only 21 million coins allowed to exist.

    However, this theory doesn’t claim the luster that it once did. Here’s why.

    The numbers don’t lie

    Inflation remained low throughout the last decade. Meanwhile, Bitcoin delivered impressive gains. There wasn’t a compelling reason to dismiss the idea that the cryptocurrency could serve as a good hedge against inflation with inflation rates at historical lows.

    Then the COVID-19 pandemic changed everything. The federal government, afraid of the pandemic’s economic impact, responded with unprecedented stimulus packages. At the same time, supply chain disruptions resulted in many businesses being unable to keep up with demand. After a long hibernation, inflation began to rear its ugly head once again.

    It was the perfect scenario for Bitcoin to show just how great of an inflation hedge it could be. But it didn’t.

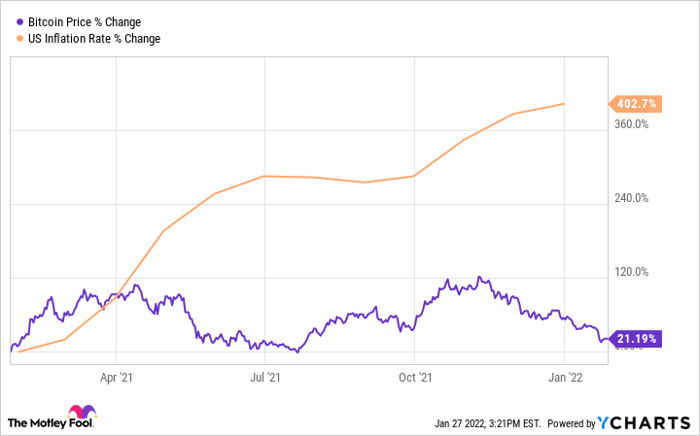
    Bitcoin Price Chart

    Bitcoin Price data by YCharts

    No, Bitcoin didn’t completely fall apart. However, over the past 12 months, the cryptocurrency took investors on a rollercoaster ride. It’s up, but only by a little over 20%. Bitcoin is currently near its lowest level in six months.

    The inflation rate, though, has more than quintupled during the same period. The numbers don’t lie: Bitcoin has proven to be an abysmal hedge against inflation.

    Bitcoin’s underlying problem

    Why isn’t Bitcoin better at hedging against inflation? We can easily rule out one possible reason. It isn’t that a large number of new digital coins have been mined. The number of Bitcoins in circulation has risen by less than 1.8% over the past 12 months.

    The primary underlying problem for Bitcoin is that for any asset to be an inflation hedge, investors must actually believe that it will hold its value as inflation rises. It’s abundantly clear that isn’t the case with Bitcoin.

    Bitcoin is only as valuable as investors believe that it is. It doesn’t have any real intrinsic value like stocks do.

    Investors think that cryptocurrencies, in general, are risky and volatile. And they seem to be lumping Bitcoin in with every other digital coin. Bitcoin has fallen roughly the same amount as some altcoins such as Dogecoin over the last three months.

    A hedge in waiting?

    Don’t throw in the towel on Bitcoin as an inflation hedge just yet, though. There’s still a possibility that the cryptocurrency could be exactly what investors once hoped it would be.

    Increased adoption of the cryptocurrency would help. The more real-world utility that Bitcoin has, the more justifiable its valuation will be. At some point, the digital coin’s valuation could become more stable.

    If and when this happens, Bitcoin’s fluctuations could inversely correlate with inflation rates much more than they do now. The cryptocurrency isn’t an inflation hedge yet, but it just might be a hedge in waiting. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Has the case for Bitcoin as an inflation hedge crumbled? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    Keith Speights has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and recommends Bitcoin. The Motley Fool Australia owns and recommends Bitcoin. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/pVKBWrHRT

  • The Treasury Wine (ASX:TWE) share price has plunged 25% from its 2021 highs. What’s next?

    Spilled wine and a glass on its side, indicating a share price drop for ASX wine companiesSpilled wine and a glass on its side, indicating a share price drop for ASX wine companiesSpilled wine and a glass on its side, indicating a share price drop for ASX wine companies

    Key points

    • Treasury Wine shareholders, have lost almost 15% since January 1
    • Morgan’s is constructive on the company, and see’s a potential of 34% at the current share price
    • The broker positive with its recent acquisition of Frank Family Vineyards
    • Goldman Sachs isn’t as positive on the Frank Family Vineyards transaction and is neutral on the stock

    The Treasury Wine Estates Ltd (ASX: TWE) share price is rangebound from the open today and is now trading at $10.57 apiece.

    Lately however, it’s been a bloodbath for Treasury Wine shareholders, having lost almost 15% since January 1 and more than 15% in the last month of trading.

    Shares in the wine specialist fell off the cliff-face in early January, amid a brutal ASX selloff that disproportionately hurt high-beta names like the company and its peers in the S&P/ASX 200 Consumer Staples Index (XSJ).

    Treasury Wine leads the broad index in losses this year with the wider sector booking a 9% dip into the red since we commenced trading in 2022.

    So what’s next for the listed-liquor player – whose portfolio includes brands like Penfolds, Beringer, Lindemans, Wolf Blass and Rosemount Estate and many more – in 2022? Let’s take a look.

    What’s next for Treasury Wine Estates?

    There’s no denying that January 2022 has been one to forget with respect to the stock market and its ability to create wealth.

    In fact, if global markets close down again today, it will mark the worst January performance on the major indices on record – that’s something to think about.

    Hence why the team at Morgan’s is constructive on the Treasury Wine share price, and see’s a potential of 34% upside with its valuation of $14.06 on the stock.

    “TWE has the China reallocation risk and it will take 2-3 years to recover these earnings in new markets. However once it comps China earnings, we expect TWE to deliver strong earnings growth from the 2H22 onwards” Morgans said in a recent note.

    “Organic growth will be supplemented by [merger and acquisition activity] M&A”, the broker says, noting strengths of this to the company’s earnings profile.

    With respect to the company’s recent M&A activity, Morgans was positive with its recent acquisition of Frank Family Vineyards, claiming the “high margin business” should accelerate Treasury Wine’s efficiency goals.

    “We view TWE’s recent acquisition of Napa Valley luxury wine business, Frank Family Vineyards (FFV) as strategically important” Morgans said in an update to clients.

    “This high margin business should see [Treasury Wine] achieve its US margin target two years earlier than planned.”

    Meanwhile, Goldman Sachs isn’t as positive on the Frank Family Vineyards transaction. The fellow broker had a mixed reaction to the company’s decision to tuck the smaller entity into its current portfolio of luxury brands.

    Goldman also noted the deal could add in additional e-commerce capacity and is parallel with the company’s pivot strategy in the Americas.

    “However”, the broker cautioned, “we remain conservative in the potential for FFV to become a margin accretive = channel for wine currently used in lower margin brands”.

    It expects “this acquisition to remain a lacklustre addition into FY22/23,” retaining its neutral rating on the stock, however, lifted its price target by 20 cents to $11.80 in the update.

    Alas, with the recent turmoil in global equity markets set to continue this week, time will tell which broker’s forward estimates will come to fruition.

    A bit more on the Treasury Wine share price

    The Treasury Wine share price is down more than 14% this year to date and had collapsed more than 15% over the past month.

    Although, in the past year of trading, shares have held gains and are up 5% in that time – more than can be said for many other ASX names at the moment.

    At the time of writing, the company has a market capitalisation of $7.6 billion and trades on a price to earnings (P/E) ratio of approximately 30.5x.

    The post The Treasury Wine (ASX:TWE) share price has plunged 25% from its 2021 highs. What’s next? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Treasury Wine Estates right now?

    Before you consider Treasury Wine Estates, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Treasury Wine Estates wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Treasury Wine Estates Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/q3WRxdLIP

  • Why is the NextDC (ASX:NXT) share price climbing today?

    a group of three cybersecurity experts stand with satisfied looks on their faces with one holding a laptop computer while he group stands in front of a large bank of computers and electronic equipment.a group of three cybersecurity experts stand with satisfied looks on their faces with one holding a laptop computer while he group stands in front of a large bank of computers and electronic equipment.a group of three cybersecurity experts stand with satisfied looks on their faces with one holding a laptop computer while he group stands in front of a large bank of computers and electronic equipment.

    Shares in ASX 100-listed technology company NextDC Limited (ASX: NXT) are rallying after dropping from the open today following a company announcement.

    At the time of writing, NextDC shares are fetching $10.63 apiece, up 2.36%, after hitting a low of $10.15 early in the session.

    It’s a welcome sign for the data centre-as-a-service company which has seen its shares slip more than 19% year to date amid a tech-heavy selloff across the ASX.

    The broader S&P/ASX All Technology Index (ASX: XTX) is also having a better start to the trading week, up 2.45% at the time of writing.

    Let’s have a look at NextDC’s latest news.

    What did NextDC announce?

    This morning, the company advised that “following recent customer wins”, it has secured an increase in contracted utilisation for the 6 months ending 31 January 2022.

    According to the company’s announcement, specifically-contracted utilisation (excluding expansion options and reservations) has increased by approximately 5.5MW since 30 June 2021 to roughly 81MW at 31 January 2022.

    NextDC says it will book sales for “most of the new contracted capacity” from next year. As such, revenue is expected to be recognised from FY23 “following completion and commissioning of the associated data halls”.

    The company has been building on momentum in contracted utilisation for some time. For instance, in its FY21 results, it announced that contracted utilisation increased 5.5MW, or 8%, to 75.5MW, while “interconnections” accounted for 7.7% of recurring revenue.

    At the time, NextDC also advised that approximately 80% of built capacity was contracted at 30 June 2021, whilst 87% of contracted utilisation was billing at the same time.

    Back then, in August 2021, the company said it had “significant expansion potential with total planned capacity of 400MW”. This excluded Sydney’s “target capacity of around 300MW announced 28 July 2021”.

    It had guided capital expenditures of $480-$540 million for FY22, focused mainly on building key expansion networks in Melbourne and Sydney (M3 and S3/4 respectively).

    NextDC’s CEO and Managing Director Craig Scroggie said the company’s “sales pipeline remains robust”:

    The demand for our premium data centre services remains strong and we are pleased to have secured these new material customer commitments, including new hyperscale orders, across our national network of world class facilities.

    Furthermore, the sales pipeline remains robust, with the Company seeing the strong sales momentum carry forward into the second half of FY22.

    NextDC is also prioritised securing and developing new contracted capacity. That, in turn, will generate “annuity-style economic returns”, according to Scroggie.

    “We remain on track to bring our third generation hyperscale data centre campuses, M3 and S3, into service at the end of FY22, further expanding our muti-site, multi-zone availability solutions for customers”.

    NextDC share price summary

    The NextDC share price is already down 19% this year to date after sliding 19.63% in the past month. The selloff in ASX tech shares has been brutal so far this year and the company isn’t immune.

    As such, over the last 12 months, shares are down more than 10% after trading as high as $14.04 in September last year.

    The post Why is the NextDC (ASX:NXT) share price climbing today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in NextDC right now?

    Before you consider NextDC, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and NextDC wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/Q0pthTgSv

  • Why the Airtasker (ASX:ART) share price is rocketing 17% higher today

    Key points

    • Airtasker’s growth accelerated in the second quarter
    • Strong demand experienced as lockdowns eased
    • Management has upgraded its second half guidance

    The Airtasker Ltd (ASX: ART) share price has been on fire on Monday morning following the release of its second quarter update.

    At the time of writing, the online local services marketplace provider’s shares are up 17% to 75 cents.

    Airtasker share price rockets on Q2 update

    • Gross marketplace volume (GMV) up 39% quarter on quarter to $48.6 million
    • Record weekly GMV run rate of $4.5 million achieved in December
    • UK GMV up 121% over the prior corresponding period and US posted task growth of 71% quarter on quarter
    • Second quarter revenue up 37.5% quarter on quarter to $8.1 million
    • Second half GMV guidance upgraded to $107 million to $110 million

    What happened during the quarter?

    Airtasker had a strong second quarter, with GMV increasing 39% quarter on quarter to $48.6 million after the easing of lockdowns. Management notes that year on year customer acquisition rose 2.1% in October, 6.6% in November, and then 8.9% in December. This was complemented by a 24% increase in quarterly average task price over the prior corresponding period to $255.

    In light of this strong quarter, management has upgraded its GMV guidance for the second half from $105 million to between $107 million and $110 million. This will represent full year GMV of $191 million to $194 million, which will be an increase of 25% to 27% over FY 2021’s GMV of $153.1 million.

    Management commentary

    Airtasker’s Co-Founder and CEO, Tim Fung, was pleased with the quarter.

    He said: “The strong performance this quarter demonstrates the robust and resilient underlying growth of the Airtasker marketplace. Based on our current growth trajectory, a clear outlook on no further lockdowns and an exciting product and marketing roadmap – we’re super pleased to be upgrading our H2 guidance for FY22.”

    The post Why the Airtasker (ASX:ART) share price is rocketing 17% higher today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Airtasker right now?

    Before you consider Airtasker, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Airtasker wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended Airtasker Limited. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/cm2j8nNXQ