Category: Stock Market

  • Why 2022 could be a strong year for the Woodside (ASX:WPL) share price: Saxo Markets

    A Woodside worker assesses productivity at an oil rig

    Key points

    • The Woodside share price is closely linked to the price of energy
    • Saxo analysts forecast that crude oil prices are likely to rise in 2022
    • EVs won’t derail combustion engine vehicles for a number of years yet

    The Woodside Petroleum Limited (ASX: WPL) share price is off to a strong start in the new year.

    Since trading started on 4 January, Woodside shares have gained 10%. That’s in stark contrast to the broader S&P/ASX 200 Index (ASX: XJO), which is down 6% so far in 2022.

    But even with a few strong weeks behind it, the Woodside share price could deliver more outsized gains in the year ahead, according to analysts at Saxo Bank.

    Energy prices likely to remain elevated

    Today, online trading and investment specialist Saxo Bank released its Q1 2022 Quarterly Outlook for global markets.

    Drilling into what investors can expect for oil prices was Peter Garnry, Saxo’s head of equity strategy.

    Garnry said that investment in the energy sector has been starved of vital new investments, “since the oil price plunge of 2014 to 2016 and subsequently, climate change awareness, coupled with ESG mandates and huge returns in stocks with exposure to digitalisation”.

    According to Garnry:

    The current level of capital expenditures is the lowest in 20 years in real terms and the lowest since 2004 in nominal terms. The investment drought that has lasted for more than seven years will set the stage for very attractive energy prices in the years to come.

    As for EVs moving in to replace petrol cars, Garnry doesn’t see that happening in the short to mid-term:

    The biggest consumer of oil is the transportation sector, and as it is getting electrified the oil market is potentially the biggest long-term loser from the green transformation. But before we get there, the sector will experience another very profitable period during the energy crisis years.

    Indeed, Saxo’s technical analysts believe Brent crude could trade between US$107 and US$115 per barrel in the year ahead. They point to Brent needing to surmount “strong resistance” at US$86.75 per barrel. One barrel of Brent is currently trading for US$88.69 per barrel.

    From a technical analysis angle for crude oil, Saxo adds:

    The underlying trend is up, as illustrated by the 21, 55 and 200 Simple Moving Averages all rising. In addition, a Relative Strength Indicator (RSI) above 60 is also supporting this uptrend.

    Woodside “a stock to watch”

    Woodside may have smashed the ASX 200 so far in 2022, but that doesn’t mean its strong run is over.

    Saxo’s Australian market strategist, Jess Amir, points to the likely rise in crude prices as helping support the Woodside share price. “Oil and oil stocks will also likely continue to dominate, given oil is likely to rise from the US$80s to US$100 amid rising demand as the world’s winters and summers become more extreme.”

    According to Amir:

    Woodside Petroleum is a stock to watch, as it’s set to become the world’s 10th biggest oil and gas producer, following the merger with BHP’s [BHP Group Ltd (ASX: BHP)] petrol business in Q2. Woodside produces 20 percent of Australian gas, competing with Chevron, Santos (ASX: STO), ExxonMobil and Shell.

    Woodside share price snapshot

    Although it’s kicked off 2022 strongly, the Woodside share price remains down 5% over the past 12 month. By comparison the ASX 200 is up 5% during that same time.

    The post Why 2022 could be a strong year for the Woodside (ASX:WPL) share price: Saxo Markets appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Woodside right now?

    Before you consider Woodside, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Woodside wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3Iyi1iz
  • Two top ASX 200 mining shares to watch in 2022: Saxo Markets

    Two miners standing together with a smile on their faces.

    Key points

    • These 2 ASX 200 miners have trounced the index in 2022
    • A strong outlook for iron ore could see more gains ahead
    • Saxo Bank Australian market strategist, Jess Amir on the strengthening commodity sector

    The S&P/ASX 200 Index (ASX: XJO) has been struggling in the new year.

    Since the opening bell on 4 January, the ASX 200 is down 5.9%.

    But not every share on the index has lost ground.

    The BHP Group Ltd (ASX: BHP) share price has gained 6.6% so far in 2022.

    And fellow ASX 200 mining giant Rio Tinto Limited (ASX: RIO) shares have gained 8%.

    While those share price gains are in the rear view now, Saxo Bank’s Australian market strategist, Jess Amir, says investors would do well to keep an eye on both companies in the year ahead.

    Iron ore strength could boost ASX 200 miners

    Online trading and investment specialist Saxo Bank’s Q1 2022 Quarterly Outlook for global markets was released today.

    Writing in that update, Amir singled out a number of ASX 200 shares that look well positioned to outperform over the coming quarters.

    With iron ore prices moving higher once more, both BHP and Rio figure prominently among those.

    Noting that iron ore is trading back at US$129 per tonne, its highest level since October and up 40% since the November lows, Amir said this is “exciting for investors in BHP and Rio as it boosts their profitability”.

    Pointing to positive developments in China, including China’s announcement this year of some US$471 billion in major new infrastructure projects, Amir said “iron ore could claw out of its bear market and head back to the $220 mark, where it traded in May 2021”.

    And that would spell good news for ASX 200 miner BHP.

    According to Amir:

    The biggest catalyst for the BHP share price is a rise in the iron ore price. In 2021, BHP made 58% of its revenue from iron ore, 26% from copper, 9% from coal and 7% from petroleum. BHP’s coal and petrol revenue is being boosted by record prices, but remember that this will reduce after BHP divests oil assets this year, followed by coal in 15 months’ time.

    As for the critical demand for iron ore from China, Amir said, “BHP sees iron ore demand picking up, expecting China’s GDP to grow by up to 6% this year.”

    Atop its iron ore production, BHP is also pitching in with the world’s efforts to decarbonise, “supplying copper, nickel and potash”.

    The BHP share price currently stands at $45.30. Will it be able to get back to its August 2021 high of $54?

    “Many think it can,” said Amir.

    What about Rio Tinto?

    As for Rio Tinto, Amir says this is another stock for ASX 200 investors to watch in the year ahead:

    Rio shares rocketed up 20% from $88.56 in November to $106.41. Can it get back to the $135 high it hit in July 2021? The jury doesn’t think so, as it’s been facing a backlash about potentially building a $3 billion lithium mine in Serbia. Either way, tailwinds supporting Rio’s share price growth come from the way it’s currently generating revenue.

    But the market seems to have mispriced that. In 2021, 56% of revenue was from iron ore, 23% from aluminium, 11% from copper and diamonds, and 10% from energy; all commodity prices are moving up.

    The post Two top ASX 200 mining shares to watch in 2022: Saxo Markets appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP right now?

    Before you consider BHP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3tX5Gka

  • The Critical Resources (ASX:CRR) share price is diving 10% today. Here’s why

    Man in business suit above the clouds plummeting downwards back firstMan in business suit above the clouds plummeting downwards back firstMan in business suit above the clouds plummeting downwards back first

    Key points

    • The Critical Resources share price has plunged 10% lower to trade at 9.9 cents this morning
    • Its dip follows the release of its quarterly activities and cash flow report
    • Over the quarter ended 31 December, the company underwent acquisition, exploration, and capital raising activities

    The Critical Resources Ltd (ASX: CRR) share price is suffering this morning after the company published its quarterly activities and cash flow report. Unfortunately, the market is reacting poorly to its release.

    At the time of writing, the Critical Resources share price is 9.9 cents, 10% lower than its previous close.

    Let’s take a look at what the base metal and lithium explorer and developer got up to during the quarter just been.

    Critical Resources share price tumbles 10% on quarterly report

    The quarter ended 31 December was a big one for Critical Resources, and while the company’s quarterly report is seemingly positive, the market is bidding the company’s share price down today.

    During the period, the company began drilling at its Halls Peak base metal project in New South Wales. There, it uncovered massive sulphide mineralisation and high-grade zinc, copper, and silver assays.

    It has now applied for another 839 square kilometres of tenements around the project’s tenements.

    The company also paid a non-refundable fee of $200,000 for 90 days of exclusive acquisition talks regarding the Mavis Lake lithium project in Ontario, Canada. It finalised the purchase of the project after the quarter’s end.

    Finally, at its Sohar Copper Project – located in Oman – Critical Resources continued its talks with the Oman government.

    According to the company, it was asked to pay ground fees it considers “onerous and unreasonable” for the project’s Block 4 licence earlier in 2021. It plans to update the market on the outcome of talks in due course.

    Additionally, the company underwent a $4 million placement last quarter. Its shares were offered at 2.9 cents apiece as part of the capital raise, with the resulting funds going towards the Mavis Project’s acquisition and exploration at Halls Peak.

    As of 31 December, the company had $4.75 million of cash in the bank.

    The Critical Resources share price’s latest tumble follows yesterday’s 8.3% slump. This came on the same day the company advised it had staked 700 hectares of additional claims around its Graphic Lake project, located about 180km from its Mavis Lake lithium project in Canada. Its shares also fell 14.2% on Friday.

    However, the company’s stock is still swapping hands for around 150% more than it was at the end of 2021.

    The post The Critical Resources (ASX:CRR) share price is diving 10% today. Here’s why appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Critical Resources right now?

    Before you consider Critical Resources, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Critical Resources wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3AsNXlN

  • Codan (ASX:CDA) share price rockets 16% on trading update

    A drawing of a rocket follows a chart up, indicating share price lift

    Key Points

    • Codan shares accelerate on back of a positive trading update
    • Sales surge despite tough trading conditions
    • Record net profit after tax expected for H1 FY22

    The Codan Limited (ASX: CDA) share price is zooming into positive territory during morning trade. This comes after the company announced a trading update for the first-half of FY22.

    At the time of writing, the metal detector-focused technology company’s shares are fetching for $9.75, up 16.49%.

    Codan on track for ‘record profit’

    Investors are buying up Codan shares after the company advised of a robust performance for the half-year ended on 31 December.

    The company highlighted that it finished the 6-month period on a high note, with sales coming in at $257 million. This represents a 32% improvement when compared against the prior corresponding period.

    Supporting growth, recently acquired businesses, DTC and Zetron, both exceeded first-half profit expectations by management.

    Zetron manufactures mission-critical communication technologies. Products include voice dispatch, emergency call taking including next generation 911 (NG911), mapping, computer aided dispatch and fire station alerting.

    On the other hand, DTC provides short-range high bandwidth communications suitable for the wireless transmission of video and other data applications. Customers include Military and Special Forces, Intelligence Agencies, Border Control and First Responders.

    As a result of the strong trading performance, net profit after tax (NPAT) is forecasted to be around $50 million. If achieved, this will reflect a 21% increase on H1 FY21.

    Codan stated that despite the global shortages of electronic components and supply chain disruptions, it has successfully maintained operations.

    In addition, the group has increased inventory levels which will most likely act as a precautionary measure.

    The company plans to release the first-half FY22 performance and outlook for the second-half FY22 on 17 February.

    About the Codan share price

    Codan designs and manufactures a range of electronic products and software for governments, businesses, aid & humanitarians, as well as customer markets. The company’s three main products are radio communication, metal detection, and tracking solutions.

    Despite today’s eutrophic rise, it has been a disappointing 12 months for Codan investors, with the company’s shares falling 22%.

    Based on today’s price, Codan presides a market capitalisation of roughly $1.76 billion, with approximately 180.88 million shares outstanding.

    The post Codan (ASX:CDA) share price rockets 16% on trading update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Codan right now?

    Before you consider Codan, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Codan wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3fVCkuc

  • Are ASX consumer staples shares really ‘safe’ to hold in a market selloff?

    a woman leans on her shopping trolley as she rests her chin in her hand as if thinking as she stands in the middle of a grocery supermarket shopping aisle with a serious look on her face.

    Key points

    • Consumer staples shares are often referred to as ‘safe’ shares
    • But just how safe are they?
    • Let’s crunch some numbers and see how they’ve performed recently

    When it comes to investing, a popular opinion that you might come across (especially in times like these) is that consumer staples shares are ‘safe’ investments to hold during a market correction or crash.

    If you weren’t aware, a consumer staples company is one whose primary business is producing food, drinks, alcohol, tobacco, or household essentials such as laundry powder, dishwashing detergent, or razor blades. If you can’t live (or live in a modern way) without it, chances are it’s a consumer staples product.

    So you can see why some investors would regard a company that is in the business of supplying these kinds of products might be viewed as safe or recession-proof. No matter how bad the economy might get, we all still need to eat, drink, and clean our houses. Many of us would be loath to give up our vices as well.

    So here on the ASX, most of our consumer staples companies are middlemen. Think Woolworths Group Ltd (ASX: WOW) or Coles Group Ltd (ASX: COL). Although these companies don’t technically produce most of the products they sell themselves, they still participate in the consumer staples value chain.

    So let’s see how these companies have performed over the past month or so. As most investors would be aware, the past few weeks have been brutal for many ASX investors, with the S&P/ASX 200 Index (ASX: XJO) losing approximately 7.15% year to date in 2022.

    Have ASX consumer staples shares protected their owners from the market selloff?

    Well, if we take the Woolworths share price, we might be able to get some idea as to how consumer staples shares have performed in a period of market turmoil like we have seen recently.

    Since the start of the year, the Woolworths share price has gone from $38.47 to the $34.51. That’s a fall of 10.3% — a performance that handily trails the broader market. What about Coles ? Well, it’s down by very similar amount — 9.9% at the time of writing.

    So it’s not looking too good for consumer staples shares thus far.

    Let’s take a few more consumer staples shares. There’s Treasury Wine Estates Ltd (ASX: TWE) and Metcash Limited (ASX: MTS). Treasury shares have lost 12.25% since the start of 2022, while Metcash is down 7.5% over the same period. Again, all ASX 200 underperformance.

    So, all in all, it seems that ASX consumer staples shares have not delivered their investors any protection from the selloff we have seen on the share market over the year so far. In fact, all of the big consumer staples shares we have discussed today have been crushed by the market during this downturn.

    Let’s be clear, there’s nothing wrong with consumer staples shares. But the evidence here clearly shows that they are not immune to underperforming the market in a downturn. It just goes to show that, as Mark Twain once said, ‘what gets us into trouble is not what we don’t know. It’s what we know for sure that just ain’t so’.

    The post Are ASX consumer staples shares really ‘safe’ to hold in a market selloff? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Woolworths right now?

    Before you consider Woolworths, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Woolworths wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended COLESGROUP DEF SET. The Motley Fool Australia has recommended Treasury Wine Estates Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3tTQIv9

  • Why is the Sezzle (ASX:SZL) share price rocketing 20% higher?

    Key points

    • Sezzle shares are rocketing after confirming takeover talks with Zip
    • Zip is looking to acquire Sezzle but talks are at a preliminary stage
    • No financial details have been provided to the market

    The Sezzle Inc (ASX: SZL) share price is having its best day in a long time on Tuesday.

    In late morning trade, the buy now pay later (BNPL) provider’s shares are up 20% to $2.57.

    Why is the Sezzle share price shooting higher?

    The catalyst for the rise in the Sezzle share price on Tuesday has been news that the company is a takeover target.

    According to the release, Sezzle has confirmed that it is in discussions with larger rival Zip Co Ltd (ASX: Z1P). However, it has warned that talks are at an early stage and there’s no guarantee that a transaction will materialise.

    The company commented: “Sezzle confirms that it is currently engaged in preliminary discussions with Zip regarding a possible merger. No definitive agreement has been reached between the parties in relation to any transaction. There is no certainty at this time that these discussions will result in a transaction.”

    Zip also responded to the speculation by confirming the talks. It said: “Zip confirms it is in discussions with Sezzle in relation to a potential acquisition. Zip is always interested in pursuing options that are in the best interests of shareholders.”

    What price will Zip pay for Sezzle?

    Neither party has provided any indication of the proposed terms of the deal. However, The Australian has suggested that Zip would be required to pay a 50% premium to the Sezzle share price at the close of play on Monday.

    That would mean a price of approximately $3.21 per share, which values Sezzle at a little under $600 million. While this is a far cry from Sezzle’s 52-week high of $11.99, a lot has changed in the sector in respect to valuations since its shares were trading at that level.

    The post Why is the Sezzle (ASX:SZL) share price rocketing 20% higher? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Zip right now?

    Before you consider Zip, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Zip wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ZIPCOLTD FPO. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3qUUNgI

  • Novonix (ASX:NVX) share price drops 6% amid agreement with US battery cell developer

    Key points

    • The Novonix share price is down 5.95%%
    • The lithium-ion battery materials developer plans to acquire 5% of US-based Kore Power
    • The agreement is subject to board approval

    The Novonix Ltd (ASX: NVX) share price is sliding today amid the company releasing plans to acquire 5% of US battery cell developer Kore Power.

    The battery materials company’s shares are currently trading at $7.75 apiece, a fall of 5.95%. The company’s share price has been on the slide since market open. For perspective, the broader S&P/ASX 200 Index (ASX: XJO) is down 1.58% at the time of writing.

    Let’s take a look at what the company announced today.

    New agreement

    Novonix informed investors it intends to acquire a 5% stake in Kore Power Inc. Kore Power is a battery cell developer for the clean energy industry based in the US state of Idaho. The agreement will depend on board approval from both companies.

    Novonix is a developer of materials for the global lithium-ion battery industry. The company said it has executed a letter of intent on the proposed investment to strengthen its North American battery supply chain.

    Under the agreement, Novonix would become the exclusive supplier of graphite anode materials to Kore’s battery cell manufacturing facility in the US.

    Commenting on the agreement, Novonix co-founder and CEO Dr Chris Burns said:

    Novonix and Kore Power have been actively working together to improve battery technology utilising Novonix’s proprietary cell testing technologies, and these agreements deepen our longstanding collaboration.

    We are reducing the reliance on foreign materials and furthering the United States’ position as a global energy storage leader by providing high capacity long-life synthetic graphite anode material to a leading domestic developer.

    If the proposal goes ahead, Novonix would purchase 3,333,333 Kore Power shares at $7.50 per share.

    Novonix revealed in January it has commenced the process for a secondary listing on the Nasdaq stock exchange. The company has also filed a registration statement with the US Securities and Exchange Commission.

    The company’s share price had a boost in December on news the company had been added to the S&P/ASX 200 Index.

    Share price recap

    The Novonix share price has skyrocketed 124% in the past year. However, it’s dropped around 6% in the past month and is down 16% in the past week alone.

    In contrast, the broader ASX 200 Index has returned nearly 3% in the past 52 weeks.

    Novonix has a market capitalisation of $3.9 billion based on its current share price.

    The post Novonix (ASX:NVX) share price drops 6% amid agreement with US battery cell developer appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Novonix right now?

    Before you consider Novonix, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Novonix wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3qZr9ag

  • This crypto will be the Ethereum of 2022

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Several cryptocurrencies are emerging to take on the king of the hill, Bitcoin (CRYPTO: BTC). Ethereum‘s (CRYPTO: ETH) trading price rose 408% in 2021. Investors like Ethereum as a viable competitor to Bitcoin because of its faster transaction speeds and its large ecosystem of decentralised applications (dApps), which are programs that run on blockchains. 

    But there is another up-and-coming crypto starting to show promise. NEAR Protocol (CRYPTO: NEAR) rose 984% last year. This layer-one blockchain offers similar benefits in transaction speeds and utility value as Ethereum, but with much greater upside potential. Let’s check it out.

    NEAR’s upside is huge

    The entire crypto market is currently worth just over $1.5 trillion. If you’re looking for a relatively safe but strong performer that can multiply your original investment, I would look at smaller blockchains that are seeing price momentum supported by a growing developer community.

    NEAR currently has a market cap of $6.2 billion. It could rise 42-fold in value, and it would still only match Ethereum’s current market cap of $268 billion. 

    On the other hand, if Ethereum increased 42 times in value, it would command a market cap of over $11 trillion, which is not likely to happen anytime soon.

    Supporting the upside case for NEAR are some key developments in the past year that are starting to attract investor interest.

    Recent developments 

    It can take six minutes to finalize a transaction on the Ethereum blockchain, but NEAR can currently process up to 1,000 transactions per second and has the potential to reach 100,000 per second. 

    NEAR uses a technology called sharding, which fundamentally makes it faster than Ethereum. With Ethereum, every transaction must be processed through every node in the network, which slows it down. But with sharding, the work is split among different nodes, so transactions can be processed much faster.

    The NEAR Foundation says the rollout of its Simple Nightshade sharding mechanism will make its blockchain “super-fast, incredibly secure, and capable of onboarding millions of users into the world of Web3 without skipping a beat.” 

    In the same announcement, NEAR disclosed that only 13% of the network was being used in mid-November of 2021, but the NEAR team said that the average number of daily transactions had risen to more than 300,000, with “more and more projects building” on the blockchain. Prices of cryptocurrencies tend to follow growth in developer projects, so this is a strong indicator of where NEAR might be heading.

    NEAR has one of the fastest-growing developer communities, and that’s being validated by a rising value in the market. I believe it’s a promising cryptocurrency to buy with higher upside than Ethereum in 2022.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post This crypto will be the Ethereum of 2022 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of January 12th 2022

    More reading

    John Ballard owns Bitcoin. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Bitcoin and Ethereum. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.


    from The Motley Fool Australia https://ift.tt/3ICMlIL
  • Apple stock before earnings: Sell or Buy?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Man sits at computer and analyses stock graphic

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

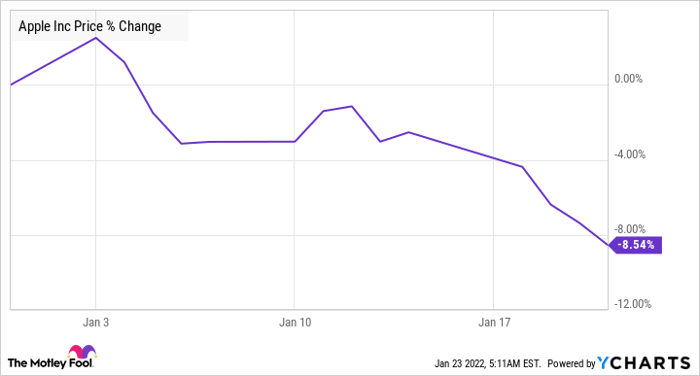
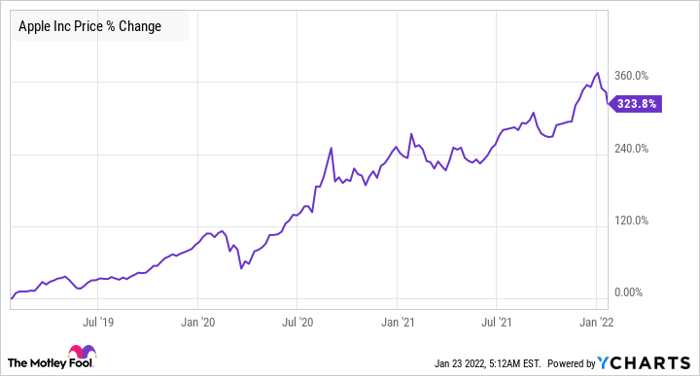
    Apple (NASDAQ: AAPL) is set to release its fiscal 2022 first-quarter results after the market closes on Thursday, Jan. 27, and investors would be hoping for a solid performance from the company to arrest the stock’s slide.

    Shares of Apple have been going downhill in 2022 due to the sell-off in tech stocks, which has been triggered by the Federal Reserve’s hawkish stance that could result in as many as four interest rate hikes in 2022 to keep inflation under control.

    AAPL Chart

    AAPL data by YCharts.

    Reasons to sell

    Apple CEO Tim Cook had pointed out on the October 2021 earnings conference call that the company lost an estimated $6 billion in revenue in the fourth quarter of fiscal 2021, driven by “industrywide silicon shortages and COVID-related manufacturing disruptions.” Cook had added that “the impact from supply constraints will be larger during the December quarter.”

    Apple had declined to issue revenue guidance for Q1 because of the supply chain problems, so it remains to be seen how its results stack up against Wall Street’s expectations. Analysts expect Apple’s revenue to increase just 6% year over year in the fiscal first quarter to $118.4 billion. The company had recorded a 21% year-over-year increase in revenue in the same quarter last year to $111.4 billion and finished fiscal 2021 with a 33% spike in full-year revenue to $365.8 billion.

    Higher rates encourage investors to shift their money from high-risk companies to relatively safer investments such as bonds. Additionally, higher interest rates increase borrowing costs that could hurt the bottom line, which is something investors don’t want to see in richly valued stocks.

    Throw in the fact that Apple was suffering from supply chain problems during the holiday season, and the odds seem to be stacked against the iPhone maker when it releases its results. Does this mean that investors should start selling Apple stock before its earnings report? Or should they take advantage of the dip and buy more? Let’s find out.

    The company’s earnings, on the other hand, are expected to increase only 12% year over year during the quarter. For comparison, Apple had clocked a 71% increase in adjusted earnings in fiscal 2021 to $5.61 per share.

    What’s more worrying is that Apple’s growth could slow down meaningfully this fiscal year. Analysts are expecting just 4.5% revenue growth in fiscal 2022 to $382.3 billion, while earnings are expected to increase just 2.3% to $5.74 per share. The potential interest rate hikes could add to the gloom and keep Apple from repeating its stellar stock market performance of the past three years.

    AAPL Chart

    AAPL data by YCharts

    So, there are quite a few reasons why investors may want to sell Apple stock before its earnings report. However, savvy investors should focus on the bigger picture as the company could spring a surprise, both in the short and in the long run.

    Reasons to buy Apple stock

    It would be a bad idea to write off Apple given the way it is dominating the 5G smartphone market. Strategy Analytics reports that Apple has been the top 5G smartphone vendor ever since it launched its first 5G-enabled device in the fourth quarter of 2020. More specifically, Apple controlled 26% of the 5G smartphone market in the third quarter of 2021, and it is unlikely that it would be giving up the pole position any time soon.

    That’s because Apple has a huge installed base of users in an upgrade window that are waiting to get their hands on a 5G iPhone. Wedbush Securities analyst Daniel Ives estimates that around 230 million iPhone users haven’t upgraded their phones in the past three and a half years, which means that Apple’s sales can start picking up once its supply chain problems are sorted.

    The good part is that Wall Street sees an improvement in Apple’s supply chain. Wells Fargo analysts have raised their price target on Apple stock to $205, which points toward a 26% potential upside from Friday’s close. Analyst Aaron Rakers says that a combination of supply chain improvements and robust demand for Apple’s products could help it sustain its growth momentum.

    CFRA Research also maintains a similar view, stating that supply constraints are likely to ease in the first half of the year and Apple is on track to gain market share in markets such as China. Not surprisingly, analysts believe that the tech giant could outperform expectations. Katy Huberty of Morgan Stanley estimates that Apple sold 83 million iPhones last quarter and outperformed expectations of 80 million units.

    Additionally, Apple is expected to sell 55 million iPhones in the current quarter as per Huberty, which would land ahead of the market’s expectations. So, Apple could exceed expectations when it releases its earnings report, and that could help the stock regain its mojo. More importantly, the tech stock could sustain its momentum in the future as well since it is sitting on several mouthwatering catalysts.

    In all, a strong report and a robust outlook could send the stock soaring and make it more expensive. That’s why investors can consider buying Apple’s dip heading into its quarterly report as it is trading at 29 times trailing earnings now, a small discount to the 31.6 times earnings it was trading at last year. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Apple stock before earnings: Sell or Buy? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Apple right now?

    Before you consider Apple, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Apple wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Harsh Chauhan has no position in any of the stocks mentioned. Wells Fargo is an advertising partner of The Ascent, a Motley Fool company. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and recommends Apple. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. recommends the following options: long March 2023 $120 calls on Apple and short March 2023 $130 calls on Apple. The Motley Fool Australia has recommended Apple. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3FXzHCw

  • What’s going on with the St Barbara (ASX:SBM) share price today?

    Older mine worker in hard hat looks upsetOlder mine worker in hard hat looks upsetOlder mine worker in hard hat looks upset

    Key Points

    • St Barbara shares are in the red following the release of the comany’s Q2 FY22 trading update
    • Production levels slightly dropped due to lower grades at its Leonora operation
    • FY22 guidance is on track of up to 335koz at ASIC $1,815 per ounce

    The St Barbara Ltd (ASX: SBM) share price has dipped in morning trade amid the company providing a trading update for its second quarter.

    At the time of writing, the gold miner’s shares are at $1.355 apiece, a drop of 1.45%.

    How did St Barbara perform in Q2 FY22?

    The St Barbara share price has edged lower as investors digest the company’s latest performance report.

    For the three-month period ending 31 December, St Barbara produced 65,523 ounces of gold at an all-in sustaining cost of $1,587 per attributable ounce. Although production dropped at Leonora in the second quarter, this was largely offset by higher feed grades at Atlantic. In comparison, production levels in the prior period came to 67,000 ounces.

    Operating cashflow came in at $49 million for the period. However, after growth capital, corporate costs, and tax payments, net cash contribution stood at $3 million.

    St Barbara sold 76,000 ounces of gold at an average price of $2,423 per ounce.

    The gold miner recorded a robust balance sheet with cash on hand of $94 million, up from $42 million on 30 September. Total debts included a syndicated facility of C$80 million (A$88.61 million) and $50 million which was recently drawn down.

    Management noted that the pandemic is causing issues sourcing required labour and equipment for the Atlantic and Simberi operations. A tightening of the labour market in Western Australia as a result of border closures is also hampering the company’s efforts.

    Nonetheless, a contingency plan has been developed to minimise any potential interruptions if the Western Australian border opens.

    What did the head of St Barbara say?

    St Barbara managing director and CEO Craig Jetson commented:

    The end of the December FY22 quarter marks a momentous period for St Barbara.

    Through the announcement of our acquisition of Bardoc Gold, we took decisive steps towards securing Leonora’s future as a significant processing hub in the Western Australian goldfields. The acquisition uniquely positions St Barbara to add value to the high quality Bardoc ore bodies by processing the ore at the Leonora processing plant.

    We also had some very encouraging drilling results in the Old South Gwalia ore body, which has the potential to add new mining fronts higher up in the mine. By the end of this financial year, we are targeting an updated Mineral Resource for this area.

    FY22 outlook

    Looking ahead for the full year, St Barbara is expecting FY22 to be broadly in line with previous expectations.

    The miner is forecasting consolidated gold production of between 305,000 ounces and 335,000 ounces. This is assumed at an AISC (all-in sustaining cost) of between $1,650 and $1,815 per ounce.

    St Barbara is scheduled to release its half-year results to the market on 23 February.

    About the St Barbara share price

    Over the past 12 months, St Barbara shares have plummeted around 40%, with year-to-date performance also sinking 7%. The company’s share price reached a 52-week high of $2.36 in February last year before treading on a downward path.

    Based on today’s price, St Barbara commands a market capitalisation of roughly $964 million, with approximately 709 million shares outstanding.

    The post What’s going on with the St Barbara (ASX:SBM) share price today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in St Barbara right now?

    Before you consider St Barbara, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and St Barbara wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of January 13th 2022

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3tWDEoA