Category: Stock Market

  • This cryptocurrency could 10x by 2026

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.
    a business person in a suit and tie directs a pointed finger upwards with a graphic of a rising bar graph and an arrow heading upwards in line with the person's finger.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    I’m sure by now you’ve heard about the outrageous returns that the cryptocurrency market has produced. In 2021, the total value of these digital assets roughly tripled, and the entire market is worth just over $2 trillion today. 

    Bitcoin (CRYPTO: BTC), the world’s most valuable cryptocurrency, finished 2021 up 61% on the year. But there could still be massive gains ahead. Even ARK Investment Management’s CEO, Cathie Wood, thinks Bitcoin, which was priced around $43,000 as of Jan. 6, will eclipse the $500,000 mark in 2026. 

    Let’s dive into what needs to happen for the top cryptocurrency to rise tenfold over the next five years. 

    Bitcoin becomes “digital gold” 

    The current value of all the gold in the world is a little over $9 trillion. Based on Bitcoin’s market cap of approximately $800 billion, if the cryptocurrency ever truly becomes what many investors and speculators think of it as — a “digital gold” — then it’s not difficult to believe that its value could approach the precious metal’s. Both possess scarcity, as there is only a finite amount of gold in the earth’s crust and there will only be 21 million bitcoins mined. Bitcoin can’t be used in electronics or worn as jewelry, but it can be easily owned or transferred. For “digital gold” proponents seeking an effective store of value, Bitcoin could be the answer. 

    According to Cathie Wood, if institutional investors allocate 5% of their portfolios to Bitcoin, then it could reach $500,000 in value. The likelihood of this happening is anyone’s guess, and it will certainly depend on its volatility decreasing significantly, but there are signs that point to increased investor interest. 

    There are already numerous Bitcoin exchange-traded funds available. And investment bank Goldman Sachs even has a trading desk dedicated to Bitcoin. These developments reduce the friction to get institutions on board. The appeal of owning Bitcoin, or any cryptocurrency for that matter, is that it’s not correlated to other financial assets. As a result, it can add a level of diversification to portfolios. 

    Then there’s the possibility of corporations moving a portion of any cash on their balance sheets into Bitcoin, like what Block, MicroStrategy, and Tesla have already done. If this trend continues, it will definitely provide support for Bitcoin’s price appreciation in the years ahead. 

    Bitcoin’s utility rises 

    Another argument for why Bitcoin can soar tenfold by 2026 is that its utility could increase. While we in the U.S. might take our advanced payments system and financial services for granted, citizens of developing countries have a different perspective.

    El Salvador is the perfect example of how useful Bitcoin can be. Remittances make up a quarter of its gross domestic product, but sending money back home incurs an average fee of close to 3% per transaction. Bitcoin offers low fees (or none) to send payments across borders, meaning hundreds of millions of dollars can be released to immediately improve the livelihood of people in El Salvador. The Central American nation also recently made the cryptocurrency legal tender, a model other countries could soon follow. 

    Jack Dorsey, CEO of Block, views Bitcoin as the most important thing to work on during his lifetime. His company has two initiatives, TBD and Spiral, that aim to build the tools and infrastructure, such as a decentralized exchange for converting fiat currency to Bitcoin, as well as improved wallet functionality, to meaningfully improve Bitcoin’s user experience.

    And Coinbase Global, the leading crypto brokerage and exchange business in the U.S., operates with the overarching mission to create and propel the crypto economy. Some of the brightest entrepreneurs today are clearly working on bringing crypto to the masses. As the world’s most valuable cryptocurrency, Bitcoin should naturally benefit since it will probably be the general public’s first exposure to the nascent asset class. 

    Over the past five years, Bitcoin has skyrocketed a remarkable 4,800%. A tenfold jump in the next five years equates to a total return of 900%, or 58% on an annualized basis. This is a phenomenal rate of return that will crush the broader stock market. However, it’s still a huge slowdown from Bitcoin’s past performance. 

    There will no doubt be volatility along the way. That’s just the price we must pay in order to achieve great returns. But based on the arguments I’ve laid out above, I think there’s a possibility for Bitcoin to increase tenfold by 2026. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post This cryptocurrency could 10x by 2026 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    Neil Patel owns Bitcoin, Block, Inc., and Coinbase Global, Inc. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and recommends Bitcoin, Block, Inc., Coinbase Global, Inc., and Tesla. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/33jzxYp
  • Here’s why the AGL (ASX:AGL) share price is surging 8% today

    happy miner using a computer at a mine, oil or gas site with rigging in the background.

    Shares in struggling energy giant AGL Energy Limited (ASX: AGL) are back in the money today amid a longer-term uptrend that’s been in situ since November.

    AGL shares are now trading more than 7% higher at $6.74 apiece, after rallying as high as $6.84 early in the session. Let’s take a look.

    What’s driving the AGL share price today?

    Whilst there’s been no price-sensitive information from the company’s end today, the team at Credit Suisse upgraded the firm to outperform in a note to clients, adding another bull to the list of analysts covering AGL.

    That means that each of Credit Suisse, JP Morgan, and one other broker are bullish on the direction of the AGL share price in 2022.

    Credit Suisse values the company at $8.50 per share, whereas JP Morgan reckons AGL should trade at around $7.55.

    Aside from this, the S&P/ASX 200 Energy Index (XEJ) has also nudged past 1.5% today and has climbed around 6% in the past week, indicating strengths in the broad sector.

    Energy markets are regaining steam as we roll into the first quarter of fiscal 22, as the price of natural gas and coal remain stationed near multi-year highs.

    Natural gas has climbed more than 50% in the last year and is up 10% for the month, whereas coal has soared more than 130% and 23% respectively.

    Aside from that, ASX energy shares are positioned on the ‘defensive’ rather than ‘cyclical’, because people will consume energy in all phases of the business cycle.

    Hence, with the recent spike in US Treasury yields that is hurting the valuations on cyclical and high-growth stocks, it appears that investors are reshuffling capital back in favour of defensive names like AGL.

    AGL shares bounced off a low of $5.10 in mid-November and have skyrocketed from January alongside the broad index just as the S&P/ASX All Technology Index (XTX) has tanked over 6% in the same time.

    Hence, the $4 billion company by market cap has now shot past its 3-month highs and is on track to finish the session up today as well.

    AGL share price summary

    In the past 12 months, the AGL share price has fallen more than 44% much to the anguish of shareholders.

    However, with the strengths in recent weeks, it has climbed over 15% in the last month and is up 10% for the past week.

    Yet, over the long-term, AGL has lagged its key benchmarks substantially, even with its 75 cents per share trailing dividend.

    The post Here’s why the AGL (ASX:AGL) share price is surging 8% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in AGL Energy right now?

    Before you consider AGL Energy, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and AGL Energy wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The author has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3GeQ1jf

  • VGI Partners (ASX:VGI) share price climbs 10% amid possible merger

    Two hikers high five each other having climbed to the top of the mountain.

    The VGI Partners Ltd (ASX: VGI) share price is in the green today on the back of merger speculation.

    The company’s share price is currently swapping hands at $5.25, up 10.29% on yesterday’s close.

    Let’s take a look at what is happening at the investment company today.

    Merger speculation

    Investors may be reacting today to speculation in The Australian that VGI Partners may merge or be taken over by one of its competitors.

    The company has asked Jefferies banker Michael Stock to spearhead the potential merger or acquisition, News Corp reported.

    In a statement authorised by company secretary Ian Cameron, VGI Partners acknowledged the media speculation and left the door open to a potential merger.

    VGI confirms that it is having preliminary discussions with a number of parties, including Regal [Regal Investment Fund (ASX: RF1)], in relation to a range of potential transactions.

    VGI is aware of its continuous disclosure obligations to the market and will keep the market informed consistent with those obligations.

    A global funds manager, VGI Partners has offices in Sydney, New York and Tokyo. The company has $2.8 billion worth of funds under its management as of 30 September 2021.

    VGI’s share price has had a tough year, shedding 39% in the past 12 months. Additionally, the VGI share price has dropped 41% from its 12-month high of $8.54 reached on 25 February.

    VGI share price recap

    While the 2021 year was a shocker for VGI Partners shares, the past month is providing relief for investors.

    In the past week, VGI shares have gained 7.8%, while they are up nearly 22% in the past month.

    The company commands a market capitalisation of roughly $332.28 million based on the current share price.

    The post VGI Partners (ASX:VGI) share price climbs 10% amid possible merger appeared first on The Motley Fool Australia.

    Should you invest $1,000 in VGI Partners right now?

    Before you consider VGI Partners , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and VGI Partners wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3JRQvOy

  • Tritium is set to list on the Nasdaq this month, but what about the ASX?

    a headless person holds an electric vehicle charger front on to the campera so its plug points are visible, forming the central focal point for the shot.

    Electric vehicle (EV) fast-charging company Tritium is back in view today as the company gets set for a likely Nasdaq listing this month. Currently, there are no signs of the EV charging player landing on the ASX anytime soon despite Tritium’s headquarters being located in Australia.

    After cementing a record-breaking fourth-quarter result, investors are eagerly awaiting the Brisbane-based company’s listed future. The final stepping stone along the path of a public debut involves a shareholder vote on 12 January.

    Powering towards a Nasdaq listing

    Tritium’s interest in becoming a publicly listed company began back in May last year. During a boom in special purpose acquisition companies (SPACs), the business partnered up with Decarbonization Plus Acquisition Corporation II (NASDAQ: DCRN).

    The two companies have been working on the merger for Tritium to be taken public. After roughly eight months, the final piece of the puzzle is a shareholder vote on the proposed business combination with Tritium.

    According to the company’s release, DCRN shareholders will lodge their votes up until 12 January. On this date, a special meeting will be held with the final outcome of the vote to be announced. If the votes tally in favour of the merger, Tritium is expected to hit the Nasdaq days after the meeting.

    Additionally, Tritium had been tagged with an estimated $2 billion valuation in June last year. Since then, the company has further grown its revenue.

    ASX misses out on Tritium growth

    At present, the world’s second-largest fast-charging company has shared no intentions of appearing on the ASX. Instead, Tritium’s future currently lies solely with the Nasdaq exchange in the United States. This is likely a reflection of the company’s composition of sales.

    Based on its investor presentation, 20% of Tritium’s sales are made in North America. Comparatively, only 10% of the EV charging company’s sales are to the Asia Pacific region. Interestingly, approximately 70% of total sales are in Europe.

    For the three months ended 31 December 2021, Tritium notched up ~US$41 million in revenue. This was a record for the company and represented more than a 2.5 times increase on the prior corresponding period.

    https://platform.twitter.com/widgets.js

    However, as Tritium CEO Jane Hunter noted, the quarter was impacted by supply chain and logistics issues.

    When COVID started, it was 42 days from Australia to Europe by boat, and 35 days to North America from Australia, and we had … a ship that left in September and still has not docked in North America, which is just unheard of.

    Unfortunately for ASX investors, the Tritium growth story has been out of reach, being a private company. Although, with the possibility of it listing on the Nasdaq, investors might soon have access to Tritium on a public exchange.

    The post Tritium is set to list on the Nasdaq this month, but what about the ASX? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Mitchell Lawler has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3f3qEoK

  • Following the Wesfarmers (ASX:WES) API takeover? Here are some key dates to watch out for

    a woman sitting at a desk checks an old fashioned calendar resting against her wall as she sits with documents in front of her.

    It’s been a wild rise for market watchers interested in Wesfarmers Ltd‘s (ASX: WES) takeover of Australian Pharmaceuticals Industries Ltd (ASX: API).

    The company’s bid has been blindsided twice, once by Sigma Healthcare Ltd (ASX: SIG) and another by its retail peer Woolworths Group Ltd (ASX: WOW).

    For those excited by the prospective takeover, Wesfarmers’ bid is now the last one standing.

    At the time of writing, the Wesfarmers share price is $57.40. Meanwhile, API’s shares are trading for $1.52 apiece.

    Here’s how it’s expected to play out from here.

    What’s next for Wesfarmers’ takeover of API?

    Wesfarmers’ bid is the last on the table for Priceline owner, API. Woolworths withdrew its $1.75 per share takeover offer for the company on Friday, leaving the door wide open for Wesfarmers’ $1.55 offer.

    However, Wesfarmers’ takeover of API has several hurdles to complete before it can take effect.

    At this stage, the exact dates to complete them haven’t been released. Though, they might be placed on the table shortly.

    The first will be the release of a scheme booklet. The booklet will contain an independent expert’s report on the transaction, directors’ recommendations, and details on the scheme meeting.

    That is expected to drop early this year, meaning its release could be imminent.  

    The takeover will need to be approved by most API shareholders. Shareholders will be able to vote on the transaction at the scheme meeting, the date for which will likely be found in the scheme booklet.

    The takeover also needs to get approval from the Australian Competition and Consumer Commission and the courts.

    As long as each of these key happenings proceeds, the takeover is expected to happen before the end of the March quarter.

    Wesfarmers initially placed a $1.38 per share bid for API – representing a 21% premium to its last close.

    That was bumped to $1.55 after API rejected it in July. However, the bid was to be minus any dividends to API shareholders prior to the takeover becoming effective.

    As API paid its investors a 2-cent dividend in December, Wesfarmers’ offer has been dropped to $1.53 per share.

    Since Wesfarmers placed its first bid for API, the Priceline owner’s share price has gained 31%. Meanwhile, that of Wesfarmers is trading 0.8% lower than it was at the time of its initial bid.

    The post Following the Wesfarmers (ASX:WES) API takeover? Here are some key dates to watch out for appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Wesfarmers right now?

    Before you consider Wesfarmers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Wesfarmers wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Wesfarmers Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3naalej

  • Why is the Tyro (ASX:TYR) share price tumbling today?

    Close up of a sad young Caucasian woman reading about Leigh Creek Energy's declining share price on her phone

    Shares in payment solutions company Tyro Payments Ltd (ASX: TYR) opened the week down and are now inching more than 2% lower at $2.57.

    Tyro has been on an extended run downwards these past 3 months, with shares collapsing from a high of $4.12 last November.

    In today’s session, Tyro provided a glimpse of its weekly transaction value updates until 7 January 2021 in keeping with prior commitments. The company had pledged to share this data until the publication of its full year results for FY22. Here are the details.

    What’s up with the Tyro share price today?

    Tyro shares are walking lower today despite the company demonstrating a positive gain in transaction value across all time frames since the onset of FY22.

    So far in FY22, the company has grown transaction value more than 20% year on year in every single month until January.

    The highest growth period came in November last year, with the company securing $3.095 billion in transaction value, a 43% gain from the year prior. December transaction value was also 35% higher than the same period in FY20.

    As of 7 January 2022, the company boasts $16.371 billion in transaction value, a considerable 31% year on year gain from FY21.

    This is already 64% of FY21’s total of $25.454 billion even though we are still in the first month of the fiscal year.

    Even though the announcement exhibits a number of positive factors to Tyro’s growth narrative today, the market has disagreed, amid a broad-sector selloff in ASX tech shares that’s been in situ since November.

    The yield on the benchmark 10-year US Treasury note recently touched 1.8%, its highest mark since the pandemic wreaked havoc on fixed income markets. It is currently a few ticks down at 1.76%.

    As the US Fed positions itself to tighten monetary policy by tapering its quantitative easing (QE) programs this year, the markets are pricing in no less than 3 rates hikes throughout 2022, according to equity strategists Yardeni Research, Inc.

    Rising yields on US Treasuries is a negative for valuations on assets like stocks, and the impact is disproportionate to unprofitable tech companies like Tyro that may also be trading at a premium.

    As such, investors are leaning away from growth-type stocks and rotating towards more value-orientated or defensive positions, explaining the downside move in the ASX tech basket lately.

    The stress appears to have continued this week for ASX tech shares like Tyro who rely on a bottom-heavy US 10-year yield to justify trading at such lofty valuations.

    Tyro share price snapshot

    The Tyro Payments share price has plunged almost 22% in the last 12 months after sliding more than 9% in the previous month alone.

    Year to date it has fallen another 10% and the weakness has continued this past week with shares giving away another 10%.

    Each of these results is behind the S&P/ASX 200 Index (ASX: XJO)’s gain in the last year.

    The post Why is the Tyro (ASX:TYR) share price tumbling today? appeared first on The Motley Fool Australia.

    These 5 Cheap Shares Could Be Set For Huge Gains (FREE REPORT)

    We hear it over and over from investors, “I wish I had bought Altium or Afterpay when they were first recommended by The Motley Fool. I’d be sitting on a gold mine!” And it’s true.

    And while Altium and Afterpay have had a good run, we think these 5 other stocks are screaming buys. And you can find out the names of these stocks in the FREE stock report.

    *Extreme Opportunities returns as of February 15th 2021

    More reading

    The author has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Tyro Payments. The Motley Fool Australia has recommended Tyro Payments. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3n9TXdK

  • ASX 200 (ASX:XJO) midday update: AGL and Novonix shares shoot higher

    Man looks shocked as he works on laptop on top a skyscraper with stockmarket figures in graphic behind him.

    At lunch on Monday, the S&P/ASX 200 Index (ASX: XJO) is on course to start the week with a small decline. The benchmark index is currently down 0.1% to 7,445.7 points.

    Here’s what is happening on the ASX 200 today:

    AGL’s shares shoot higher

    The AGL Energy Limited (ASX: AGL) share price has been a very strong performer on Monday. Its shares are shooting higher after reportedly being upgraded by analysts at Credit Suisse. According to the Australian, the broker has upgraded the energy retailer’s shares to an outperform rating from neutral.

    Pro Medicus shares upgraded

    Another share that has been upgraded today is Pro Medicus Limited (ASX: PME). Less than a week after downgrading the health imaging technology company’s shares to a reduce rating, Morgans has upgraded them to a hold rating. Morgans made the move after a sizeable selloff last week post-downgrade left its shares trading at a fairer level. This hasn’t stopped the Pro Medicus share price from sinking today.

    Novonix aiming to join the Nasdaq

    The Novonix Ltd (ASX: NVX) share price is surging higher today after announcing plans for a secondary listing on the Nasdaq index on Wall Street. The battery materials company hopes that listing on the famous stock exchange will allow US investor and fund managers the opportunity to invest in the growing company.

    Best and worst ASX 200 performers

    The best performer on the ASX 200 on Monday has been the AGL share price with a 7.5% gain following the aforementioned broker note out of Credit Suisse. The worst performer on the index has been the Reliance Worldwide Corporation Ltd (ASX: RWC) share price with a 4.5% decline. This is despite there being no news out of the plumbing parts company.

    The post ASX 200 (ASX:XJO) midday update: AGL and Novonix shares shoot higher appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended Pro Medicus Ltd. and Reliance Worldwide Corporation Limited. The Motley Fool Australia owns and has recommended Pro Medicus Ltd. The Motley Fool Australia has recommended Reliance Worldwide Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3n5wn1J

  • Could this crypto be the Solana of 2022?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    a woman holds her hands up in delight as she sits in front of her lap

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Fantom (CRYPTO: FTM) is under the radar right now, but probably not for long. The crypto had an amazing run-up last year. The coin sold for $0.02 a year ago. Now it’s trading at $3 a coin.

    Fantom is jumping because it’s a layer 1 protocol with super-fast speeds, like Solana (CRYPTO: SOL). In 2021, those two coins skyrocketed in value 14,000% and 11,000%, respectively. Fantom is a lot smaller with a market cap of $7 billion versus $43 billion for Solana. I think part of that discrepancy is because Solana, unlike Fantom, can be bought and sold on Coinbase (NASDAQ: COIN), the biggest crypto exchange. (You can buy the coin on another exchange, Gemini.)

    I’m expecting the smaller coin to outperform Solana yet again in 2022. Here’s why you might want to own Fantom coin.

    1. It might be the fastest blockchain out there

    Last year the crypto markets went crazy for Ethereum (CRYPTO: ETH) competitors. Ethereum is the major platform for the crypto universe. But interest in crypto is skyrocketing, and the Ethereum network is creaking under the strain. The “gas fees” (the cost of validating a transaction on the Ethereum blockchain) hit $300 at one point. In comparison, a transaction on Fantom or Solana costs a fraction of a a penny.

    Why are the fees so cheap? Speed. Solana averages 50,000 transactions per second, versus 14 per second on Ethereum. Fantom is not as fast as Solana, but it’s still way ahead of Ethereum; in a test run back in 2018, its blockchain processed 25,000 transactions per second. But Fantom has a pretty solid claim to being the fastest blockchain if you look at time to finality. This is arguably the most important statistic, as that’s the moment when a transaction has been fully validated on the chain. Fantom’s time to finality is about a second, versus 13 seconds on Solana and more than a minute on Ethereum.

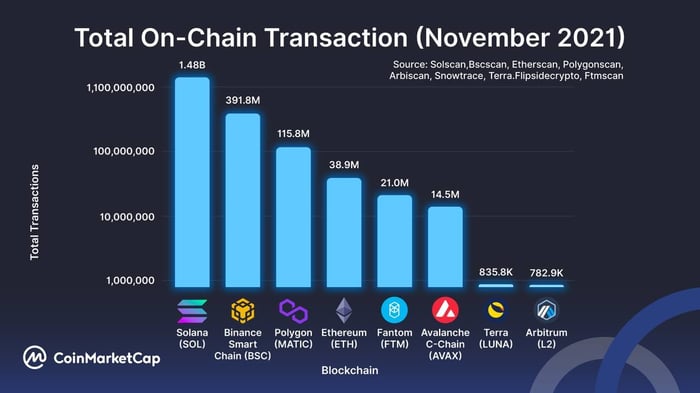
    Fantom is also rocking the total number of transactions on the blockchain. A year ago, Fantom averaged of 4,000 transactions a day. Now the network is averaging 750,000 a day. That’s an amazing growth rate. Fantom is already fifth in the number of transactions, and it has zoomed past much bigger coins like Avalanche (CRYPTO: AVAX). 

    graph of transactions on various blockchains (November 2021)


    Image source: CoinMarketCap.

    2. It’s compatible with Solana and Ethereum

    One of the challenges in the blockchain universe is compatibility. It can be hard to move a virtual wallet from one blockchain to another. So in the blockchain universe — like Silicon Valley — a lot of these blockchain networks are frenemies. They’re all competing and want to win. But they also must play nice and work together.

    Fantom, like most Ethereum competitors, is compatible with the Ethereum Virtual Machine (EVM). This makes it easier for engineers experienced with Ethereum to develop decentralized apps (dApps) for the Fantom blockchain. And it makes it easy for dApps on the Ethereum blockchain to migrate to the Fantom blockchain to save money. 

    Solana is something of a maverick in that it’s not Ethereum compatible. That puts its blockchain outside the Ethereum universe. But what’s fascinating is that Fantom is also in the Solana ecosystem. That flexibility is a strength. Regardless of who comes out on top, Ethereum or Solana, Fantom should be just fine because it’s compatible with both systems.

    3. Major players are backing the coin

    If you’ve done any crypto investing, you’ve probably heard of Sam Bankman-Fried. He’s No. 58 on the Forbes 400 list with a net worth of $26 billion, making him the richest crypto magnate on the list. 

    Bankman-Fried made a lot of money by starting up the crypto trading exchange FTX (CRYPTO: FTT). But he’s also a notable (and early) investor in Solana. Bankman-Fried once got in a Twitter fight over the price of the coin. He and a Twitter user named CoinMamba debated the worth of the Solana coin at $2, $2.05, and $2.38. Finally, on Jan. 9, Bankman-Fried tweeted, “I’ll buy as much SOL has you have, right now, at $3. Sell me all you want.” The tweet became famous as the coin skyrocketed to $149 by the end of the year.

    Bankman-Fried is also a major backer of Fantom. His firm, Alameda Research, bought $35 million in Fantom coin back in February. This happened at the same time that Fantom started to integrate its blockchain with the Solana network.

    While Bankman-Fried might be the richest backer of Fantom, the most important is probably Andre Cronje. He’s the founder of Yearn Finance (CRYPTO: YFI) and is one of the architects of the decentralized finance (DeFi) revolution. Cronje is a technical advisor to Fantom and helped develop its blockchain. He’s already created a non-fungible token (NFT) marketplace on Fantom that’s a direct competitor to OpenSea, the largest NFT marketplace. Cronje is also working on a secret project to be released on the Fantom blockchain later this year.

    Given its support by major players in the industry, its amazing speed and stratospheric growth rates, and its low valuation versus other major coins, Fantom’s crypto is likely to soar even more in 2022. While it probably won’t repeat the 14,000% growth of last year, the upside potential here is still very high. I own this coin and I’m buying more. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Could this crypto be the Solana of 2022? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    Taylor Carmichael owns Coinbase Global, Inc., Fantom, and Solana. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and recommends Coinbase Global, Inc., Ethereum, Twitter, and Yearn.finance. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3f4l858

  • James Hardie (ASX:JHX) management shakeup continues. Here’s what you should know

    a group of 3 faceless business men stand together with one extending his hands dramatically as if protesting his treatment or stating his case passionately.

    The upper management of James Hardie Industries (ASX: JHX) has been in turmoil over the last two sessions.

    The company’s now-former CEO Jack Truong was shown the door on Friday amid continued employee complaints about his behaviour. He has reportedly spoken out on his sacking this morning, disputing the company’s claims.

    In more positive news, James Hardie’s leadership team has welcomed a new face today.

    At the time of writing, the James Hardie share price is $51.305, down 0.46% from its previous close.

    For context, the S&P/ASX 200 Index (ASX: XJO) has slipped 0.07% this morning.

    Let’s take a closer look at what’s going on with the building products company.

    What’s the latest on James Hardie’s leadership spill?

    The James Hardie share price suffered on Friday after the company announced it sacked its CEO following complaints of Truong’s conduct despite him being provided “support for sincere change”.

    According to reporting by Reuters, “dozens” of the company’s executives had threatened to leave their positions as a direct result of interactions with Truong.

    Truong had held the top position since early 2019.

    Today, the former CEO disputed claims his management style was “intimidating [and] threatening”, according to reporting by the Sydney Morning Herald.

    The publication quoted Truong as saying he was “blindsided by the termination” and he “unequivocally reject[s] the assertions made by [James Hardie chair] Mr Hammes and the company”.

    Harold Wiens has been appointed as interim CEO of James Hardie in the wake of the drama. Wiens has sat on the company’s board since May 2020.

    There was also another appointment announced today, with the company welcoming a new chief technology officer (CTO).

    Dr Joe Liu has taken the position after spending 26 years with 3M Company. There, Liu held roles in research and development, as well as in commercial and international management.

    According to James Hardie, he will use his knowledge to commercialise new products for the company.

    Right now, the James Hardie share price is 4.56% lower than it was at Thursday’s close. Though, it’s still 39% higher than it was this time last year.

    The post James Hardie (ASX:JHX) management shakeup continues. Here’s what you should know appeared first on The Motley Fool Australia.

    Should you invest $1,000 in James Hardie right now?

    Before you consider James Hardie, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and James Hardie wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3n6NoIM

  • CV Check (ASX:CV1) share price leaps 7% as revenue surges

    man jumping along increasing bar graph signifying jump in alumina share price

    The CV Check Ltd (ASX: CV1) share price is surging forward on Monday following the company’s latest flash update.

    At the time of writing, the online integrated screening and verification company’s shares are up 6.90% to 15.5 cents.

    How is CV Check performing in FY22?

    Investors are sending the CV Check share price higher after the company reported robust numbers for the FY22 period.

    According to its release, CV Check advised it has achieved revenue of $6.5 million for the December quarter (Q2 FY22). This represents an 83% increase on the prior corresponding period ($3.5 million).

    When factoring in Q1 FY22 revenue, CV Check has generated total revenue of $12.8 million for the first-half of FY22. Again, this is a significant rise of 84% when compared against the first-half of FY21.

    Furthermore, consolidated revenue included $1.2 million in Software-as-a-Service (SaaS) revenue in the form of licence and consulting fees.

    During the first-half, the company focused on completing the integration of Bright People Technology, which it bought for $1 million.

    CV Check noted that its cash flow from operations was positive, and it is well-positioned for a bumper second-half. This is regardless of the repeated lockdowns and economic uncertainty that COVID-19 has caused.

    At the end of the 2021 calendar year, CV Check recorded a closing cash balance of $12.2 million.

    CV Check CEO, Michael Ivanchenko, said:

    The completion of the integration of Bright People Technologies and the commencement of execution of the company CGI (Consolidate the base, Grow new markets and Innovate) strategy is showing results.

    We continue to see strong growth in the pre-employment screening market through our returning business customers utilising more of our screening services including our Covid Vaccination checks.

    We are experiencing unprecedented interest in our SaaS real-time compliance monitoring product, Cited, and progress continues on key innovations which we look forward to announcing soon.

    About the CV Check share price

    Despite today’s ascent, the CV Check share price has moved in circles throughout the last 12 months. Its shares have posted a loss of around 17% over the period, with year-to-date currently down 6%.

    CV Check has a market capitalisation of roughly $63 million, with approximately 434.54 million shares on its books.

    The post CV Check (ASX:CV1) share price leaps 7% as revenue surges appeared first on The Motley Fool Australia.

    Should you invest $1,000 in CV Check right now?

    Before you consider CV Check, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and CV Check wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended CV Check Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3r13Co2