Category: Stock Market

  • Is Amazon stock too expensive?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.
    woman using affirm to pay

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    There are several ways to consider if a stock is expensive. However, you may be surprised to find that they do not include the selling price. That’s because even though Amazon‘s (NASDAQ: AMZN) stock is selling for over $3,000, what truly matters is where it trades relative to the company’s results, such as earnings or revenue.

    What’s more, from a practical standpoint, most brokerages will allow you to buy fractional shares of a company. For instance, if you only had $300 to invest in Amazon, you can buy 0.10 shares (at a $3,000 stock price). That said, let’s look at Amazon’s business and then determine if the stock is expensive using financial ratios. 

    The pandemic boosted an already successful business 

    Over the past decade, Amazon has grown to a massive size. Sales in its fiscal 2020 year surpassed $386 billion. That was 37.6% higher than the previous year. The coronavirus pandemic caused hundreds of millions of people to avoid shopping in person for fear of contracting the potentially deadly virus.

    Amazon was one of the prime beneficiaries of that change in consumer behavior. The company did an excellent job in delivering items that folks needed during the pandemic with only a few hiccups. That will certainly help keep those newly acquired customers with Amazon even in the aftermath of the pandemic. 

    The surge in customer spending also had a more immediate impact. In the 12 months ended Sept. 30, Amazon generated $55 billion in cash from operations and another $55 billion during the same period last year. That massive inflow of capital has allowed Amazon to invest in the business’s infrastructure. Indeed, during that same two-year period, the company has spent over $87 billion on property and equipment, such as data centers, warehouses, and delivery vans.

    These investments could make Amazon an even more customer-friendly shopping destination —  allowing it to reduce shipping times, add more items to its “Prime Delivery” option, and lower prices for customers. 

    For Amazon, attracting new shoppers and increasing the frequency at which existing shoppers buy can fuel further increases in another lucrative business segment: advertising. In its most recent quarter, the segment that houses Amazon’s advertising revenue reported a rise of 49% to $8.1 billion. And for the most recent four quarters, Amazon earned nearly $31 billion in advertising revenue. 

    Amazon’s price multiples reveal it’s not expensive

    Amazon’s business is heading in the right direction, but are its excellent prospects already priced into the stock, making it expensive for investors? 
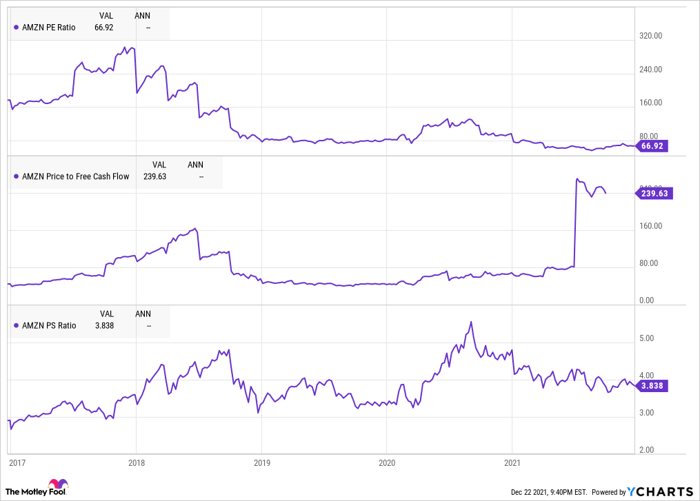
    A chart comparing Amazon's financial metrics.


    Data by Ycharts.

    According to Amazon’s price-to-earnings and price-to-sales ratios, it is not expensive; in fact, it is relatively inexpensive. However, when looking at Amazon’s price-to-free cash flow ratio, the stock does look expensive (see chart above). Considering that Amazon nearly doubled its investment in property and equipment from $30.6 billion to $56.9 billion, the cash flow figure may be less informative.

    So, overall: No, Amazon stock is not expensive. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Is Amazon stock too expensive? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Amazon right now?

    Before you consider Amazon, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Amazon wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Parkev Tatevosian owns Amazon. John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and recommends Amazon. The Motley Fool Australia has recommended Amazon. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/317aKGp

  • Pilbara Minerals (ASX:PLS) share price surges 6% to hit new record high

    A Peninsula Energy miner in hardhat and high visibility clothing makes a thumbs up symbol against a blue sky.

    The Pilbara Minerals Ltd (ASX: PLS) share price is being boosted to new heights today despite the company’s silence.

    For the first time, the lithium and tantalum producer’s stock has broken through the $3 mark. It’s a significant milestone for the company’s shares which started this year trading at just 87 cents.

    At the time of writing, the Pilbara Minerals share price is $3.11, 5.07% higher than its previous close.

    Earlier today, shares in the company were swapping hands for $3.145, marking a 6% gain and a new all-time high.

    For context, the S&P/ASX 200 Index (ASX: XJO) is currently up 0.92%.

    Let’s take a look at what could be driving the company’s stock today.

    What might be boosting the Pilbara Minerals share price?

    It’s a good day for Pilbara shareholders as the company’s share price surges amid reports 2022 is set to be another good year for lithium.

    As The Australian reported over the ASX’s Christmas break, global analysts are predicting next year will see a surge in lithium acquisitions as international giants aim to get a stronger foothold in the industry.

    That’s reflected in some brokers’ expectations for the Pilbara Minerals share price.

    As The Motley Fool Australia recently reported, Macquarie Group Ltd (ASX: MQG) analysts have tipped the stock as a buy. They’ve slapped it with a $3.70 price target. That implies it has another 17% to gain on top of its shiny new record high.

    According to the broker, its expectation for Pilbara Minerals rests on its prediction for lithium prices. It believes the lithium market will continue to strengthen over the coming year, taking the lithium producer’s stock higher in the process.

    Though not all brokers are bullish on Pilbara Minerals’ future. Credit Suisse has placed a $2.05 price target on its shares.

    Today’s gains follow on from last week’s mammoth surge. Over the last 8 days – of which, only 4 were trading days – the Pilbara Minerals share price has gained 23%.

    The post Pilbara Minerals (ASX:PLS) share price surges 6% to hit new record high appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Pilbara Minerals right now?

    Before you consider Pilbara Minerals, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Pilbara Minerals wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3ex2jHv

  • Why is the Carnaby Resources (ASX:CNB) share price up 66% today?

    a man in a hard hat and overalls raises his arms and holds them out wide as he smiles widely in an optimistic and welcoming gesture.

    The Carnaby Resources Ltd (ASX: CNB) share price is exploding today on the back of a major mining update.

    Shares in the company are swapping hands at $1.22 at the time of writing, up 66% since the Christmas Eve close. Earlier in the session, they were going for as high as $1.38.

    Let’s take a look at what may be spurring investor sentiment today.

    Major discovery

    The company announced it has made a major copper and gold discovery at the company’s Nil Desperandum Prospect within the company’s Greater Duchess Copper-Gold Project in Mount Isa, Queensland.

    Carnaby said it had identified an “exceptionally broad and high-grade copper gold intersection” at drill hole NLDD044.

    The results were better than the company estimated in announcements last week.

    Speaking on the major copper gold discovery, managing director Rob Watkins said:

    Nil Desperandum is shaping up as a major iron oxide copper gold discovery which is rapidly getting bigger and better at depth.

    The scale of the mineralised system we are seeing is exceptional.

    We look forward to 2022 as being an incredible ride for Carnaby shareholders as we escalate the exploration at the Greater Duchess Copper Gold Project to a whole new level.

    The company said it is still waiting on results from many other drill holes at the mine site, including one 80 metres to the northeast of NLDD044. More surveys and drilling will start from January 2022.

    Carnaby Resources share price snap shot

    The Carnaby Resources share price has charged up 219% year to date.

    For perspective, the S&P/ASX 200 Index (ASX: XJO) has returned nearly 12% over the past year.

    The company’s shares have also gained a staggering 404% in the past month.

    Carnaby has a market capitalisation of roughly $149 million based on its current share price.

    The post Why is the Carnaby Resources (ASX:CNB) share price up 66% today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Carnaby Resources right now?

    Before you consider Carnaby Resources, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Carnaby Resources wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3FABmic

  • Lucid, Rivian, and Tesla are just the tip of the EV stock iceberg

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    a woman holds out an electric vehicle charger with a satisfied look on her face behind cool sunglasses.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Seemingly every month, a legacy automaker makes an announcement outlining bold plans to decarbonize its operations by investing in electric vehicles (EVs).

    Simultaneously, we’ve seen plenty of new players enter the space, including Chinese automakers like Nio (NYSE: NIO) and U.S. players like Lucid Group (NASDAQ: LCID) and Rivian Automotive (NASDAQ: RIVN). A few years ago, Tesla (NASDAQ: TSLA) seemed like the only true EV investment opportunity. Today, the industry feels more crowded and competitive than ever before.

    If you’re wondering how to navigate the noise with sound investment ideas, you’ve come to the right place. Here’s the latest on Lucid and Rivian, what makes Tesla unique, and some other investment ideas worth considering now.

    Well-deserved praise

    Lucid and Rivian have plenty in common. They both have a lot of cash, impressive technology, ambitious plans to disrupt the industry, and are very expensive stocks.

    Lucid’s competitive advantage is its battery technology, which has allowed it to achieve a longer range and faster charging from a compact configuration. Its battery efficiency of more than 4.5 miles per kilowatt hour is higher than the 4 miles/kWh of Tesla’s Model S and other luxury sedans. Lucid stock was the best performing among automakers in 2021 mainly because it delivered on its major promises.

    Lucid’s initial range and horsepower projections for its Air Dream Edition were met with skepticism. But then the Environmental Protection Agency (EPA) rated the long-range version of the Air Dream Edition with a better-than-expected 520 miles of range and 933 horsepower, and the performance version of the Air Dream with an estimated range of 471 miles and 1,111 horsepower.

    This stamp of approval was just one factor of many that made the industry take Lucid seriously. It has expanded its manufacturing capacity, has over 17,000 reservations for its Air line, and plans to expand capacity even further while rolling out lower-priced Air versions in 2022.

    Like Lucid, Rivian has a large existing manufacturing capacity, plans to expand in the years ahead, and has strong demand for its vehicles. The company is looking to disrupt the electric van, truck, and SUV market. Although it began deliveries in the third quarter, the results came in lower than Rivian had guided for. However, a bright spot was that pre-orders for its R1T truck now stand at over 71,000, and that’s on top of R1S reservations and the 100,000 delivery vans Amazon pre-ordered.

    Rivian was awarded the Motor Trend 2022 Truck of the Year award and Lucid received the Motor Trend 2022 Car of the Year award. Investing in either company is a bet that their technology will hold up as new players enter the space, that they will grow production over time, and one day achieve consistent positive operating cash flow and profitably. It’s a tall order, which is why both companies are some of the highest-risk options in the industry.

    A dynasty far from decline

    Despite the potential of companies like Lucid and Rivian, the idea that either is the “next Tesla” is doubtful. Tesla is the industry leader and is probably going to remain the most valuable automaker for decades to come.

    Its invaluable first-mover advantage, incredible technology, and years making mistakes (and learning from them) have made it a battle-hardened veteran with one of the highest operating margins in the industry. Put another way, Tesla may not produce the most cars, but it does convert more revenue into actual profit than its competitors.

    Its renewable energy and energy-storage segments are growing and also very profitable. In sum, betting against Tesla is a bad idea, especially if the company continues to retain its high profitability even as it grows revenue at a breakneck pace.

    Less limelight, but lots of potential

    The EV industry is so much more than new automakers or Tesla becoming even bigger. Lucid and Rivian will also have to compete against a crowd of legacy automakers backed by much larger workforces and capital. Make no mistake, these companies are not just going to sit idly by and watch newcomers gobble up market share that took them decades to build.

    The legacy automaker that has arguably done the best job fostering real change is Ford (NYSE: F). It may surprise you to learn that Ford stock more than doubled in 2021, making it the second-best performing automaker behind Lucid for the year. Its new management team is keen on investing heavily into EVs to dominate the electric truck industry and compete in electric SUVs — and it’ll soon be making its own batteries and producing vehicles at its new mega factories in Tennessee and Kentucky.

    Another way to invest in the EV industry is through infrastructure companies like ChargePoint (NYSE: CHPT), the largest Level 2 (240 volt) charging network in North America. It’s quickly growing its Level 3 DC fast-charging network, and continues to look for ways to monetize its subscription business. Although ChargePoint’s growth and path to profitability are attractive, some investors may prefer to go with a basket of EV charging stocks.

    Zoom out and focus on the big picture

    Real gains aren’t made when a company beats a single quarter’s estimates. Rather, they are made over the long term as new companies evolve into paradigm-shifting growth stories that go on to define an industry. That’s exactly what Tesla did to the auto industry. And while there may never be another company quite like it, the auto industry has a very good chance of looking much different a decade from now than it does today.

    An investor’s task is to determine which companies have the best chance of succeeding and avoid those that aren’t making the necessary capital commitments to prepare their businesses for the future.

    It isn’t hard to envision an EV stock like Lucid taking market share from today’s leading luxury sedan makers. Or Rivian taking a chunk out of Jeep’s business. Or Ford emerging from the shift from the internal combustion engine (ICE) to the electric motor with a tighter grasp on the global truck market. Or ChargePoint expanding its footprint across North America and Europe.

    No matter how good a company’s prospects look, the reality is that no one knows exactly which of them will emerge victorious, how long it will take for EVs to surpass ICE vehicles, or if other transportation fuels like compressed natural gas and hydrogen will also take large shares out of the commercial and passenger vehicle markets. Therefore, the best choice for most investors is probably to compile a basket of EV stocks. That way, diversification reduces risk without compromising the chance for upside if a single company proves to be a long-term winner.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Lucid, Rivian, and Tesla are just the tip of the EV stock iceberg appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. Daniel Foelber has no position in any of the stocks mentioned. The Motley Fool owns and recommends Amazon, NIO Inc., and Tesla. The Motley Fool recommends the following options: long January 2022 $1,920 calls on Amazon and short January 2022 $1,940 calls on Amazon. The Motley Fool has a disclosure policy.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.


    from The Motley Fool Australia https://ift.tt/3qyE0hT
  • 3 ASX biotech shares rated as buys in 2022

    a biomedical researcher sits at his desk with his hand on his chin, thinking and giving a small smile with a microscope next to him and an array of test tubes and beackers behind him on shelves in a well-lit bright office.

    ASX biotech shares were a mixed bag in 2021. Several of the majors came in behind their benchmarks whilst many smaller players outshone the pack.

    The sector has been the benefactor of long-term tailwinds in diagnostics and demand for novel treatment solutions this year. However, the momentum has been pared back across the board.

    For instance, the S&P/ASX 300 Pharmaceuticals & Biotechnology Index (AXPBKD) has spiked from its lows this month after collapsing hard in early December. Yet, zooming out a little, it is down 8% off previous highs and now trading at October 2021 levels.

    As the impacts of COVID-19 begin to wind back, the growth outlook for the ASX biotech space is one to look out for over the coming 12 months, according to several experts covering the space.

    Here’s what stocks analysts are recommending for ASX biotech shares in 2022.

    Telix Pharmaceuticals Ltd (ASX: TLX)

    Shares in oncology company Telix recently passed their previous 12-month highs over recent weeks and, at the time of writing, are now trading for $7.85 apiece.

    Telix’s novel imaging platform for prostate cancer, Illuccix, has been in focus lately. News surrounding Illucix has seen investors piling into Telix to secure a spot in the company’s growth engine for 2022.

    Most recently, the company advised the US Food & Drug Administration (FDA) had approved the technology for use as a diagnostic imaging platform for prostate cancer.

    Aside from this, the company also recently advised its Illucix platform was awarded marketing authorisation application (MAA) in Europe. It now expects European approval for registration status no later than 23 March 2022.

    All of this regulatory momentum has analysts updating their outlook on Telix’s growth potential into the new year.

    Indeed, the team at Wilsons recently raised its valuation by 53% to $10.35 and reckons Telix is a buy at its current prices.

    Meanwhile, just before Christmas, analysts at Bell Potter also upgraded their valuation on Telix by another 16%. They feel the company’s shares are worth $9.65 apiece whereas both Jarden and Jefferies also reckon Telix is a buy, valuing the company at $8.50 and $7 respectively.

    CSL Ltd (ASX: CSL)

    Shares in biotech giant CSL were on a rollercoaster ride in 2021 and showed a wide spread in pricing across the year to date.

    For instance, the $140 billion company (by market capitalisation) traded as low at $246 and closed as high as $317 in that time — a 29% spread in price action.

    Now, with CSL’s acquisition of Vifor Pharma for US$11.7 billion confirmed and due to settle in the coming months, several experts reckon its share price is set to spike in 2022. They rate the company as a buy.

    Certainly, the team at investment bank Citi reckons the acquisition to be “[approximately] 9% accretive to NPTA (NPAT before acquisition-related amortization)” – a proxy for cash flow.

    When factoring in the non-cash item of amortization, the transaction is expected to be “modestly accretive” to earnings per share (EPS). CSL also raised $6.3 billion in capital to finance the transaction, the largest primary equity raise in ASX history.

    Citi recently upgraded its recommendation on CSL shares to a buy with a bullish $340 per share price target, implying an upside potential of 16% at the time of writing.

    Morgans is equally as bullish and just recently raised its price target by 3% to $334 per share. The broker says that investors’ worries about the deal are “misplaced as this deal looks as unique as CSL itself, allowing access to a defensible specialty product portfolio with strong market positions and growth opportunities, far from a ‘typical’ pharma transaction”.

    Morgans reckons CSL is a buy in 2022 alongside Jarden, Jefferies and Macquarie — just to name a few.

    Immutep Ltd (ASX: IMM)

    Shares in Aussie biotech Immutep have also been on the back end of some wide-reaching volatility this year. They’re now trading at 49.5 cents a share.

    However, this is a substantial plunge from the company’s 12-month highs of around 70 cents a share earlier in the year.

    Immmutep’s novel LAG-3 solution has been the major focus for investors and analysts this year, although the company has also seen growth in other areas of its pipeline in 2021.

    For instance, the company recently advised it has signed a Manufacturing Service Agreement
    (MSA) with contract manufacturer Northway Biotech, to manufacture IMP761 ahead of clinical testing.

    IMP761 is one of Immutep’s preclinical candidates for autoimmune diseases. It is classed as an immunosuppressive agonist antibody to LAG-3.

    Under the agreement, Northway will manufacture IMP761 in large scale bioreactors. After completion of the required preclinical developments, the material produced will be used for Immutep’s clinical trials of IMP761.

    Momentum like this has the team at Jefferies interested, with the firm recently initiating coverage with a buy and a $1 per share price target.

    Wilsons is also bullish on the company. It notes how LAG-3 has changed the narrative on cancer investigation and treatment for the better which, it believes, the market could be overlooking.

    The broker values Immutep at 91 cents with a buy recommendation. Meanwhile, Bell Potter also rates the company as a “speculative buy” at $1 per share.

    All in all, the average price target of $1.12 on Immutep’s share price implies an upside potential of 124% into 2022 should these brokers’ forecasts come to fruition.

    The post 3 ASX biotech shares rated as buys in 2022 appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ASX biotech shares right now?

    Before you consider ASX biotech shares, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ASX biotech shares wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The author has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended CSL Ltd. The Motley Fool Australia has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/344OBd4

  • Here’s why the Magnis (ASX:MNS) share price is powering ahead today

    asx share price increase represented by golden dollar sign rocketing out from white domes of lithium

    The Magnis Energy Technologies Ltd (ASX: MNS) share price is powering ahead on Wednesday. This comes after the battery technology company announced a milestone achievement for the New York lithium-ion battery plant.

    At the time of writing, Magnis shares are fetching 47.5 cents apiece, up 4.40%.

    What did Magnis announce?

    Investors are pushing Magnis shares higher following the company’s latest positive release.

    In a statement to the ASX, Magnis advised that it has commenced semi-automated production at the iM3NY Battery Plant.

    Based in Endicott, New York, the facility is expected to scale up to 1.8 GWh, starting in the first half of 2022. This will make it one of the largest players in the United States lithium-ion battery cell manufacturing market.

    Magnis is a major shareholder with roughly a 60% stake in iM3NY, a New York based lithium-ion Battery plant.

    Achieving semi-automated production is an important phase where batches of cells are produced for both marketing and due diligence purposes.

    The volume of power output is set to continue increasing at the plant to fully automated production.

    Magnis chair, Frank Poullas commented:

    2021 has been an amazing year for iM3NY and to achieve semi-automated production utilising the equipment we purchased over the last couple of years is a major milestone and the significance cannot be understated as the project continues to be de-risked.

    We look forward to producing revenues in 2022 and laying down the foundation to grow production exponentially towards our goal of 32GWh of annual production.

    About the Magnis share price

    In the past 12 months, Magnis shares have boasted a gain of around 150% from continued positive investor sentiment. The company’s share price charged higher in late October after receiving an aquifer permit approval for the lithium-ion battery plant.

    Based on today’s price, Magnis has a market capitalisation of around $469.71 million, with roughly 978.56 million shares on issue.

    The post Here’s why the Magnis (ASX:MNS) share price is powering ahead today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Magnis right now?

    Before you consider Magnis, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Magnis wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3Js10rN

  • Why is the NAB (ASX:NAB) share price having such a merry December?

    ASX bank shares buy A young boy in a business suit giving thumbs up with piggy banks and coin piles

    The National Australia Bank Ltd. (ASX: NAB) share price has surged this month. It has gained 6.8% despite no price-sensitive news having been released by the bank.

    However, Australia’s second largest bank hasn’t been sitting on its hands. Let’s take a look at what it has been up to lately.

    At the time of writing, NAB’s stock is trading at $29.18 apiece.

    What might’ve boosted the NAB share price this month?

    The major news moving the NAB share price this month came from the bank’s annual general meeting on 17 December.

    It saw the bank’s chair, Philip Chronican announcing some notable environmental, social, and governance (ESG) changes.

    These changes were made after NAB’s 2018 self-assessment into governance, accountability, and culture, following the Financial Services Royal Commission.

    One of the changes will see 12,000 NAB bankers placed on fixed pay to reduce their need to ‘sell’ to customers.

    That’s not the only time NAB’s employee’s wages have hit headlines this month.

    The Finance Sector Union released a damning report in early December. It claimed 87% of Group 3 NAB employees surveyed by the union reported experiencing stress and anxiety stemming from excessive working hours.

    And It’s not just alleged happenings at the bank’s workplaces that have put it in the spotlight recently.

    All eyes were on the share price of NAB, and those of its S&P/ASX 200 Index (ASX: XJO) bank peers, after new requirements were put forward by the Australian Prudential Regulation Authority (APRA) earlier this month.

    While news the entity could be tightening its strings on financial institutions might have initially worried some investors, the NAB share price ultimately bounced 0.8% following APRA’s release on 2 December.

    Finally, the bank recently made news by being the latest ASX 200 bank to increase its fixed interest rates.

    However, its stock’s future could be looking bright.

    As The Motley Fool Australia recently reported, Bell Potter believes the NAB share price is in the buy zone. The broker has a price target of $32 on the bank’s shares.  

    The post Why is the NAB (ASX:NAB) share price having such a merry December? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in National Australia Bank right now?

    Before you consider National Australia Bank, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and National Australia Bank wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/32yJSzV

  • Here’s an under the radar ASX growth share with 22% upside

    a man looks down at his phone with a look of happy surprise on his face as though he is thrilled with good news.

    The Adairs Ltd (ASX: ADH) share price is pushing higher on Wednesday morning with the rest of the market.

    At the time of writing, the furniture and homeware retailer’s shares are up 1.5% to $3.93.

    This means the Adairs share price is now up 15% in 2021.

    Is it too late to invest?

    The good news for investors is that one leading broker believes the Adairs share price can still rise materially from here.

    According to a recent note out of Morgans, its analysts have put an add rating and $4.80 price target on the company’s shares. Based on the current Adairs share price, this suggests that it could still rise by a further 22% over the next 12 months.

    But it gets better. Morgans also expects the company to pay a fully franked 23 cents per share dividend in FY 2022. This represents a generous 5.8% dividend yield, which brings the total return on offer here to almost 28%.

    Why is Morgans so bullish?

    Morgans notes that Adairs has agreed to acquire Focus on Furniture for $80 million, which it feels is a fair price.

    The broker commented: “We think ADH has got the business for a decent price and, while we concede it increases the group’s exposure both to the housing market and bricks and mortar retail (neither of which are terribly fashionable right now), we believe it will prove complementary to the core business and may offer enhanced opportunities for network expansion.”

    And while the broker acknowledges that the acquisition hasn’t helped dispel the view that Adairs could struggle for organic growth post-COVID, it doesn’t believe this is the case. In fact, Morgans is forecasting strong earnings growth through to FY 2024.

    Its analysts explained: “It seems to us that the market sees ADH as a COVID beneficiary that is unlikely to deliver much in the way of organic growth over the next few years. Buying Focus perhaps hasn’t done anything to dispel this notion. But we think that’s unfair. Our estimates are for an EPS CAGR of 21% between FY20 and FY24F. The acquisition of Mocka and Focus play a large part in driving this, but even organically, a combination of a very strong loyalty programme, GLA growth and cost efficiencies underpin a growth story that we think is going under the radar.”

    The post Here’s an under the radar ASX growth share with 22% upside appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Adairs right now?

    Before you consider Adairs, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Adairs wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns and has recommended ADAIRS FPO. The Motley Fool Australia owns and has recommended ADAIRS FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/32NwbwU

  • December is shaping up to be pretty good for the Telstra (ASX:TLS) share price . Here’s why

    person on old-fashion telephone, surprised person

    The Telstra Corporation Ltd (ASX: TLS) share price is having a positive December 2021 – it’s currently up around 2%.

    That adds to what has actually be a market-beating year for Telstra shares.

    The Telstra share price has gone up 38% this year, which compares to the S&P/ASX 200 Index (ASX: XJO) return of 12% this year.

    What has been going in December 2021?

    The telecommunications giant hasn’t announced much during December 2021. It has continued with its share buy-back, which is a way to return capital to shareholders and improve the per-share statistics such as earnings per share (EPS).

    However, there was one market sensitive announcement that was released this month.

    Telstra said that it had secured the maximum possible low band spectrum to maintain its “leading” mobile network.

    Earlier this month, the telco said that it had invested $616 million in the Australian Communications and Media Authority’s 850/900 MHz band auction to secure 2x10MHz – this is the maximum Telstra could bid for under the competition limits set by the government.

    Telstra now has more spectrum than any other carrier, which it said was important given the larger customer base and it will help it provide the best mobile coverage and service.

    This spectrum is particularly important for its 5G rollout and it will help provide better coverage indoors and other difficult to reach places in metro locations.

    Over the seven years to the end of FY22, it will have invested $11 billion in its mobile network nationally, with $4 billion invested in the mobile network. It’s aiming to provide 5G coverage to 95% of the population by 2025.

    What do analysts think of the Telstra share price?

    There are quite a few brokers that like Telstra shares at the moment. A recent note from Ord Minnett re-iterated its buy rating on the telco.

    Ord Minnett’s price target on Telstra is $4.60, which is around 10% higher than where it is today.

    The broker notes that the telco is getting stronger in non-metro locations with its ongoing investment.

    Analysts are also positive on the Digicel Pacific acquisition and how it is structured. It adds to, and diversifies, the telco’s earnings.

    Three months ago, Telstra revealed its T25 strategy which involves more network coverage, profit growth and margin growth, a goal of growing the dividend over time and a further reduction in costs. It’s looking to reduce net fixed costs by a further $500 million between FY23 to FY25.

    At the current Telstra share price, Ord Minnett thinks that it’s valued at 24x FY23’s estimated earnings.

    The post December is shaping up to be pretty good for the Telstra (ASX:TLS) share price . Here’s why appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Telstra right now?

    Before you consider Telstra, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Telstra wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns and has recommended Telstra Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3sApE3o

  • Novonix (ASX:NVX) shares rocketed 600% this year. Now what?

    green fully charged battery symbol surrounded by green charge lights

    Those lucky enough to have Novonix Ltd (ASX: NVX) shares since the start of the year would have had a broad smile on their face eating their Christmas turkey.

    The stock price for the battery materials company has rocketed 594% since the fireworks went off at the start of January.

    So now the dilemma is what to do with a stellar performer as we head into the new year.

    If you have it, do you hold onto it or take the profits? If you don’t have it, is it too late to buy in or has the ship sailed?

    The team at Marcus Today had some thoughts.

    No profit, not much revenue (yet)

    Firstly, it must be noted that Novonix is a polarising stock.

    The company is a long way from turning a profit, and doesn’t yet make a huge amount of revenue — not much more than $5 million — considering its valuation.

    “A profit isn’t expected to be achieved for a few years so it will be incredibly announcement driven,” read the memo from Marcus Today.

    “Deals with EV [electric vehicle] and tech companies to shore up supply chains likely to drive performance but that will come in dribs and drabs.”

    Massive unexplained fall in share price

    Secondly, despite this year’s spectacular rise, the share price has fallen almost 28% this month. 

    This worries the team at Marcus Today.

    “An unexplained 34% fall [in early December] should be a bit of a red flag,” the memo stated.

    “The move has taken some of the froth off the top, which is putting it back in the focus of ‘bargain hunters’. [But] unclear if it is a bargain at current levels given the eye-watering valuation at 723x revenue.”

    We need to see more runs on the board

    A little bit more tangible progress would be needed before the Marcus Today team would buy in.

    It noted Novonix does have some heavy hitters on its board, which “looks like it has some leverage in Washington [DC]”.

    “Favourable legislative outcomes from the US are another possible tailwind,” the memo read. 

    “A period of share price consolidation around the 900c level, progress on its production capacity and a deal or two would make it look more appealing.”

    So for now, Marcus Today would not get involved, although if you already own Novonix shares you’d want to hold onto them.

    “The near-term picture doesn’t offer that much of a compelling reason to get involved,” the team stated.

    “Demand for its products are expected to gain momentum but until there are more cash flows, it is hard to value. No obvious reason to sell if you have decided to hold. HOLD.”

    The post Novonix (ASX:NVX) shares rocketed 600% this year. Now what? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Novonix right now?

    Before you consider Novonix, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Novonix wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3pzzpNi