Category: Stock Market

  • Why the Brisbane Broncos (ASX:BBL) share price up 16% on Tuesday

    stadium signifying brisbane broncos share price

    The Brisbane Broncos Limited (ASX: BBL) share price has stepped firmly into the green during early trade on Tuesday.

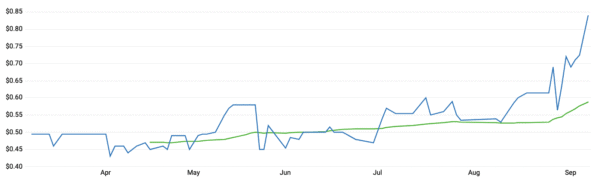
    Brisbane Broncos’ shares are now exchanging hands at 84 cents apiece, a 16% jump from the opening of trade.

    Let’s investigate further.

    Quick recap on Brisbane Broncos

    Brisbane Broncos is a sports entertainment business that is best known for its ownership of the National Rugby League (NRL) football team of the same name.

    The Brisbane Broncos franchise generates revenue from sponsorships and from sales of its merchandise and memberships.

    At the time of writing, Brisbane Broncos has a market capitalisation of $71 million.

    What tailwinds are behind the Brisbane Broncos share price lately?

    There has been no market sensitive information released for the company on Tuesday.

    However, the Brisbane Broncos share price has been on the move since the company reported its half year results in early August.

    Brisbane Broncos’ share price – significant uptick since August to date
    Source: The Motley Fool

    In its report, the company recognised a net profit before income tax (PBIT) of $3.17 million, a significant increase from $22,000 a year ago.

    This came from revenue recognition of $25.34 million in the half year ended June 30 2021, underscored by an NRL grant of $7.2 million and sponsorship growth of 26% over the year.

    One factor that is important to note, is that the performance for the same time in 2020 “reflects the unprecedented negative impact that Covid-19 restrictions had on the Group”.

    However, in saying this, the company’s half yearly PBIT for 2019 came in at $1.3 million. This means the company still grew its profitability in 2021 when backing Covid-19 out of the equation.

    Aside from these driving factors, there has been no market-moving announcements that relate to the company.

    However, the recent uptick in the Brisbane Broncos share price from 27 August does show an interesting correlation to the NRL finals series.

    For example, several NRL finals games are scheduled at the Brisbane Broncos’ home ground, Suncorp Stadium. This is in accordance with the NRL competition being relocated to Queensland due to the Covid-19 pandemic.

    In other words, this is an anomaly for the 2021 season, as the majority of NRL finals games would otherwise be played in NSW venues located in Sydney.

    As a result, the group is set to benefit from revenues associated with crowd attendance at this venue, that are asymmetrical to previous years.

    Brisbane Broncos share price snapshot

    The Brisbane Broncos share price has posted a return of 93% over the year to date. This extends the gain over the previous 12 months to 110%.

    Both of these results have outpaced the S&P/ASX 200 index (ASX: XJO)’s climb of around 25% over the past year.

    The post Why the Brisbane Broncos (ASX:BBL) share price up 16% on Tuesday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Brisbane Broncos right now?

    Before you consider Brisbane Broncos , you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Brisbane Broncos wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The author Zach Bristow has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/38KGgKv
  • Flight Centre (ASX:FLT) share price storms 6% higher on broker upgrade

    A smiling travel agent sitting at her desk working for Flight Centre

    The Australian share market may be dropping today but that hasn’t stopped the Flight Centre Travel Group Ltd (ASX: FLT) share price from storming higher.

    At the time of writing, the travel agent’s shares are up 6.5% to $18.67.

    This compares very favourably to a 0.4% decline by the S&P/ASX 200 Index (ASX: XJO).

    Why is the Flight Centre share price storming higher?

    The catalyst for the rise in the Flight Centre share price on Tuesday has been a bullish broker note out of Credit Suisse this morning.

    According to the note, the broker has upgraded the company’s shares to an outperform rating with an improved price target of $19.00.

    Based on the Flight Centre share price at Monday’s close of $17.50, this implied potential upside of 8.6% over the next 12 months.

    However, with the company’s shares storming higher today, the upside is now a more modest 1.8%.

    Why did the broker upgrade Flight Centre?

    Credit Suisse upgraded the Flight Centre share price from a neutral rating to an outperform rating for a number of reasons.

    One of those was the positive progress Australia is making with the vaccine rollout. This is expected to support the travel market recovery and underpin its return to break-even.

    In addition to this, the broker is a big fan of Flight Centre’s corporate business. It notes that the high quality business has been winning market share and appears to believe this trend will continue.

    What about its rivals?

    Unfortunately, Credit Suisse isn’t as positive on the Webjet Limited (ASX: WEB) share price. This morning it downgraded the online travel agent’s shares to a neutral rating with a $5.70 price target.

    While the broker sees significant upside if Webjet delivers on its cost reduction targets, it isn’t enough for a more positive rating. This is due largely to valuation reasons.

    Nevertheless, this hasn’t stopped the Webjet share price from climbing almost 1% today.

    The post Flight Centre (ASX:FLT) share price storms 6% higher on broker upgrade appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Flight Centre right now?

    Before you consider Flight Centre, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Flight Centre wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Webjet Ltd. The Motley Fool Australia has recommended Flight Centre Travel Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2X2Gjzd

  • Why the Pan Asia Metals (ASX:PAM) share price is rocketing 39% today

    Vanadium Resources share price person riding rocket indicating share price increase

    The Pan Asia Metals Ltd (ASX: PAM) share price is surging again in early trade. Shares are up 39% at the time of writing to 79 cents.

    Today’s meteoric rise for the ASX battery metals explorer follows a series of recent huge daily gains.

    Those daily leaps have seen Pan Asia Metals share price soar an astonishing 380% since 30 August. Yep, that’s just 6 days ago.

    Yesterday, investor enthusiasm was roused by the company’s announcement of its capital raising.

    Today, investors appear to be snapping up stock following the release of promising drilling results.

    What drilling results did the resource explorer report?

    The Pan Asia Metals share price is off to the races again today after the company reported it had intersected thick pegmatites at its Reung Kiet Lithium Prospect in Thailand.

    The promising results come from 6 additional drill holes. According to the explorer, they indicate the potential of “extensive lithium mineralisation hosted in lepidolite rich pegmatite dykes and veins”.

    Pan Asia Metals managing director Paul Lock noted, “Peer feasibility studies suggest that lepidolite is the lowest cost source of lithium and potentially has one of the lowest carbon footprints.”

    The company has defined a 1-kilometre strike length which remains open.

    Some of the top results include:

    • RKDD031: 14.9 metre wide pegmatite from 90.1 metre; and 18.4m thick pegmatite from 130.7m
    • RKDD030: 31.4m of composite pegmatite thickness from 42.3m-80.2m
    • RKDD029: 23.25m thick pegmatite dyke from 49.95m

    Commenting on the results, Lock added:

    We are rapidly progressing to a Mineral Resource and we are targeting the delivery of a Scoping Study in the first quarter of calendar year 2022. Our aim at the Reung Kiet Lithium Project is to deliver a Mineral Resource which is sufficient to operate a 10,000 tonne per annum lithium hydroxide or lithium carbonate plant for 10 plus years, initially.

    The company said it intends to continue drilling, aiming to report a Mineral Resource in accordance with the JORC Code 2012.

    It expects assay results for 7 previously drilled holes in about 2 weeks.

    Pan Asia Metals share price snapshot

    Year-to-date, the Pan Asia Metals’ share price has soared 461%. To put that in some perspective, the All Ordinaries Index (ASX: XAO), which is having a very strong year so far, is up 12% in 2021.

    The Pan Asia Metals share price is up 342% since this time last month.

    The post Why the Pan Asia Metals (ASX:PAM) share price is rocketing 39% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Pan Asia Metals right now?

    Before you consider Pan Asia Metals, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Pan Asia Metals wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3zPhk0k

  • Why the BetMakers (ASX:BET) share price has rocketed 50% in 7 weeks

    Couple cheer and celebrate after winning on online bet while sitting on sofa

    The BetMakers Technology Group Ltd (ASX: BET) share price has had a stellar month and a half.  

    Shares in the wagering company have powered more than 50% in the past 7 weeks.

    Let’s take a look at what’s been driving the BetMakers share price.

    What’s been fuelling the BetMakers share price?

    Several catalysts have helped power the BetMakers share price in the past month and a half.

    After being sold-off initially, shares in the wagering company were boosted by record quarterly results.

    For the fourth quarter, BetMakers recorded $8.91 million in cash receipts, a 272% increase on the prior corresponding period.  

    BetMakers attributed the strong growth to improved sentiment in the Australian market and positive results from its international expansion.

    In addition, the company cited its recent acquisition of Sportech PLC for enhancing the company’s revenue-generating opportunities.

    The BetMakers share price received a further boost in early August following a landmark achievement.

    Shares in the wagering company were buoyed after New Jersey legalised fixed-odds wagering. The legalisation of fixed-odds wagering bodes well for the company’s US ambitions.  

    BetMakers currently holds a 10-year agreement to deliver and manage fixed-odds thoroughbred horse racing in New Jersey.

    Another catalyst was the company’s recent full-year report for FY21.

    How did BetMakers perform in FY21?

    Late last month BetMakers posted its full-year results for FY21. For the full year, the wagering company reported a 126.7% surge in revenue of $19.5 million.

    Despite the promising revenue figure, BetMakers recorded a net loss of $13 million for FY21 versus a $4.4 million loss in FY20.

    BetMakers cited extra investments to support its international expansion for the widened earnings loss.

    For FY21, the wagering company spent $2.4 million in operating expenses for its US business.

    Snapshot of the BetMakers share price

    Shares in BetMakers have more than doubled this year. Since the start of the year, the wagering company’s share price has surged by more than 111%.

    The company’s growing market capitalisation was recently acknowledged with BetMakers being added to the S&P/ASX300 Index.

    The BetMakers share price has continued its bullish run today. At the time of writing, shares in the company are powering 7.34% higher for the day at $1.39.

    The post Why the BetMakers (ASX:BET) share price has rocketed 50% in 7 weeks appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BetMakers right now?

    Before you consider BetMakers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BetMakers wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Nikhil Gangaram has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Betmakers Technology Group Ltd. The Motley Fool Australia has recommended Betmakers Technology Group Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3yTPFtU

  • Why the Mosaic Brands (ASX:MOZ) share price is shooting 16% higher

    two fashionable asx investors dancing among confetti

    The Mosaic Brands Ltd (ASX: MOZ) share price has been a very strong performer on Tuesday.

    In morning trade, the retailer’s shares are up 16.5% to 63.5 cents.

    Why is the Mosaic Brands share price shooting higher?

    Investors have been bidding the Mosaic Brands share price higher today after it secured its future via an underwritten capital raising.

    This morning the company announced an underwritten $32 million capital raising via the issue of convertible notes. This comprises a $10 million strategic placement of notes to Danfin Pty Ltd and a $22 million 1 for 4.39 pro-rata non-renounceable entitlement offer of notes to eligible shareholders.

    The aforementioned notes will be secured by a second-ranking security behind the existing Australia and New Zealand Banking GrpLtd (ASX: ANZ) facility. Positively, the release advises that ANZ has provided consent to the issue of the notes.

    Why is the company raising funds?

    Mosaic Brands is raising funds for general working capital purposes and to provide the business with additional balance sheet support until COVID-19 related lockdown measures are eased and stores re-open for trade.

    Following the completion of the capital raising, Mosaic Brands expects to be well funded through the current period of disrupted trading. This is based on conservative assumptions around lockdown easing measures and the timing of stores re-opening.

    In addition, Mosaic Brands intends to exercise its option for the remaining shares in Ezibuy during September. Payment terms for the $11 million acquisition consideration are proposed to be extended from 31 December 2021 to provide additional balance sheet flexibility. Mosaic Brands would have up to 30 June 2022 to settle the exercise price.

    Mosaic Brands notes that it will have pro forma cash of approximately $88.1 million post completion of the offers.

    The Mosaic Brands share price is down 23% in 2021 despite today’s strong gain.

    The post Why the Mosaic Brands (ASX:MOZ) share price is shooting 16% higher appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Mosaic Brands right now?

    Before you consider Mosaic Brands, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Mosaic Brands wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3BLTZNF

  • Openpay (ASX:OPY) share price rallies on major expansions

    a woman wheels five rubber car tyres piled onto a trolley.

    The Openpay Group Ltd (ASX: OPY) share price is rallying on Tuesday after the company announced the signing of significant strategic partnerships across key verticals in Australia and the United Kingdom.

    At the time of writing, the Openpay share price is 3.04% higher at $1.355.

    Openpay share price higher lifts on major expansions

    From the get-go, Openpay has focused on differentiating itself from peers in the “pay-in-4” space by focusing on longer, larger, verticalised plans in meaningful industries.

    The company was pleased to announce a number of significant wins in Australia to “solidify its position as a market-leading BNPL provider in the Automotive vertical”.

    Openpay signed a partnership with tyre marketer, wholesaler and retailer, Goodyear & Dunlop Tyres Australia. This will bring on board 160 company-owned Beaurepaires stores that can now offer Openpay services as an alternative payment option.

    Openpay already had an existing 143 Goodyear Autocare Centres and 148 Dunlop Super Dealer stores using its services prior to today’s partnership.

    In addition, the company signed partnership agreements with the Victorian Automobile Chamber of Commerce (VACC) and Bosch Car Service Australia to offer Openpay services at more than 5,000 locations combined.

    The Openpay share price could also be benefiting from the company’s growth in the Healthcare vertical.

    According to today’s announcement, Openpay signed a partnership with Nexus Hospital to offer services to self-funded patients through the private hospital and specialists network.

    In addition, Openpay entered into the UK healthcare sector with an agreement with Henry Schein, Software of Excellence, a global leader in the provision of dental price management software.

    Openpay highlighted that “[w]ith reach to over 6,000 sites in the UK, this partnership will accelerate Openpay’s ability to acquire nearly half of the UK’s dental market”.

    Back in March, Openpay revealed its entry into the US$55.8b US and UK veterinary markets in partnership with cloud-based practice management software platform, ezyVet.

    In today’s announcement, Openpay advised that its global integration with the ezyVet platform went live in the UK with several major veterinary practices signed and onboarded.

    Management commentary

    Openpay managing director and CEO Michael Eidel commented on the major automotive wins, saying:

    Automotive is at the core of our verticalised strategy as this is a sector where we can make a very meaningful difference to both merchants and customers. Access to longer and higher value plans means that unexpected and even scheduled car servicing and parts payments can be spread over time – delivering a tangible, positive impact on the household budget and cashflow.

    The announcement concluded with broader strategic commentary from Eidel.

    Openpay continues to establish partnerships with major ecosystem providers and aggregators in our target verticals across our key markets. With these new partnerships, we have deepened our focus into our core verticals in the UK, which together with the anticipated Payment Assist acquisition in Automotive and our imminent US launch, will set us up to achieve our long-term objectives of sustainable growth and profitability.

    Openpay share price snapshot

    The share prices of smaller BNPL players have struggled to stay afloat in the past 12 months.

    The Openpay share price is no exception, down 42% year-to-date and 59% in the past year.

    The post Openpay (ASX:OPY) share price rallies on major expansions appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Openpay right now?

    Before you consider Openpay, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Openpay wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3h8giVS

  • Why is the AMA Group (ASX:AMA) share price halted?

    woman sitting at desk holding hand up in stop motion

    The AMA Group Ltd (ASX: AMA) share price has been going nowhere since yesterday morning.

    A trading halt came into effect pending a release from the smash repair company before market open on Monday.

    The last closing price of AMA Group’s shares was 42 cents apiece.

    Let’s take a closer look at what the company is planning to announce to the ASX.

    Why is AMA Group share price in a trading halt?

    AMA Group provided little detail in regards to the reason why it requested the ASX to freeze its shares.

    According to the notice, AMA Group advised two consecutive trading halts are in place in respect to its securities.

    In particular, the company is carrying out a capital structure review to manage short-term disruptions caused by COVID-19.

    As such, plans are underway to initiate a capital raise to shore up AMA Group’s balance sheet.

    This comes after the company released its full-year results late last month, acknowledging COVID-19 related repair volume decreases. The average decline in vehicle collision repair volume fell 17% compared to prior period.

    At the end of the 2021 financial year (30 June), AMA Group had $64.2 million in cash and $237.5 million of debt.

    The news comes after last week’s response to media speculation regarding its capital position is in tatters. AMA Group was quick to refute the reports highlighting that an equity raise is to fuel further growth.

    It is expected that its shares will resume normal trading on or before Friday 10 September following a release.

    More on AMA Group shares

    It’s been a whirlwind 12 months for AMA Group shares, treading downwards to reach a 52-week low of 42 cents. The company’s share price has lost around 30% in value since this time last year. However, when looking at 2021 alone, its shares have fallen almost 50%.

    On valuation grounds, AMA Group presides a market capitalisation of roughly $313.5 million, with approximately 746 million shares on issue.

    The post Why is the AMA Group (ASX:AMA) share price halted? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in AMA Group right now?

    Before you consider AMA Group, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and AMA Group wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3kYDrLI

  • 3 growing small cap ASX shares to watch

    Three excited business people cheer around a laptop in the office

    At the small end of the Australian share market, there are a number of companies with the potential to grow strongly in the future.

    Three that investors might want to get better acquainted with are listed below. Here’s what you need to know about them:

    Booktopia Group Ltd (ASX: BKG)

    The first small cap ASX share to watch is Booktopia. It is an online book retailer which has brushed off the arrival of Amazon in Australia and continued its meteoric growth. This has been driven by its strong market position, the shift to online shopping, and its new distribution centre. The latter is allowing the company to capture the heightened demand and ship more books than ever.

    Serko Ltd (ASX: SKO)

    Another small cap ASX share to watch is Serko. It is the online travel booking and expense management provider behind the Zeno Travel and Zeno Expense platforms. Serko uses intelligent technology, predictive workflows, and a traveller-centric marketplace to transform the world of business travel and expense. It also recently signed a game-changing deal with travel giant Booking.com, which looks set to be a significant boost to revenues in FY 2022 and beyond.

    Whispir Ltd (ASX: WSP)

    A final small cap ASX share to watch is Whispir. It is a growing workflow platform provider that allows organisations to deliver actionable two-way interactions at scale. This is achieved using automated multi-channel communication workflows. While the company has been growing its revenues strongly in recent years, it has still only captured a small slice of its target market. For example, management estimates that it has a total addressable market (TAM) of US$4.7 billion in the just United States.

    The post 3 growing small cap ASX shares to watch appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Serko Ltd and Whispir Ltd. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended Booktopia Group Limited. The Motley Fool Australia has recommended Serko Ltd and Whispir Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2WYwP7P

  • ASX 200 energy shares in firing line of United Nations’ climate action

    Miner with a light in the darkness as he moves coal

    S&P/ASX 200 Index (ASX: XJO) energy shares focused on coal production are under fire from the United Nations’ latest proposal to try to limit global warming.

    According to the Daily Mail, the UN has given Australia a 10-year deadline to shut down the coal mining industry.

    The article noted that the UN’s assistant secretary-general and special adviser on climate action, Selwin Hart, “told the ANU’s [Australian National University] Crawford Leadership Forum the phasing out of coal is a prerequisite of limiting global warming to 1.5C”.

    According to Hart, “If the world does not rapidly phase out coal, climate change will wreak havoc right across the Australian economy: from agriculture to tourism, and right across the services sector.”

    Multibillion-dollar ASX 200 energy shares that would need to shut operations or transition to other resource development inside the next decade include Yancoal Australia Ltd (ASX: YAL), Whitehaven Coal Ltd (ASX: WHC), and New Hope Corporation Limited (ASX: NHC).

    As for the 50,000 Aussies working for these ASX 200 energy shares and in the rest of the coal industry?

    Hart said they were entitled to a “just transition” to new jobs.

    Australian government responds

    Coal, as you may be aware, is Australia’s number 2 export earner, coming in right behind iron ore.

    In fact, as Resources Minister Keith Pitt pointed out, coal exports increased 26% quarter-on-quarter in the 3 months to July, hitting $12.5 billion.

    Pitt said (quoted by the Daily Mail):

    The future of this crucial industry will be decided by the Australian Government, not a foreign body that wants to shut it down costing thousands of jobs and billions of export dollars for our economy…

    Coal will continue to generate billions of dollars in royalties and taxes for state and federal governments, and directly employ over 50,000 Australians.

    Atop the government’s strong support, there’s another hitch in the UN’s proposal that could see these ASX 200 energy shares producing coal well beyond the 10-year deadline.

    Australia only supplies 6% of the global annual coal demand. And that 6% is largely high quality, lower emissions coal compared to that supplied by other international sources.

    For the UN’s coal mining ban proposal to have any meaningful impact on CO2 reduction, the world’s top 3 coal-producing nations would surely need to be on board.

    It’s unclear if those top coal producers – China, India, and Indonesia – have been approached by the international body to plan for their own 10-year phase-out. But judging by the Australian government’s response, it’s unlikely they’ll jump on the UN’s bandwagon.

    How have these ASX 200 energy shares performed?

    The 3 ASX 200 energy shares with a strong focus on coal production listed above have put in a mixed performance this year.

    The Yancoal share price is down 3% year-to-date, and up 12% over the past month.

    The Whitehaven share price is down 25% for the calendar year, and up 35% over the last month.

    The New Hope share price is up 57% in 2021, and up 14% over the past month.

    Will investors begin selling out of these ASX 200 energy shares with an eye to potential coal bans?

    Perhaps in time.

    But at the moment, with global demand for coal remaining buoyant and government support for the industry strong, that time looks to be well over the horizon.

    The post ASX 200 energy shares in firing line of United Nations’ climate action appeared first on The Motley Fool Australia.

    Should you invest $1,000 in New Hope right now?

    Before you consider New Hope, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and New Hope wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3l3ciqK

  • Telstra (ASX:TLS) share price flat amid possible union action

    a woman in a mask holds up a hand to stop a COVID-19 vaccine being held by a medically gloved hand in the foreground.

    The Telstra Corporation Ltd (ASX: TLS) share price is at a standstill in early trading amid news the company might be facing union action over its decision to make COVID-19 vaccinations mandatory for some employees.

    Telstra reportedly sent an email to its staff yesterday outlining the soon-to-be-implemented vaccine requirements.

    The Communication Union believes workers shouldn’t be forced to get vaccinated.  

    Right now, the Telstra share price is $3.90, unmoved from its previous closing price.

    Let’s take a closer look at Telstra’s plan to make a COVID-19 vaccine mandatory for some employees.

    Telstra to make COVID-19 jabs a requirement

    The Telstra share price is steady amid news vaccines might soon be necessary to work in some of the company’s roles.

    Telstra employees who interact with customers, the broader public, or with people vulnerable to COVID-19; or those who work in high-risk locations or can’t work from home must get their first COVID-19 jab before 15 October.

    Telstra will find new roles that don’t require a jab for workers who can’t be vaccinated for medical reasons. Though yesterday, The Australian reported Telstra’s CEO Andy Penn stated employees who can’t be vaccinated might face “medical retirement”.

    According to reporting by ABC News, 8,300 Telstra employees will be affected by the decision.

    The Communications Union will be meeting with Telstra today to discuss the company’s contentious decision. The outcome of what could be a heated discussion might have an effect on the Telstra share price.

    The union believes that businesses shouldn’t force their workers to be jabbed. However, it strongly encourages Australians to get vaccinated against COVID-19.

    In a statement, the Communications Union commented:

    The Union supports our members having the choice as to whether or not they are vaccinated – not because it is a popular view amongst some of our members, but because it is based on the current public health advice….

    Unlike Mr Penn, the majority of our members have been on the front-lines of this pandemic response putting their safety, and that of their families, at risk so that people in situations like his can continue working from the safety of their homes.

    If he thinks he can sack those same essential workers who may have genuine medical exemptions, he is sorely mistaken.

    Telstra share price snapshot

    Before the announcement, the Telstra share price has been performing well lately.

    It has gained 29% year to date. It is also 35% higher than it was this time last year.

    The post Telstra (ASX:TLS) share price flat amid possible union action appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Telstra right now?

    Before you consider Telstra, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Telstra wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned.

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Telstra Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3jPL5Zr