Category: Stock Market

  • SILK Laser (ASX:SLA) share price rockets 20% after beating FY21 guidance

    Vanadium Resources share price person riding rocket indicating share price increase

    The SILK Laser Australia Ltd (ASX: SLA) share price has been a very strong performer on Wednesday.

    In morning trade, the laser clinic company’s shares are up 20% to $4.09 following the release of its full year results.

    SILK Laser share price rockets after beating upgraded guidance

    • Network cash sales increased 68% to $85.1 million
    • Reported revenue grew 82% to $58.9 million
    • Pro forma earnings before interest, tax, depreciation and amortisation (EBITDA) up 180% to $17.3 million
    • Pro forma net profit after tax up 839% to $7.5 million
    • 11 new SILK clinics opened bringing network to 116 after acquisitions

    What happened in FY 2021 for SILK?

    SILK was on form in FY 2021, delivering a 68% increase in network cash sales to $85.1 million and a 180% jump in pro forma EBITDA to $17.3 million. The latter was ahead of its upgraded EBITDA guidance range of $15 million to $16 million, which explains why the SILK Laser share price is performing so strongly today.

    This was driven by a 52% increase in like for like sales, new store openings, and strong demand in the injectables and body categories. Underpinning this was a 28% increase in average customer spend to $605.

    What did management say?

    SILK Laser’s Co-Founder and Managing Director, Martin Perelman, said: “The past 12 months have been a busy and highly successful period for SILK, and I am very proud of our first full year results delivered as a publicly listed company.”

    “Given the dedication and commitment of SILK’s employees, franchisees and joint venture partners, and our focus on excellence in customer service, all of SILK’s service categories performed in line or above expectations, and the Company is well-positioned to drive long term growth.”

    What’s next for SILK Laser?

    Also potentially giving the SILK Laser share price a lift today was a trading update and management’s outlook.

    It revealed that July 2021 sales and EBITDA exceeded what was achieved in July 2020 despite lockdowns. This is a big positive given that July and September 2020 were the most profitable months of FY 2021.

    Mr Perelman said: “The underlying business foundations of SILK are strong as demonstrated by like-for-like clinic performance when adjusted for lost trading days due to lockdowns. We’re carefully managing the COVID-19 challenges across SILK, and at present approximately 80% of our SILK clinic network remains open. Our priority is to operate in a way that keeps our customers and team members safe. Our clinics continue to build waiting lists for clients in states where clinics are closed, to capture pent-up demand in readiness for easing of lockdown restrictions. We intend to provide a further update on Q1 FY22 trading in October.”

    Management also revealed that it plans to open 4 to 8 new clinics in FY 2022, focused on Australia’s East Coast and New Zealand.

    It sees these geographical catchments as key growth markets, with up to 25 potential new sites identified for FY 2022 and FY 2023 across Australia’s East Coast. Whereas in New Zealand it aims to add 4 new clinics in FY 2022, taking the total number to 19.

    The SILK Laser share price is up 14% in 2021.

    The post SILK Laser (ASX:SLA) share price rockets 20% after beating FY21 guidance appeared first on The Motley Fool Australia.

    Should you invest $1,000 in SILK right now?

    Before you consider SILK, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and SILK wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended SILK Laser Australia Limited. The Motley Fool Australia has recommended SILK Laser Australia Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3jkzG3L
  • Northern Star (ASX:NST) share price up after reporting 300% profit surge

    gold, gold miner, gold discovery, gold nugget, gold price,

    The Northern Star Resources Ltd (ASX: NST) share price has opened only slightly higher on Wednesday after the company released its FY21 full-year results.

    At the time of writing, shares in the gold miner are up 0.2% to $9.78.

    Northern Star share price higher on record financial result

    Northern Star delivered a record financial result, following the incorporation of Saracen Mineral Holdings Ltd (ASX: SAR) from 12 February 2021. Key highlights for FY21 include:

    • Revenue up 40% to $2,761 million.
    • Earnings before interest, taxes, depreciation, and amortisation (EBITDA) lifting 216% to $2,268 million.
    • Net profit after tax (NPAT) rallying 300% to $1,032 million.
    • Final dividend of 9.5 cents per share
    • Annualised gold price realised up 3% to A$2,227/oz
    • Annualised all-in sustaining cost (AISC) increased 10% to A$1,483/oz

    What happened to Northern Star in FY21?

    The Northern Star share price has struggled to perform in FY21, down 22% year-to-date.

    Despite the struggling share price, the company has continued to perform well from a financial and operational perspective.

    Following the acquisition and incorporation of Saracen, Northern Star became the sole owner of the iconic Super Pit and Mt Charlotte underground mine in Kalgoorlie. It also welcomed two new operations into its portfolio, Thunderbox and Carosue Damn in Western Australia.

    Northern Star said that the delivery of synergies from the merger in 2H FY21 resulted in “both savings and improved productivity at numerous levels”.

    In addition, the company highlighted that FY21 delivered “exceptional exploration results”, with Group resources increasing 15% to 56Moz and Group reserves increasing 8% to 21Moz over the 9 month period to 31 March 2021.

    “This expanded inventory will underpin the Company’s announced strategy to grow production to 2Moz per annum by FY26,” the company added.

    Northern Star declared a new dividend policy, targeting a total annual dividend payment of 20-30% of cash earnings.

    The company will be paying a final fully franked dividend of 9.5 cents per share, bringing its full-year payout to 19 cents per share.

    Management commentary

    Northern Star managing director Stuart Tonkin commented on the results of the enlarged company, saying:

    With the completion of the merger, we have established a simple, effective strategy based on our three production centres in world class locations.

    We have a clear five-year pathway to annual production of 2Moz a year with a strong emphasis on ensuring it is profitable growth.

    This strategy involves investing capital in those projects which will generate the strongest returns and actively managing our asset portfolio to maximise this outcome.

    We have an enviable asset base and world-class inventory with significant scope for further organic growth. And as these result show, we have the balance sheet and cash strength to unlock the full value of these opportunities in a way which will drive strong financial returns.

    What’s next for Northern Star?

    Northern Star forecasts FY22 production of 1.55-1.65Moz at an AISC between A$1,475 to A$1,575.

    Its long term goal is to achieve profitable production of 2Moz per annum by FY26.

    The Northern Star share price will go ex-dividend on Monday, 6 September, with the 9.5 cents per share dividend paid out on Wednesday, 29 September.

    The post Northern Star (ASX:NST) share price up after reporting 300% profit surge appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Northern Star right now?

    Before you consider Northern Star, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Northern Star wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3yfCLpJ

  • Medical Developments (ASX:MVP) share price falls on $13 million loss

    a doctor in white coat slumps against a window, head on hand, gazing down in dejection.

    The Medical Developments International (ASX: MVP) share price is lower after the company released its full-year results for FY21.

    At the time of writing, shares in the company are trading for $3.93 – down 2.48%. The ASX All Ordinaries Index (ASX: XAO), meanwhile, is 0.48% higher.

    Let’s take a closer look at today’s announcement.

    Medical Developments share price slumps despite 27% gross profit jump

    • Revenue increased 12.1% on the prior corresponding period (pcp) to $25.6 million and gross profit leaped 27.4% to $19.1 million.
    • A net profit after tax (NPAT) of $379,000 in FY20 turned into a $12.6 million loss for the period. This was driven mostly by a $9.6 million rise in administration expenses and a new $8.9 million impairment expense.
    • Net cash outflow from operating activities of $8.9 million.
    • Basic loss per share of 18.4 cents. In the pcp it was a gain of 0.58 cents per share.
    • No full-year dividend was paid, as was the case in FY20.

    What happened in FY21 for Medical Developments

    The first significant announcement of Medical Developments in FY21 was the announcement of its expansion into Europe. The Medical Developments share price jumped 14% on the news at the time. Chair David Williams called the news a “turning point” for the company.

    In October, Medical Developments appointed Brent McGregor as CEO of the company. He previously worked for CSL Limited (ASX: CSL).

    The company also acquired the distribution rights to its product in Australia in the financial year and implemented a capital raising scheme.

    Medical Developments also said the COVID pandemic affected sales of its pain relief and respiratory products. This was because fewer people were out and about (and therefore getting injured) and there was less cold and flu in the community due to border restrictions.

    What did management say?

    McGregor gave the following comments on today’s results.

    I am as confident as I was in November in the potential of MVP. Promising work has continued on our next generation product (“Selfie”) and we are beginning to think of other innovations to support strategic sales growth.

    Finally, I acknowledge the resilience and commitment of the (now international) MVP team who have worked extraordinarily hard in a difficult and uncertain time to maintain the supply of our important products to patients.

    What’s next for Medical Developments

    Looking forward, Medical Developments anticipates “strong sales growth” in FY22. It says it will be driven by its expanding European presence and a “renewed focus” on the Australian market.

    More updates will be provided at the October AGM.  Despite this outlook, the Medical Developments share price is slipping today.

    Medical Developments share price snapshot

    Over the past 12 months, the Medical Developments share price has decreased 34.2%. Year-to-date, it is down an even greater 40.8%.

    Medical Developments has a market capitalisation of $287 million.

    The post Medical Developments (ASX:MVP) share price falls on $13 million loss appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Medical Developments right now?

    Before you consider Medical Developments, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Medical Developments wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Marc Sidarous has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended CSL Ltd. and Medical Developments International Limited. The Motley Fool Australia owns shares of and has recommended Medical Developments International Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2XUkx0F

  • Bravura Solutions (ASX:BVS) share price plunges 17% on FY21 earnings

    share price dropping

    The Bravura Solutions Ltd (ASX: BVS) share price is plummeting following the release of the company’s earnings for financial year 2021 (FY21).

    Right now, The Bravura share price is $3.11, 17.29% lower than its previous closing price.

    Bravura share price slumps/jumps on 11% revenue decline

    Here’s how the wealth management, life insurance, and funds administration software provider performed through FY21:

    Barvura’s wealth management segment reported $160.1 million of revenue in FY21, 11% less than in FY20. Its funds administration segment’s revenue fell 12% to $82.9 million.

    According to Bravura, its wealth management segment’s revenue was lessened due to the effects COVID-19 had on its UK professional services work, but it was offset by contributions from FY20’s acquisitions.

    But not all was dire. Contracted reoccurring revenue in wealth management rose 30%.

    The company’s funds administration segment’s revenue was also impacted by the effects of COVID-19, but most of its reduced revenue was attributable to a lower mix of licence fees.

    Bravura ended the period with $73.6 million cash in the bank and $1.2 million of financial facilities used.

    What happened in FY21 for Bravura?

    FY21 was a productive period for Bravura and its share price.

    The company acquired Delta Financial Systems for $42 million in October 2020.

    It also signed an initial 7-year contract with Aware Super to allow the super fund to use Bravura’s Sonata Alta and Digital Advice.

    Bravura also signed or renewed contracts allowing the use of its software with a UK financial institution, a global investment bank, an Australian trustees business, an Australian superannuation fund, a New Zealand life insurance firm, a UK platform, and UK platforms for microservices.

    What did management say?

    Bravura’s CEO and managing director Tony Klim commented on the news driving the company’s share price today. He said:

    Despite what has undoubtedly been a challenging year, Bravura has achieved its guidance. The result reflects the unprecedented impact of COVID-19, particularly on UK project work and the sales pipeline. Despite the impact, we have responded to changing market conditions and evolved Bravura’s strategy to stay well ahead of client needs. This will lead to greater flexibility for clients in the speed of their implementation and will help them smooth their IT spend. In doing so, Bravura also expands its total addressable market and moves towards a higher proportion of contracted recurring revenue…

    Bravura continues to win new clients and has further developed its market credentials by investing in [research and development]. Confidence is expected to continue to improve as the COVID-19 vaccines roll out and is well placed to take advantage of improving client demand.

    What’s next for Bravura?

    Here’s what might drive the Bravura share price in FY22:

    As the COVID-19 pandemic is still affecting its key markets, the company warned its near term outlook is uncertain.

    However, it expects FY22 to bring growth of its net profits after tax in the mid-teens, relative to FY21’s adjusted profit after tax of $32.3 million.

    Bravura commented that its sales pipeline is strong and demand in the UK is starting to improve. The company gave a shoutout to the UK’s vaccine rollout, which it believes is helping to instil confidence. Additionally, the company believes there are large opportunities for its Sonata Alta offering in Australia.

    Over this financial year, Bravura believes its business will be driven by demand for software-as-a-service, microservices, cloud, and subscription-based services.

    Additionally, it has sped up its digital transformation through the pandemic and expects demand in the UK and South Africa to pick up in FY22 as projects delayed by COVID-19 resume.

    Bravura share price snapshot

    The Bravura share price has lost its gains for 2021 today. Right now, it’s 1.8% lower than it was at the start of this year. It is also 28% lower than it was this time last year.

    The post Bravura Solutions (ASX:BVS) share price plunges 17% on FY21 earnings appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Bravura Solutions right now?

    Before you consider Bravura Solutions, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Bravura Solutions wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned.

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Bravura Solutions Ltd. The Motley Fool Australia owns shares of and has recommended Bravura Solutions Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3gxCHvx

  • What happened to the Blackmores (ASX:BKL) share price last earnings season?

    blackmores share price

    The Blackmores Limited (ASX: BKL) share price has climbed just over 2% in the last month. In comparison, the S&P/ASX 200 index (ASX: XJO) is up 1.5% over the same period.

    In early trading today, the Blackmores share price is up 0.56% at $78.97 apiece.

    As the nutritional supplement company prepares to report its FY21 earnings on Thursday, let’s take a look at what happened to the Blackmores share price last earnings season back in February.

    What did Blackmores deliver in its half year results?

    Blackmores detailed a pattern of growth in its FY21 half-year results in February, including:

    • Revenue of $302.6 million that grew 4% on a constant currency basis
    • International and China revenue growth of 13% and 25% respectively
    • 10% decline in ANZ revenue to $148 million
    • Net profit after tax (NPAT) of $19.4 million, an 8% increase from the year prior
    • Fully franked interim dividend of 29 cents per share.

    While Blackmores did not shed any colour on guidance expectations, it did state that revenue in H2 would be “slightly lower” than H1.

    Furthermore, it announced it would hand back $2.4 million of the $10.4 million in Jobkeeper assistance provided by the government for COVID-19 relief.

    How did the Blackmores share price react?

    The results were well received by the market, as investors drove the Blackmores share price north in the days following the announcement.

    Blackmores shares climbed around 10% in the two days after the report, peaking at $81.41 before retracing to $76.57 the week after.

    Afterwards, the Blackmores share price regained momentum and again shot back up near its 52-week high, closing at $87.19 on 15 March.

    One month after its FY21 half-year results, Blackmores shares closed at $82.92, a 12% climb, despite no other market-sensitive information during this time.

    Considering how its earnings growth was a positive to the Blackmores share price in February, investors will no doubt hope for a similar performance this time around.

    This is especially true when factoring the recent run-up on the charts the company’s shares have exhibited since May.

    At the current Blackmores share price, the company has a market capitalisation of $1.5 billion.

    The post What happened to the Blackmores (ASX:BKL) share price last earnings season? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Blackmores right now?

    Before you consider Blackmores, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Blackmores wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    The author Zach Bristow has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Blackmores Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3muhl64

  • Whispir (ASX:WSP) share price up 6% on solid FY21 result

    a happy investor with wide mouth expression grasps a computer screen that shows a rising line charting the upward trend of a share price

    The Whispir Ltd (ASX: WSP) share price is climbing this morning. This follows the cloud-based communications company releasing its full-year results for the 2021 financial year.

    At the time of writing, Whispir shares are up 5.93% to $2.50. It has been a challenging year for the Whispir share price. It’s dropped 36% since the beginning of 2021. However, in the past 5 days, the company’s value has crept up 10.8%.

    Whispir share price in focus following double digit revenue growth

    Here are the highlights from the company’s full-year results:

    • Annualised recurring revenue up 28.5% to $53.6 million
    • Recurring revenue now represents 96.7% of total revenue, up from 95.6% in FY20
    • FY21 revenue of $47.7 million, up 22% from the prior corresponding period
    • Operating earnings before interest, tax, depreciation, and amortisation (EBITDA) loss of $4.7 million, up from a loss of $5.6 million in FY20
    • Net loss after tax of $9.65 million, a 2% improvement on FY20
    • Net new customers of 171 during the financial year, bringing the total to 801 in FY21

    What happened in FY21 for Whispir

    The market is responding positively to the Whispir share price on Wednesday after the company released its full-year results for FY21. Growth metrics across the board were solid, with most financial measures indicating an increase of 20% to 30% from the prior year.

    According to the release, Whispir achieved total revenue of $47.7 million in FY21 – representing an increase of 22% from the previous year. Similarly, annualised recurring revenue grew by 28.5% to $53.6 million.

    This growth was underpinned by the increased usage of existing customers. In addition, new customers — to the tune of 171 across Whispir’s operating regions — pushed the company’s top-line result higher.

    Looking at the geographic breakdown of performance — Australia and New Zealand delivered growth of 29% to $39.7 million. Meanwhile, the company’s Asia and North America segments shrunk by 1% and 12% respectively.

    Fortunately, the latter geographies are smaller in revenue terms to begin with. However, the challenging international growth environment may be an eyebrow-raiser for some investors.

    According to Whispir, the challenging international environment reflects the impacts of COVID-19 and a pivot in its marketing strategy in North America during the year.

    What did management say?

    Commenting on the result, Whispir Chief Executive Officer Jeromy Wells said:

    During FY21 the Whispir platform continued to scale with ARR increasing 28.5% and largely driven by increased usage amongst existing customers who are extracting more value from the platform, as well as new customer sign-ups across each region.

    Additionally, regarding the company’s future opportunities, Mr Wells said:

    We see significant opportunity for growth in the underserved SME and SMB segments identified in North America. We have successfully delivered new customer growth in the recent half as a result of adding more capability to execute against our strategic plan and our refined persona-led strategy.

    What’s next for Whispir?

    Looking ahead, Whispir intends to focus on increasing customer numbers, platform usage, and revenue across its operating regions. While the pandemic has produced a headwind in customer wins in Asia, it has also accelerated the digitisation of many businesses.

    Additionally, the company provided guidance for FY22 for four important metrics:

    • Year-end annual recurring revenue between $65.4 million and $70 million, representing growth of 22% to 31%
    • Revenue between $57.2 million and $60.2 million, representing growth of 20% to 26%
    • Operating EBITDA loss between $15.5 million and $13 million
    • Research and development spend between $17.5 million and $18 million, representing 70% to 80% growth

    Whispir share price snapshot

    Unfortunately for shareholders, the Whispir share price has underperformed the S&P/ASX 200 Index (ASX: XJO) by a significant margin over the past year.

    The benchmark index returned 21.8% as it recovered from the crash in March 2020. Meanwhile, shares in the communication platform have tumbled 50.6% during the past year.

    Whispir currently holds a market capitalisation of $275.9 million.

    The post Whispir (ASX:WSP) share price up 6% on solid FY21 result appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Whispir right now?

    Before you consider Whispir, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Whispir wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Mitchell Lawler has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Whispir Ltd. The Motley Fool Australia has recommended Whispir Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3sGU0ze

  • IDP Education (ASX:IEL) share price higher despite 36% FY21 profit decline

    The IDP Education Ltd (ASX: IEL) share price is on the move on Wednesday morning following the release of its full year results.

    In early trade, the language testing and student placement company’s shares were down as much as 9% to $25.24 before rebounding to be up 1%.

    IDP Education share price higher after 36% profit decline

    • Revenue down 10% (or 5% in constant currency) to $528.7 million
    • English Language Testing revenue flat at $325.6 million
    • Student Placement revenue down 25% to $143.3 million
    • Earnings before interest, tax, depreciation and amortisation (EBITDA) down 330% to $145.2 million
    • Adjusted net profit after tax dropped 36% to $45 million

    What happened in FY 2021 for IDP Education?

    For the 12 months ended 30 June, IDP Education reported a 10% reduction in revenue to $528.7 million and a 36% decline in adjusted net profit after tax to $45 million. This reflects ongoing operational disruptions caused by COVID-19 related government restrictions.

    Positively, the company’s IELTS volumes still managed to grow 5% year on year despite COVID-19. This led to revenues in the English Language Testing business remaining flat on a reported basis and growing 8% in constant currency. This appears to be supporting the IDP Education share price today.

    The main impacts were felt in the Student Placement business. Australian revenues fell 34% and Multi-Destination revenues in the business fell 17% on a reported basis and 11% in constant currency. Management notes that placements to Australia were hardest hit, falling 40% versus last year. International border closures meant student enrolments were largely limited to those willing to commence their studies online.

    One positive was the company’s Digital Marketing business, which saw its revenue rise by 8% to $30 million. This was thanks to its institutional clients looking to IDP’s global digital platform for marketing and data insights.

    At the end of the period, the company’s cash balance stood at $307 million. This was largely unchanged year on year.

    What did management say?

    IDP’s Chief Executive Officer and Managing Director, Andrew Barkla, was pleased with the company’s resilient performance.

    He said: “Our diverse business model and long-term strategy allowed us to decisively navigate the disruptions of the past sixteen months. Importantly, our business took critical steps during the year to further strengthen our leadership position in preparing the industry for recovery.”

    “IELTS demonstrated its through-the-cycle appeal as volumes rebounded despite ongoing restrictions across our global network,” he added.

    What’s next for IDP Education?

    Unsurprisingly, no guidance has been provided for FY 2022. However, Mr Barkla appears positive that the company is well-placed for the future after five years of transforming the business.

    He said: “IDP took another significant step in FY21 to deliver on our vision of building a global platform and connected community. By bringing together human connections and digital innovation, we are guiding people on their journey to achieve lifelong learning and global career aspirations.”

    “Over the past five years we have transformed our business and built a digital platform to complement our trusted human connections. With our people, customers and institutions now on one global platform, our stakeholders have begun to benefit from even stronger support at all stages of their journey.”

    “Our recent acquisition of the British Council’s IELTS operations in India, along with investments in digital marketing and the IELTS technology platform have strategically positioned us to grow IELTS market share going forward,” the CEO said.

    The IDP Education share price is up 35% in 2021.

    The post IDP Education (ASX:IEL) share price higher despite 36% FY21 profit decline appeared first on The Motley Fool Australia.

    Should you invest $1,000 in IDP right now?

    Before you consider IDP, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and IDP wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Idp Education Pty Ltd. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3msOM9d

  • Nine Entertainment (ASX:NEC) share price slumps 7% despite earnings surge

    A young woman with tattoos puts both thumbs down and scrunches her face with the bad news.

    The Nine Entertainment Co Holdings Ltd (ASX: NEC) share price has fallen more than 7% at the open after the group’s latest full-year results release.

    Nine Entertainment share price slumps despite earnings surge

    Some of the key takeaways from today’s result for the year ended 30 June 2021 (FY21) include:

    What happened in FY21 for Nine Entertainment?

    Prior to today’s move, the Nine Entertainment share price had rocketed 69.3% higher in the last 12 months. It was a big year for the Aussie media group with the launch of Stan Sport and the completion of agreements with major digital platforms like Facebook (NASDAQ: FB) and Alphabet (ASX:GOOGL)’s Google.

    Nine reported ad market growth amid a focus on brand exposure from advertisers. The Aussie media group also noted growth in revenue and profitability for its TV Combined segment and strong audience results across all platforms.

    Significant revenue growth combined with prudent cost management saw Nine generate a strong pro forma operating cash flow of $346.2 million and reduce net leverage to 0.4 times during the year.

    What did management say?

    Nine Entertainment CEO Mike Sneesby had the following to say this morning:

    After a year which began in the depths of COVID, we are pleased to report 43% growth in EBITDA for FY21. Whilst this growth was consistent across both halves, the drivers in each half were quite different, highlighting the strength of Nine’s mix of advertising and subscription-based assets.

    While the past year has proven challenging, we have been able to establish the base to execute on our longer term strategy.

    We are starting FY22 with strong momentum across all of our businesses — in terms of audiences and revenue, advertising and subscription. With the foundation of Nine’s unique assets, strong cash flows and a supportive Board, we have a clear vision for the future as Australia’s Media Company.

    What’s next for Nine and its share price?

    Nine’s metro free to air (FTA) ad revenue is expected to be up almost 20% in the FY22 year to date compared to the same quarter last year.

    The Nine Entertainment share price is one to watch as the media group forecasts FY22 Publishing EBITDA of $30 million to $40 million. In its subscription business, Stan’s revenue run rate is more than $340 million with total FY22 costs expected at the lower end of the previous $70 million to $90 million guidance range.

    The Nine Entertainment share price has climbed 19% higher in 2021 after accounting for Wednesday morning’s slump.

    The post Nine Entertainment (ASX:NEC) share price slumps 7% despite earnings surge appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Nine Entertainment right now?

    Before you consider Nine Entertainment, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Nine Entertainment wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Suzanne Frey, an executive at Alphabet, is a member of The Motley Fool’s board of directors. Randi Zuckerberg, a former director of market development and spokeswoman for Facebook and sister to its CEO, Mark Zuckerberg, is a member of The Motley Fool’s board of directors. Motley Fool contributor Ken Hall has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Alphabet (A shares), Alphabet (C shares), and Facebook. The Motley Fool Australia has recommended Alphabet (A shares), Alphabet (C shares), and Facebook. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3DiaB11

  • How the BetMakers (ASX:BET) share price responded last reporting season

    excitement surrounding asx share price rise represented by man holding slip of paper and making happy, fist up gesture

    The BetMakers Technology Group Ltd (ASX: BET) share price will be on watch this reporting season.

    With the betting company slated to report its earnings for FY21 on Thursday, investors will be interested to know how the company responded last year.

    Let’s take a look at how the BetMakers share price reacted last earnings season.

    FY20 results spurs BetMakers share price

    Initially, the BetMakers share price did not raise any eyebrows last reporting season.

    Shares in the wagering company were relatively flat immediately after releasing its full-year results for FY20.

    However, there was significant buying interest for shares in BetMakers after investors had time to interpret the company’s report.

    A couple of days after reporting, buyers flocked for shares in the wagering company, sending its share price soaring more than 20% higher.

    Highlights from the company’s FY20 report included;

    • Revenue of $9.2 million, up 34% from the prior corresponding period (pcp)
    • 74% increase in gross profit of $6.3 million
    • $2.9 million increase in EBITDA of $0.8 million for FY20

    Snapshot of Betmakers share price

    It has been a landmark year for the BetMakers share price thus far.

    Shares in the wagering company have soared more than 85% since the start of 2021.

    There have been several catalysts fuelling the BetMakers share price.

    Most recently, shares in the wagering company received a boost after fixed-odds wagering was legalised in New Jersey.

    The legalisation of fixed-odds wagering bodes well for the company’s US ambitions.  BetMakers currently holds a 10 year agreement to deliver and manage fixed-odds thoroughbred horse racing in New Jersey.

    The BetMakers share price also received a boost in late July after the company released a promising quarterly update.

    The wagering company recorded $8.9 million in cash receipts for the fourth quarter of FY21, a 71% increase on the previous quarter.

    BetMakers attributed the strong growth to improved sentiment in the Australian market and positive results from its international expansion.

    In addition, the company cited its recent acquisition of Sportech PLC for enhancing the company’s revenue-generating opportunities.

    Investors will be keen to see if BetMakers can replicate its strong growth when the company releases its full-year results for FY21 tomorrow.

    The post How the BetMakers (ASX:BET) share price responded last reporting season appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BetMakers right now?

    Before you consider BetMakers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BetMakers wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Motley Fool contributor Nikhil Gangaram has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Betmakers Technology Group Ltd. The Motley Fool Australia has recommended Betmakers Technology Group Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3kfxeKY

  • Is Tesla Bot a catalyst for Tesla stock?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

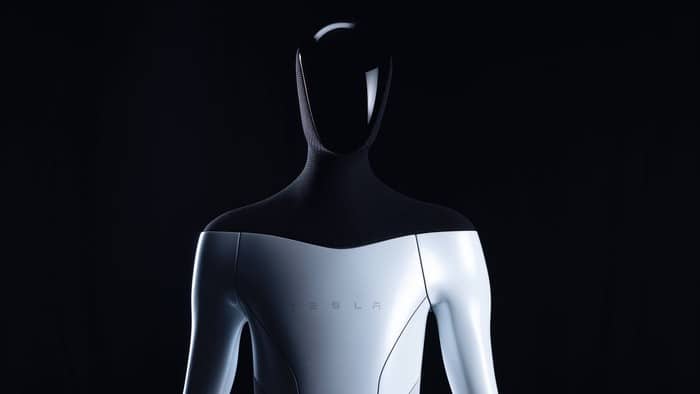
    tesla bot, artificial intelligence

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    One of the surprise announcements at Tesla‘s (NASDAQ: TSLA) artificial intelligence event last week was a humanoid robot: Tesla Bot. Despite unveiling it with a dancing human in a robot costume, it was not a joke.

    The electric car and green energy company (and now a robotics company?) hopes to have a prototype by next year. The humanoid bot will aim to help eliminate dangerous, repetitive, and boring tasks, Tesla CEO Elon Musk said after Tesla Bot was announced.

    With such an exciting potential product, should investors start pricing this into the stock?

    Absolutely not.

    Meet Tesla Bot

    With the Tesla Bot still in early development, specs on the new product were unsurprisingly sparse. Tesla did say it would be 5 feet 8 inches tall, weigh 125 pounds, walk at a speed of 5 mph, and be able to deadlift 150 pounds.

    While Tesla Bot may seem “out there,” Musk said the company would be essentially employing technology it’s already developing for its vehicles.

    “Tesla is arguably the world’s biggest robotics company,” Musk said during the event, “because our cars are like semi-sentient robots on wheels.” Tech used in its cars that could be utilized in Tesla Bot would include its neural nets for recognizing the environment, sensors, batteries, and actuators.

    “It’s intended to be friendly, of course,” Musk said. Even more, there are precautions in place: The company will set it at a mechanical level so that you can run away from it and, if needed, “most likely” overpower it, the CEO added. Whew. Thank you, Tesla!

    Why investors should be skeptical

    Analysts seem to be largely ignoring Tesla Bot as a potential driver for the stock — and they’re right to do so.

    Wedbush analyst Daniel Ives even called Tesla Bot “an absolute head scratcher.” Meanwhile, Wells Fargo analyst Colin Langan says the company’s 2022 target timeline for a prototype robot may be too optimistic. Neither of them increased their price targets for Tesla stock in response to the news.

    The analysts are right to be raising eyebrows. Investors shouldn’t start pricing anything in until there’s a clear path to revenue and profits. If anything, the Tesla Bot could be viewed as a distraction and could be a net negative for the stock. But given the company’s history of doing extraordinary things and exceeding expectations, investors may want to at least refrain from counting the project against Tesla. Not only could it potentially turn into a driver for the business someday but it may be the type of project needed for Tesla to attract some of the world’s greatest minds in the artificial intelligence space.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Is Tesla Bot a catalyst for Tesla stock? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Tesla right now?

    Before you consider Tesla, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Tesla wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of August 16th 2021

    More reading

    Daniel Sparks has no position in any of the stocks mentioned. Wells Fargo is an advertising partner of The Ascent, a Motley Fool company. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Tesla. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3grSYSU