Category: Stock Market

  • Why Tesla stock edged higher on Thursday

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.
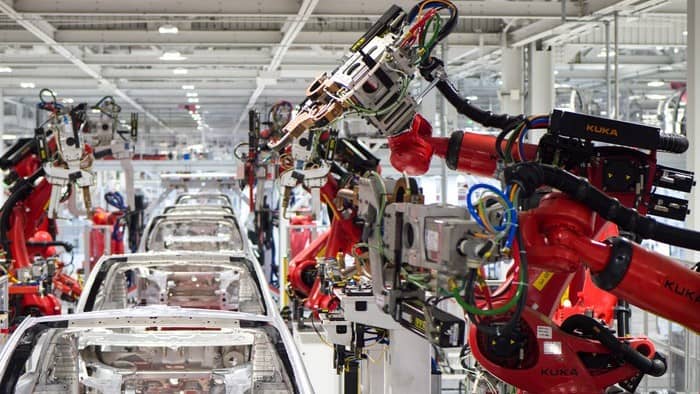
    manufacturing of Tesla

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    What happened

    Shares of Tesla (NASDAQ: TSLA) rose 2.1% at one point on Thursday. As of 12:45 p.m. EDT, however, the stock was up 1.3%.

    The stock’s gain is likely driven by a generally bullish day for many growth stocks, as well as news circulating about strong deliveries coming from Tesla’s China factory in July.

    So what

    A few days ago, concerns mounted about a drop in China-made vehicles being delivered to customers in the market. Though its 32,968 total vehicles made for delivery during the month were strong, 24,347 of these vehicles were exported. This means that local deliveries decreased 69% from levels in June. 

    But we’re learning on Thursday that there’s no reason to fret about deliveries in China. “Tesla makes cars for export in first half of quarter & for local market in second half,” said Tesla CEO Elon Musk on Twitter in response to a tweet about the company’s production trends in the important market.

    With this context, investors should spend more time focusing on total vehicles made in China in a given month rather than where they are delivered. Local deliveries in a given month aren’t exactly indicative of orders if Tesla bases exporting decisions on quarterly timing rather than order trends.

    Meanwhile, with many growth stocks seeing gains on Thursday greater than the S&P 500‘s 0.12% increase as of this writing, this market trend could be helping Tesla shares as well.

    Now what

    For the full year, Tesla is aiming to grow its vehicle deliveries more than 50% year over year. The company’s China factory, which accounted for more than 40% of Tesla’s installed manufacturing capacity in Q2, is key to achieving this target.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Why Tesla stock edged higher on Thursday appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Tesla right now?

    Before you consider Tesla, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Tesla wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Daniel Sparks has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Tesla and Twitter. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/37E1zgw
  • Its been a great week for the ANZ (ASX:ANZ) share price so far

    ASX bank shares buy A young boy in a business suit giving thumbs up with piggy banks and coin piles

    The Australia and New Zealand Banking Group Limited (ASX: ANZ) share price has had a great week thus far.

    The ANZ share price opened the week at $28.60 a share. At the close of yesterday’s trading session, shares in the banking giant finished off at $29.35.

    This translates to a 2.55% increase in the ANZ share price within a week.

    In comparison, the  S&P/ASX 200 Index (ASX: XJO) has only managed to crawl 0.6% higher for the week.

    It’s not very common to see the share price of a big bank like ANZ outperforming the broader index.

    So, let’s take a look at what’s pushing the ANZ share price higher this week.

    What’s been fueling the ANZ share price?

    There have been several catalysts that have helped propel the ANZ share price this week.

    Firstly, a strong full year result by rival Commonwealth Bank of Australia (ASX: CBA) helped boost the ANZ share price.

    A strong result from ANZ’s rival helped fuel investor sentiment towards the banking sector.

    A second catalyst that boosted the ANZ share price this week was the appointment of a new Chief Financial Officer (CFO).

    ANZ’s management highlighted Mr Faruqui’s accomplishments and experience, painting a positive outlook for the bank’s future.

    Snapshot of the ANZ share price

    In addition to a strong week, the ANZ share price has also had a stellar year thus far.

    Since the start of the year, shares in the banking giant have soared more than 28.5% in 2021.

    Despite their impressive gains this year, the ANZ share price still offers investors a decent dividend yield.

    According to a recent note from broker Bell Potter, the potential return of the ANZ share price remains attractive.

    Analysts from the broker initiated a buy rating on the bank and placed a $30 price target on its shares.

    The broker also forecasts ANZ to pay out a fully franked dividend per share of 140 cents in FY 2021. In addition, analysts forecast a payout of 146 cents in FY 2022 and 154 cents in FY 2023.

    These figures reflect a dividend yield of 5%, 5.2%, and 5.5%, respectively.

    As a result, the ANZ share price will receive extra attention this reporting season.

    ANZ is expected to release its results for the financial year on Wednesday the 18th of August.

    The post Its been a great week for the ANZ (ASX:ANZ) share price so far appeared first on The Motley Fool Australia.

    Should you invest $1,000 in ANZ right now?

    Before you consider ANZ, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and ANZ wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Nikhil Gangaram has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2UegQBx

  • Why the Xero (ASX:XRO) share price has climbed 5% in a month

    A cloud with a blue arrow pointing upwards through its middle symbolising a rising asx share price

    The Xero Limited (ASX: XRO) share price has moved 5% higher in the past month. This comes despite no new price-sensitive news from the cloud accounting platform provider since its FY21 results in mid-May.

    At Thursday’s market close, Xero shares finished the day down 2.71% to $141.59.

    What’s been driving Xero shares higher?

    A possible catalyst for the recent rise in the Xero share price could be a note released by a leading broker last Wednesday.

    According to Goldman Sachs, its analysts are viewing Xero with a favourable outlook.

    The multinational investment house acknowledged Xero’s recent launch of its app store across the Australia, New Zealand and United Kingdom markets. It said the company is focused on achieving international expansion through monetising the strong position of its app store.

    Goldman Sachs believes the total addressable market for the Xero app store to be NZ$1.4 billion (A$1.34 billion).

    Furthermore, the broker expects Xero to double its revenue across FY21 to FY24 with a 26% compound annual growth rate. In its FY21 financial results ending 31 March, Xero highlighted operating revenue coming in at $848.8 million, up 18% year on year.

    In addition, the company’s subscriber base grew to 2.74 million subscribers, up 456,000 year on year.

    Net profit stood at $19.8 million, an increase of $16.4 million year on year.

    In light of this, Goldman Sachs put a “buy” rating on Xero shares, raising its 12-month price target by 9.3% to $165.00. Based on the current Xero share price, this implies an upside of approximately 16.5%.

    Xero is scheduled to report its FY22 half-year results on 11 November 2021.

    Foolish takeaway

    Since last August, Xero shares climbed higher from the $90 mark to almost touch $160 in December 2020. Investors would have enjoyed returns of around 75% in just a few months. However, following its meteoric rise, the Xero share price has largely moved in circles. Year to date, Xero shares are down 3%.

    As the twentieth largest company on the ASX, Xero has a market capitalisation of roughly $21 billion.

    The post Why the Xero (ASX:XRO) share price has climbed 5% in a month appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Xero right now?

    Before you consider Xero, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Xero wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Xero. The Motley Fool Australia owns shares of and has recommended Xero. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3jNZdkB

  • One Delta lockdown winner and 2 other rocketing ASX shares

    a happy investor with a wide smile points to a graph that shows an upward trending share price

    If you’re looking for inspiration for your next ASX share investment, it is often useful to see what the professionals are making money out of.

    Australian fund Cyan C3G gained 1.8% in July and remains a firm believer in growth shares.

    “Most recently the growth and tech sectors have received support on the back of the announcement that Afterpay Ltd (ASX: APT) will be acquired by Square Inc (NYSE: SQ) for $39 billion,” portfolio manager Dean Fergie said in a memo to clients.

    “This illustrates that fast-growing fintech businesses such as Square Inc are willing to buy aggressively to improve [their] strategic position as they continue to disrupt traditional industry incumbents.”

    Three particular ASX shares within the Cyan portfolio leapt ahead last month. Despite the ballooning valuations, Fergie’s team will continue to keep the faith to call them “long-term holdings”:

    A true Delta lockdown winner

    Fergie previously told The Motley Fool how fond he was of Maggie Beer Holdings Ltd (ASX: MBH), and his belief was rewarded handsomely.

    The gourmet food ASX share returned 6% over July.

    It was no coincidence that demand for its goods and services accelerated during the ongoing COVID-19 resurgence.

    In great timing, Maggie Beer had just completed its acquisition of online business The Hamper Emporium.

    “Particularly considering the extended periods of domestic lockdown, the online element of their hamper business is looking increasingly attractive,” said Fergie.

    “The market now appears to be realising the benefits, synergies and strengthened business model of the combined group.”

    Maggie Beer shares are arguably not super expensive though, with the price still more than 16% lower than when the year started.

    Aussie studio about to release blockbusters

    Fergie has also been on the record as a fan of Playside Studios Ltd (ASX: PLY).

    And that loyalty brought his fund a stunning 40% during July.

    “This Melbourne based game developer, which listed in December last year, delivered solid cashflow performance and proved that its business model, which combines work for hire and original IP games development, is performing outstandingly.”

    And what’s better is that Fergie anticipates more positive news coming over the next year or so.

    “The company has an exciting 12 months ahead with the upcoming release of several new games including titles based on blockbuster movies Legally Blonde and The Godfather which should contribute to a material uplift in revenues in FY22.”

    Similar to Maggie Beer, despite the sensational climb in July, Playside shares are still down more than 11% for the year.

    Raiz the roof, says fund manager

    The micro-investing app RAIZ Invest Ltd (ASX: RZI) had a sensational 28 July, when the share price rocketed 8%.

    The boost was thanks to a record quarterly result.

    “Raiz achieved record results for global active customers, funds under management (FUM) and revenue,” reported The Motley Fool’s Kerry Sun.

    “Global active customers totalled 456,927 at quarter-end, an increase of 86.7% on the prior corresponding period.”

    All up Raiz shares stepped up 10% for the month of July.

    “It is comfortably on track to exceed FUM of $1 billion by the close of 2021, representing a doubling in size over 12 months,” said Fergie.

    “It remains one of our most high-conviction positions as we find the company’s consumer product offering very compelling.”

    The fintech had another upward spike in its stock price last week after it revealed positive July performance metrics.

    Raiz shares are up a stunning 90% for the year.

    The post One Delta lockdown winner and 2 other rocketing ASX shares appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tony Yoo owns shares of AFTERPAY T FPO and Square. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended AFTERPAY T FPO and Square. The Motley Fool Australia owns shares of and has recommended AFTERPAY T FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3CN4yBE

  • It’s been a good month so far for the Westpac (ASX:WBC) share price

    happy woman throws arms in the air

    The Westpac Banking Corp (ASX: WBC) share price has been a very positive performer in August.

    Since the start of the month, the banking giant’s shares have risen 5%.

    This means the Westpac share price is now up by 31% year to date, which is more than double the return of the S&P/ASX 200 Index (ASX: XJO).

    Why is the Westpac share price charging higher in August?

    Investors have been bidding the Westpac share price higher this month for a number of reasons.

    One of those was the release of the Commonwealth Bank of Australia (ASX: CBA) full year results earlier this week.

    The strength of this result and the significantly largely than expected capital return gave investor sentiment in the banking sector a major boost.

    What else?

    Also giving the Westpac share price a boost this month was news that the bank is selling its Australian Life Insurance business.

    Westpac has agreed to sell Westpac Life Insurance Services to TAL Dai-ichi Life Australia for $900 million.

    The two parties have also entered an exclusive 20-year strategic alliance for the provision of life insurance products to Westpac’s Australian customers. This will generate ongoing payments to Westpac.

    Management notes that this sale is part of its strategy of simplifying the bank.

    Is it too late to invest?

    One leading broker that still sees a lot of value in Westpac shares is Morgans. Earlier this week, the broker retained its add rating and $29.50 price target on its shares.

    Based on the current Westpac share price of $25.76, this implies potential upside of 14.5% over the next 12 months.

    Morgans is also forecasting attractive fully franked dividend yields of 4.3% in FY 2021 and then 5% in FY 2022. Combined, this means the broker expects Westpac shares to provide investors with a return of ~19% over the next 12 months.

    The post It’s been a good month so far for the Westpac (ASX:WBC) share price appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Westpac right now?

    Before you consider Westpac, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Westpac wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro owns shares of Westpac Banking Corporation. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/37DImvg

  • 2 retail ASX dividend shares with large yields

    shoes asx share price represented by white shoes against pink and blue background AX1 share price downgrade

    There are some ASX dividend shares in the retail sector that may be interesting considerations for their large yields.

    The strong market conditions for retailers may not be as strong in FY22 as FY21, but they are still expected to provide large cash payouts for shareholders.

    These two businesses may have big dividend yields for the next 12 months:

    Accent Group Ltd (ASX: AX1)

    This business is one of the leading shoe retailers in the country. It sells footwear through a number of different brands in Australia and New Zealand (some are owned, some are exclusively distributed): Platypus, Hype, Stylerunner, Trybe, The Athlete’s Foot, Glue store, Skechers, Vans, Dr Martens and so on.

    Accent is always on the look for ways to increase its brand distribution. It recently bought the Glue Store retail business, and the wholesale and distribution brands, of Next Athleisure for $13 million. It came with annual sales of $90 million, including $16.6 million of online sales. This provides an opportunity to increase exposure in the youth apparel segment.

    Accent is rolling out more stores across a number of its brands, whilst also investing in its digital presence.

    Accent has grown rapidly in recent reporting periods. FY21 first half earnings before interest and tax (EBIT) grew by 47.3% to $81.8 million, whilst earnings per share (EPS) went up 56.9% to 9.76 cents. Digital sales soared 110% to $108.1 million, representing 22.3% of total sales.

    The profit growth allowed the retail ASX dividend share’s board to grow the interim dividend by 52.4% to 8 cents per share.

    Commenting on its dividend and profit growth aspirations, the Accent CEO Daniel Agostinelli said:

    With long-term objectives and incentives linked to driving at least 10% compound EPS growth, Accent continues to be defined by strong cash conversion and the consistently strong returns it delivers on shareholders’ funds.

    According to Commsec, Accent could pay a grossed-up dividend yield of 6.6% in FY22.

    Adairs Ltd (ASX: ADH)

    Adairs is another business that’s growing quickly with a tendency to pay a high dividend.

    The first half of FY21 saw Adairs’ total sales rise 34.8% to $243 million, with online sales jumping 163.2% to $90.2 million (representing 37% of total sales).

    Profit margin growth helped the bottom line rise even faster. The overall gross profit margin improved 545 basis points, underlying EBIT surged 166% to $60.2 million and statutory net profit went up 233.4% to $43.9 million. This helped EPS grow to 25.9 cents (up from 7.8 cents).

    The Adairs board decided to pay an interim dividend of 13 cents per share.

    Adairs is investing in a number of areas to improve its financial performance in future years such as opening bigger stores (which are more profitable) and seeking to increase Mocka’s market share in Australia.

    The new national distribution centre in Melbourne is another part of the plan. This will help stock flow, online order fulfilment, improve stock availability and save an annual $3.5 million of costs once fully operational.

    According to Commsec, Adairs is projected to pay a grossed-up dividend yield of 8.5%.

    The post 2 retail ASX dividend shares with large yields appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Adairs right now?

    Before you consider Adairs, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Adairs wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended ADAIRS FPO. The Motley Fool Australia owns shares of and has recommended ADAIRS FPO. The Motley Fool Australia has recommended Accent Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/37B1All

  • August has been a good month for the IAG (ASX:IAG) share price

    happy woman cheering with hands in air

    The Insurance Australia Group Ltd (ASX: IAG) share price has been on fire in August. Shares in the Aussie insurer have climbed 12.4% higher since the start of the month to close at $5.45 on Thursday afternoon.

    The IAG share price is soaring this month

    The biggest news this month was IAG’s full-year results release on Wednesday.

    Australia’s largest general insurance company reported a 170% jump in cash earnings to $747 million as its insurance profit climbed 35.9% to $1,007 million.

    However, IAG reported a 130 basis point drop in its underlying insurance margin to 14.7% and a $427 million net loss after tax.

    The IAG share price started Wednesday’s trade strongly following the result. It wasn’t a good day for investors though as IAG shares closed down 2.7% at $5.15 per share.

    That indicates Wednesday’s earnings result was far from the only explanation for the recent share price gains.

    Interestingly, the IAG share price shot 6.0% higher in Thursday’s trade. That was despite no further announcements from the Aussie insurer following the full-year result.

    Yesterday’s strong gains may have something to do with a different Aussie insurer. The QBE Insurance Group Ltd (ASX: QBE) share price jumped 8.1% on Thursday to close at $12.51 per share – just shy of a 52-week high.

    That came after the ASX insurer reported its half-year financial results with a stronger underwriting result and interim dividend. QBE reported an adjusted cash profit up US$463 million compared to a US$66 million loss in 1H 2020.

    Investors appeared to also bid up the IAG share price as both Aussie insurance shares enjoyed a strong day in the markets.

    Foolish takeaway

    The August reporting season is always an interesting time to watch ASX shares. The IAG share price saw a muted reaction to its own results before flying higher on the back of QBE’s increased dividends.

    Investors will be hoping for further gains to close out a strong month for the Aussie insurer.

    The post August has been a good month for the IAG (ASX:IAG) share price appeared first on The Motley Fool Australia.

    Should you invest $1,000 in IAG right now?

    Before you consider IAG, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and IAG wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Ken Hall has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Insurance Australia Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2VPQaI0

  • What is the outlook for the Fortescue (ASX:FMG) share price?

    Man with binoculars standing on edge of building looking into distance

    The Fortescue Metals Group Limited (ASX: FMG) share price has had a tough 2021 so far. Shares in the major iron ore miner have fallen 9.2% to close at $22.52 per share on Thursday.

    Investors will be hoping for a turnaround in fortunes before the year is out. So, what’s the outlook for the ASX mining giant in 2021?

    What’s in store for the Fortescue share price?

    Let’s start with the current state of play. Shares in the Aussie miner are still up 26.1% in the past 12 months and 356.8% in the last 5 years, not including the role that a hefty dividend plays in total returns. So, it’s not all doom and gloom for shareholders right now.

    However, a falling iron ore price, largely driven by weaker Chinese demand, has hurt the Fortescue share price in recent weeks. China is a major buyer of Aussie iron ore as a key input into the steel production process. That means when China decides to stop buying, ASX iron ore shares like Fortescue tend to perform poorly.

    One leading broker thinks that the outlook for the Aussie mining share isn’t all bad. A recent equity research report from JP Morgan reinstated a $30 per share price target and overweight rating. Given the current $22.52 share price, this implies a potential 33.2% upside based on the broker’s target.

    JP Morgan analysts cited Fortescue’s strong Q4 2021 results and a net cash position above their own and market expectations. While the Fortescue share price has been under pressure in 2021, clearly some in the market think there is still an attractive investment thesis to be made.

    Foolish takeaway

    The Fortescue share price has been on a sustained bull run for a number of years now. While 2021 hasn’t been panning out as investors would have hoped, the Aussie mining share is still up 26.1% in the last 12 months and trading on an 11.0% dividend yield.

    The post What is the outlook for the Fortescue (ASX:FMG) share price? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Fortescue right now?

    Before you consider Fortescue, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Fortescue wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Ken Hall has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3lWDSbx

  • 3 excellent ASX tech shares that could be buys

    Monadelphous share price rio tinto A small rocket take off from a laptop, indicating a share price surge

    If you’re looking for growth shares to buy, then the tech sector could be a great place to start. At this side of the market, there are a number of companies with the potential to grow materially over the next decade.

    With that in mind, I have picked out three top tech shares that could be buys. Here’s what you need to know about them:

    BetaShares Global Cybersecurity ETF (ASX: HACK)

    The first option to look at is actually an ETF that gives you access to a group of tech shares. The BetaShares Global Cybersecurity ETF aims to track the performance of an index that provides investors with access to the leaders in the growing global cybersecurity sector. Among the 40 companies that you’ll be investing in with this ETF are the likes of Accenture, Cisco, Cloudflare, Crowdstrike, Okta. Positively, with demand for these types of services increasing due to the growing threat of cyberattacks on governments and businesses, the future looks very bright for this ETF.

    Life360 Inc (ASX: 360)

    Another tech share to look at is Life360. It is the San Francisco-based technology company behind the incredibly popular Life360 mobile app. This is a market leading app for families, offering features such as communications, driver safety, and location sharing. During the three months ended 30 June, Life360 grew its user base by over 4 million to 32 million users. This is underpinning significant recurring revenues and shows no signs of slowing. Another positive is that the company has just made a major acquisition which has broadened its product range and opened up cross-selling opportunities to its massive user base. All in all, the company appears well-placed to continue its strong growth for some time to come. Credit Suisse is a fan and currently has an outperform rating and $10.00 price target on its shares.

    Nitro Software Ltd (ASX: NTO)

    A final tech share to look at is Nitro Software. It is the document productivity software company behind the Nitro Productivity Suite. This software provides integrated PDF productivity and electronic signature tools to businesses large and small. Demand has been growing rapidly and is underpinning strong recurring revenue growth. For example, at the end of June, Nitro’s annualised recurring revenue (ARR) reached US$33.8 million. This was an increase of 56% over the prior corresponding period. Pleasinginly, the future looks bright thanks to a number of positive tailwinds such as working from home. It also just announced a key acquisition and integration with Salesforce. Wilsons is very positive on the company. Its analysts currently have a buy rating and $4.22 price target on Nitro’s shares.

    The post 3 excellent ASX tech shares that could be buys appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended BETA CYBER ETF UNITS and Life360, Inc. The Motley Fool Australia owns shares of and has recommended BETA CYBER ETF UNITS. The Motley Fool Australia has recommended Nitro Software Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2VPeYPQ

  • 3 reopening ASX share ideas as potential buys

    A shop sign next to a cup of coffee saying opening soon, indicating a company back in business on the share market

    There are a few ASX shares that could be interesting reopening ideas to think about.

    The lockdown continues in Sydney and lockdowns are rolling into other places, with the ACT being the latest region to be affected.

    Plenty of businesses, large and small, are experiencing significant impacts. But they may also be ideas as reopening options once the country gets through this difficult time.

    Tony Featherstone from the Switzer Report has pointed out that in the US there is a lot of demand for COVID-impacted services like music festivals, cruises, air passenger traffic and casinos.

    He pointed out some high-quality, large ASX shares that look good value and could benefit as borders reopen.

    Mr Featherstone revealed these three ideas as ones to consider:

    Qantas Airways Limited (ASX: QAN)

    He noted that Qantas is suffering from the domestic borders closing as well as international borders remaining shut.

    Qantas could be interesting if domestic borders are completely open by the end of FY22 and international borders start to open.

    He thinks demand for Qantas air tickets will go back to full capacity once the public are confident to book travel.

    The ASX share could also emerge from this period with a lower cost base, however, Mr Featherstone acknowledged that Qantas isn’t a screaming buy.

    Star Entertainment Group Ltd (ASX: SGR)

    The casino operator was another stock idea. With The Star in Sydney in lockdown, the business is being heavily impacted. Since the start of June 2021 the Star share price has fallen 17%.

    Mr Featherstone acknowledged the potential threat from a second Sydney casino.

    However, the fact that overseas casinos are doing better than expected after the end of restrictions could be a good sign for later in the year.

    In his opinion, Mr Featherstone believes that The Star is well positioned for the rebound because its main asset is locked down in Sydney. Over the longer-term, the development in Brisbane could also be a good addition.

    Flight Centre Travel Group Ltd (ASX: FLT)

    Flight Centre is the third ASX share that was picked as a reopening idea.

    It was noted that Flight Centre is facing more than one difficulty. There’s the COVID-19 impacts on travel bookings, but there is also the long-term change of bookings from bricks and mortar places to online booking.

    The detractors of Flight Centre, Mr Featherstone points out, say that travel agent commissions are under pressure as people go directly suppliers (like Qantas), and the business also has large rent and wage costs.

    However, a positive factor for the ASX share is that Flight Centre generates around half of its total transaction value (TTV) outside of Australia and New Zealand, where vaccination rates are higher and likely to get back to normal quicker.

    Another factor is that Flight Centre sees a pleasing amount of TTV come from corporate travel, which is less affected by COVID-19 too.

    Whilst he acknowledged that it could take years for full demand to return, Mr Featherstone believes that picking Flight Centre whilst it’s down could be an opportunistic strategy.

    The post 3 reopening ASX share ideas as potential buys appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Qantas right now?

    Before you consider Qantas, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Qantas wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Flight Centre Travel Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2Xj2LUp