Category: Stock Market

  • Telstra (ASX:TLS) and this ASX dividend share are rated as buys

    asx dividend shares represented by tree made entirely of money

    Are you looking for some attractive dividend yields to boost your income? Then you want to look at the ones listed below.

    Here’s why these dividend shares could be great options for income investors in August:

    Aventus Group (ASX: AVN)

    The first ASX dividend share to look at is Aventus. It is a property company with a focus on large format retail parks.

    Thanks to its high level of exposure to the household goods and everyday needs categories, Aventus has been one of the strongest performing retail property companies during the pandemic. This has led to solid rental income growth and an increase in the value of its properties.

    Goldman Sachs has been impressed with its performance and expects it to continue. So much so, it has a buy rating and $3.27 price target on the company’s shares.

    And based on the current Aventus share price, it estimates that its shares will provide investors with yields of 5.3%, 6%, and 6.6%, respectively, between FY 2021 and FY 2023.

    Telstra Corporation Ltd (ASX: TLS)

    Another ASX dividend share to look at is Telstra. The telco giant’s shares may have just hit a 52-week high, but they are still expected to provide investors with generous yields in the coming years.

    Goldman Sachs is also a fan of Telstra. It currently has a buy rating and $4.20 price target on the company’s shares.

    Goldman likes Telstra partly due to its leadership position with 5G, which it expects to support growth in its post-paid mobile average revenue per user (ARPU) metric in the coming years. Together with its corporate restructure and potential asset monetisation, the broker believes Telstra’s outlook is positive.

    The broker is forecasting fully franked annual dividends of 16 cents per share through to FY 2023. After which, it expects a long-awaited dividend increase to 18 cents per share in FY 2024.

    Based on the latest Telstra share price of $3.85, this will mean attractive yields of approximately 4.15% for the next three years.

    The post Telstra (ASX:TLS) and this ASX dividend share are rated as buys appeared first on The Motley Fool Australia.

    These Dividend Stocks Could Be Your Next Cash Kings (FREE REPORT)

    Motley Fool Australia’s Dividend experts recently released a brand-new FREE report revealing 3 dividend stocks with JUICY franked dividends that could keep paying you meaty dividends for years to come.

    Our team of investors think these 3 dividend stocks should be a ‘must consider’ for any savvy dividend investor. But more importantly, could potentially make Australian investors a heap of passive income.

    Don’t miss out! Simply click the link below to grab your free copy and discover these 3 high conviction stocks now.

    Returns As of 15th February 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Telstra Corporation Limited. The Motley Fool Australia has recommended AVENTUS RE UNIT. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3yBxr16
  • 2 top ASX growth shares that might be worth buying

    rising share price represented by a graph, red arrow and notes of American money

    There are some high-quality ASX growth shares to think about for an investor’s portfolio.

    Businesses that are growing revenue and profit at an attractive rate are giving themselves a good chance of producing pleasing shareholder returns.

    Sometimes a business’ value has already taken some of that future growth into account, but growth may be able to help things over the longer-term:

    Bapcor Ltd (ASX: BAP)

    Bapcor is a leading auto parts business that operates in Australia, New Zealand and Asia.

    The business is capitalising on the strange impacts of COVID-19. HY21 saw the business deliver a high level of growth in the first six months of FY21. Revenue grew 25.8% to $883.6 million, pro forma earnings before interest and tax (EBIT) went up 45% to $106.8 million and pro forma net profit after tax increased 54%.

    The trade segment, including Burson, saw double digit growth with a 12.3% rise of revenue. But it was the retail segment, which includes Autobarn, that truly delivered big growth – revenue rose 44% and earnings before interest, tax, depreciation and amortisation (EBITDA) jumped 55.8%.

    In a recent trading update, Bapcor said that its trade same store sales continued to see double digit growth (up 13%), whilst Autobarn same store sales were up 35% and specialist wholesale revenue was up 31%.

    Management believe there are significant opportunities within the ASX growth share to drive operational and financial performance.

    Bapcor has a number of growth plans. It wants to grow its existing store sales, increase the number of stores, provide differentiated offerings compared to competitors, grow its e-commerce offering and expand in Asia. The business also wants to supplement market-leading brands with Bapcor’s own brand products. Another focus is leveraging its logistics capability to deliver operational excellence and optimise its supply chain benefits.

    According to Commsec, the Bapcor share price is valued at 20x FY22’s estimated earnings.

    Betashares Global Cybersecurity ETF (ASX: HACK)

    This ASX growth share is an exchange-traded fund (ETF) that is focused on the global industry of cybersecurity.

    The portfolio includes global cybersecurity giants as well as emerging players from across the world. Some of those names in the portfolio include Zscaler, Crowdstrike, Accenture, Okta, Cisco Systems, Cloudflare, Fortinet, Varonis Systems, Splunk and F5 Networks.

    Whilst more than half of the holdings are allocated to the segment of ‘systems software’, there are also double digit weightings to sub-sectors like ‘communications equipment’ and ‘internet services and infrastructure’.

    As BetaShares says, with cybercrime on the rise, the demand for cybersecurity services is expected to grow strongly for the foreseeable future. In 2017 the global cybersecurity market was US$137.63 billion and by 2023 it’s expected to have grown to US$248.26 billion.

    The returns of the ETF have reflected the growth of the underlying businesses. But past performance is not an indicator of future performance. Including the annual management fee of 0.67%, the ETF has delivered an average return per annum of 22.3% since inception in August 2016.

    The post 2 top ASX growth shares that might be worth buying appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Bapcor right now?

    Before you consider Bapcor, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Bapcor wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended BETA CYBER ETF UNITS. The Motley Fool Australia owns shares of and has recommended BETA CYBER ETF UNITS and Bapcor. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2VJymhF

  • 5 things to watch on the ASX 200 on Wednesday

    Investor sitting in front of multiple screens watching share prices

    On Tuesday the S&P/ASX 200 Index (ASX: XJO) was on form and pushed higher. The benchmark index ended the day 0.3% higher at 7,562.6 points.

    Will the market be able to build on this on Wednesday? Here are five things to watch:

    ASX 200 futures pointing higher

    The Australian share market is expected to push higher on Wednesday following a decent night on Wall Street. According to the latest SPI futures, the ASX 200 is expected to open the day 19 points or 0.25% higher this morning. On Wall Street, the Dow Jones rose 0.45%, the S&P 500 pushed 0.1% higher, and the Nasdaq dropped 0.5%.

    CBA full year results

    The Commonwealth Bank of Australia (ASX: CBA) share price will be on watch today when it releases its highly anticipated full year results. According to a note out of Goldman Sachs, it expects Australia’s largest bank to report a 15% increase in cash earnings from continued operations (pre-one offs) to A$8,342 million. This compares to the analyst consensus estimate of $8,464 million. The broker has also pencilled in a final dividend of 195 cents per share and a special dividend of 200 cents per share.

    Oil prices rebound

    It could be a good day for energy producers such as Santos Ltd (ASX: STO) and Woodside Petroleum Limited (ASX: WPL) after oil prices rebounded. According to Bloomberg, the WTI crude oil price is up 2.9% to US$68.41 a barrel and the Brent crude oil price is up 2.5% to US$70.74 a barrel. Rising demand in Europe and the United States outweighed concerns over an increase in COVID-19 cases in Asia.

    Computershare full year results

    The Computershare Ltd (ASX: CPU) share price will be one to watch today. This follows the release of the stock transfer company’s full year results after the market close. Computershare reported an 0.8% decline in full year management revenue to US$2.3 billion and a 7.3% fall in management earnings per share to 52.03 US cents. The latter was better than its guidance for an 8% decline. And while the company is guiding to a stronger year in FY 2022, its guidance has fallen short of Goldman Sachs’ estimates.

    Gold price rises

    Gold miners Evolution Mining Ltd (ASX: EVN) and Newcrest Mining Limited (ASX: NCM) could have a better day on Wednesday after the gold price pushed higher. According to CNBC, the spot gold price is up 0.2% to US$1,729.50 an ounce. Concerns over rising COVID-19 cases halted the precious metal’s slide.

    The post 5 things to watch on the ASX 200 on Wednesday appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3AxnhyU

  • 2 top ASX dividend shares tipped to grow at a solid rate

    chart showing an increasing share price

    Are you looking to add some growing dividend shares to your portfolio this month? Then you may want to look at the ones listed below.

    Here’s why they could be top options for income investors:

    Accent Group Ltd (ASX: AX1)

    The first ASX dividend share to look at is Accent. It is a growing retail group with a collection of footwear store brands including HYPEDC, Platypus, Sneaker Lab, Stylerunner, and The Athlete’s Foot. It has also recently acquired fashion retailer Glue Store and launched a new workwear store brand called 4 Workers.

    Given the popularity of its brands, its store expansion plans, and favourable trading conditions, Accent has been tipped to continue growing its earnings and dividend in the coming years.

    Bell Potter, for example, is very positive on the company. It has a buy rating and $3.30 price target on its shares.

    The broker is forecasting dividends of 11.7 cents per share in FY 2021 and 12.3 cents per share in FY 2022. Based on the latest Accent share price of $2.80, this represents fully franked yields of 4.2% and 4.4%, respectively.

    Collins Foods Ltd (ASX: CKF)

    Another ASX dividend share to look at is Collins Foods. It is a leading quick service restaurant operator with a focus on KFC restaurants.

    It has been a positive performer during the pandemic. For example, in June the company released its full year results and reported a 12.4% increase in revenue to $1.07 billion. This was driven largely by its KFC Australia business, which reported a 13.8% increase in revenue to $900.4 million thanks to new store openings and same store sales growth of 12.9%.

    On the bottom line, the company’s underlying net profit after tax from continuing operations growth was even stronger. It was up 18.2% to $56.9 million. This allowed the Collins Foods board to increase its dividend once again.

    This went down well with analysts at Canaccord Genuity. Its analysts have a buy rating and $13.35 price target on the company’s shares. The broker is also forecasting further dividend growth in the coming years. It expects fully franked dividends per share of 26 cents in FY 2022 and then 29 cents in FY 2023.

    Based on the latest Collins Foods share price of $11.08, this will mean yields of 2.3% and 2.6%, respectively.

    The post 2 top ASX dividend shares tipped to grow at a solid rate appeared first on The Motley Fool Australia.

    These Dividend Stocks Could Be Your Next Cash Kings (FREE REPORT)

    Motley Fool Australia’s Dividend experts recently released a brand-new FREE report revealing 3 dividend stocks with JUICY franked dividends that could keep paying you meaty dividends for years to come.

    Our team of investors think these 3 dividend stocks should be a ‘must consider’ for any savvy dividend investor. But more importantly, could potentially make Australian investors a heap of passive income.

    Don’t miss out! Simply click the link below to grab your free copy and discover these 3 high conviction stocks now.

    Returns As of 15th February 2021

    More reading

    Motley Fool contributor James Mickleboro owns shares of Collins Foods Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Accent Group and Collins Foods Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3izweSr

  • Computershare (ASX:CPU) share price on watch after FY21 guidance beat

    a surprised investor reading about an asx share price in a newspaper

    The Computershare Ltd (ASX: CPU) share price will be one to watch on Wednesday.

    This follows the after market release of the stock transfer company’s full year results.

    Computershare share price on watch after beating its guidance in FY 2021

    • Full year management revenue fell 0.8% to US$2.3 billion
    • Management revenue excluding margin income (MI) up 3.6% to US$2.2 billion
    • Margin income down 47.7% to US$104.3 million
    • Management earnings before interest and tax (EBIT) excluding MI up 12.6% to US$336.4 million.
    • Management earnings per share down 7.3% to 52.03 US cents per share (compared to guidance for an 8% decline)
    • Final dividend flat at 23 Australian cents per share

    What happened in FY 2021 for Computershare?

    All eyes will be on the Computershare share price tomorrow after it delivered a result slightly ahead of guidance. This was driven by a significant improvement in the company’s operating performance during the second half of FY 2021, with earnings increasing 39% half on half.

    Management advised that this was driven by a positive performance from its key operating businesses of Issuer Services and Employee Share Plans. They have been benefitting from higher activity levels and stronger equity markets. In addition, thanks to disciplined cost controls, its margins expanded when excluding the impact of low interest rates, which continue to drag on its margin income.

    What did management say?

    Computershare’s CEO, Stuart Irving, was pleased with the way the company finished the financial year.

    He said: “Computershare has delivered an improved operating performance in the second half of the year, with a 39% increase in earnings compared to the first half. This enabled us to report Management earnings per share (EPS) for the full year in line with the upgraded guidance we provided in February.”

    “A highlight of the year was the announcement in March of our agreement to acquire the assets of Wells Fargo Corporate Trust Services, a leading US provider of trust and agency services to government and corporate clients. On track to complete later this year, the acquisition accelerates our scale in the attractive US corporate trust market. It also provides Computershare with greater exposure to long term growth trends in trust and securitisation products as well as the interest rate environment. The business is to be renamed Computershare Corporate Trust (CCT),” he added.

    What’s next for Computershare?

    Potentially giving the Computershare share price a boost on Wednesday will be its outlook for FY 2022.

    Mr Irving expects the company to deliver earnings growth in FY 2022. This is thanks to the positive progress it is making in executing its growth strategies despite the challenges it is facing in some of its business lines.

    He said: “Management EPS is expected to increase by around 2% in constant currency, after accounting for the impact of the rights issue. Guidance assumes over 4% EPS growth in our existing business lines. The CCT acquisition is expected to complete in October/November. Accretive on an annualised basis, it should add over 4 cps to earnings in FY22, given its partial second-half weighted contribution to the year. The rights issue will impact us by around 5.6 cps in FY22.”

    Computershare share price performance

    The Computershare share price is up 13% in 2021. This is roughly in line with the performance of the ASX 200 index over the same period.

    The post Computershare (ASX:CPU) share price on watch after FY21 guidance beat appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Computershare right now?

    Before you consider Computershare, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Computershare wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3fRkSam

  • The ASX reporting wrap-up: Challenger, Megaport, James Hardie

    business man reviewing report and using calculator

    Tuesday has drawn to a close… it’s the second day of the week and the market is alight with ASX shares reporting earnings. Markets reacted with cheer to today’s big-name results with an acquisition announcement thrown into the mix.

    We’ll quickly unpack today’s results and then wrap it back up for tomorrow:

    Those that delivered today

    Challenger Ltd (ASX: CGF)

    Shares in the investment management company increased 1.9% to $5.89. This followed the release of the company’s FY21 results and the announcements of the CEO’s retirement.

    The takeaway points:

    • Net income down 14% to $682 million.
    • Normalised net profit after tax down 19% to $279 million.
    • Group assets under management (AUM) up 29% to $110.0 billion.
    • Fully franked, full-year dividend of 20.0 cents per share, up 2.5 cents per share on FY2020.
    • Managing Director and CEO Richard Howes to step down in March 2022

    Megaport Ltd (ASX: MP1)

    The Megaport share price gained 3.05%, putting it at $17.90 by the close of the ASX today. The move followed the interconnection services company reporting its strong full-year results to the ASX. Additionally, Megaport also announced the acquisition of an AI-powered multi-cloud company known as InnovoEdge.

    The takeaway points:

    • Revenue increased 35% year on year to $78.28 million.
    • Monthly recurring revenue (MRR) jumped 32% to $7.5 million (annualises to $90 million)
    • Customers increased 443, or 24%, to 2,285
    • Ports grew 1,922, or 33%, to 7,689
    • Average revenue per port down $2 to $978
    • Net loss of $55 million but cash position of $136.3 million
    • US$15 million acquisition of InnovoEdge

    James Hardie Industries PLC (ASX: JHX)

    Lastly, shares in James Hardie jumped 2.9% to $49.32 today. At one point, the ASX-listed materials manufacturer surpassed the $50 barrier, setting a record high. The price appreciation followed a solid first-quarter result.

    The takeaway points:

    • Sales up 35% over the prior corresponding period to US$843.3 million
    • Adjusted earnings before interest and tax (EBIT) jumped 45% to $180.5 million
    • Net income up 50% to US$134.2 million
    • Operating cash flow down 3% to US$184.1 million
    • Full year net income guidance upgraded

    ASX shares reporting tomorrow

    Wednesday is set to be a big one with a few more results to be reported by ASX-listed companies. These include Commonwealth Bank of Australia (ASX: CBA), Insurance Australia Group Ltd (ASX: IAG), and Mineral Resources Ltd (ASX: MIN).

    The post The ASX reporting wrap-up: Challenger, Megaport, James Hardie appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Mitchell Lawler owns shares of Commonwealth Bank of Australia. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended MEGAPORT FPO. The Motley Fool Australia owns shares of and has recommended Challenger Limited and Insurance Australia Group Limited. The Motley Fool Australia has recommended MEGAPORT FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3fNVxyd

  • 2 excellent ASX 200 blue chip shares named as buys

    A man with a yellow background makes an annoncement, indicating share price changes on the ASX

    If you’re wanting to boost your portfolio with some blue chips, then you might want to look at the ASX shares listed below.

    Here’s why these ASX blue chip shares are highly rated:

    SEEK Limited (ASX: SEK)

    SEEK is the leading job listings company in the ANZ region. It also has a number of growing businesses around the globe.

    In respect to the former, during the first half of FY 2021, the company was the dominant force in the local market. It was averaging 35 million monthly visits and 160,000 active hirers. This represents almost a third of all placements in the region and is five times greater than its nearest rival.

    It is thanks to this dominance that SEEK has been tipped to benefit greatly from Australia’s strong economic recovery from the pandemic. With the unemployment rate tipped to fall materially over the next 12 months, job ad volumes look set to increase and underpin strong top line growth.

    Macquarie is positive on SEEK. It currently has an outperform rating and $40.00 price target on its shares.

    Sonic Healthcare Limited (ASX: SHL)

    Sonic Healthcare is one of the world’s leading providers of medical diagnostics. Over the last few decades it has earned a reputation for excellence in pathology, diagnostic imaging, and primary care medical services across operations in the ANZ, European and North American markets.

    Due largely to strong demand for COVID-19 testing services, it is expected to deliver a very strong full year result this month. And with COVID testing unlikely to be going away any time soon, the company appears well-placed to benefit from elevated testing volumes in FY 2022 and potentially even FY 2023.

    Combined with the strength of the rest of the business and a balance sheet that would support earnings accretive acquisitions, the future looks bright for Sonic.

    Credit Suisse is very positive on Sonic and has an outperform rating and $43.50 price target on its shares.

    The post 2 excellent ASX 200 blue chip shares named as buys appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Sonic right now?

    Before you consider Sonic, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Sonic wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro owns shares of SEEK Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended SEEK Limited and Sonic Healthcare Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2VAWcM9

  • Why the Archer Materials (ASX:AXE) share price rocketed 13% today

    a man sits on a rocket propelled office chair and flies high above a city

    The Archer Materials Ltd (ASX: AXE) share price reached an all-time high in intraday trade today. This came after the semiconductor company announced it has been granted a new South Korean patent.

    In late afternoon trade, Archer shares were swapping hands for $1.665 apiece — a new record. By the final bell, they had partially retreated to $1.61, a 12.94% gain on yesterday’s closing price.

    Archer adds to its intellectual property portfolio

    Investors are pushing the Archer share price higher after digesting the company’s positive update.

    According to its release, Archer has been granted a patent associated with its CQ quantum computing chip technology.

    The KR patent (No. 10-2288974) is considered a significant commercial milestone in the company’s efforts to access global markets.

    South Korea is regarded as a leading manufacturer and exporter of semiconductor chip devices. Conglomerates such as Samsung Electronics and SK Hynix are ranked among the top producers in the world.

    Achieving patent approval is a giant leap for the company. The Korean Intellectual Property Office has more than 1 million patents and thoroughly examines each patent before consent.

    Together with the United States and China, South Korea is one of the most competitive jurisdictions for patent granting.

    As such, the granting of the patent gives Archer access to a high-performing economy to explore sales opportunities within the country.

    South Korea committed to investing US$450 billion in the industry through to 2030. Most of these funds came from Samsung Electronics and SK Hynix, US$150 billion and US$200 billion, respectively.

    CEO Dr Mohammad Choucair commented on the news which could be affecting the Archer share price:

    Archer’s quantum computing chip IP is now well protected in South Korea – home to some of the world’s largest chipmakers, and a critical part of the global semiconductor supply chain.

    We now have CQ chip patents granted in Japan and South Korea, with patent applications in the US, China, and Europe progressing well… South Korea’s semiconductor industry is one of the world’s best, while Asia as a whole dominates in semiconductor manufacturing, where close to 80% of all chips are produced.

    The patent is valid until December 2036.

    Archer share price snapshot

    Shareholders would be ecstatic with the Archer share price since the beginning of 2021.

    The company’s share price has gained more than 200% year-to-date, reflecting strong optimism in Archer’s progress in developing its CQ chip.

    The post Why the Archer Materials (ASX:AXE) share price rocketed 13% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Archer Materials right now?

    Before you consider Archer Materials, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Archer Materials wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3xxjekh

  • What’s up with ASX 200 gold shares on Tuesday?

    man eating gold bars

    The basket of S&P/ASX 200 Index (ASX: XJO) gold shares has slipped into the red during today’s session.

    And looking beyond the ASX 200, to the 27 ASX-listed gold shares with a market capitalisation of over $200 million, the average loss today is 1.47% and the median loss is 1.5% (at the time of writing).

    What’s impacting ASX 200 gold shares today?

    Firstly, the spot price of gold is down around 5% over the past month and a similar amount over the past six months, extending the loss over the past year to approximately 15%.

    Moreover, the spot price of gold took a 3–4.5% dip over the past two days, with the yellow metal now trading at $1,736 per ounce.

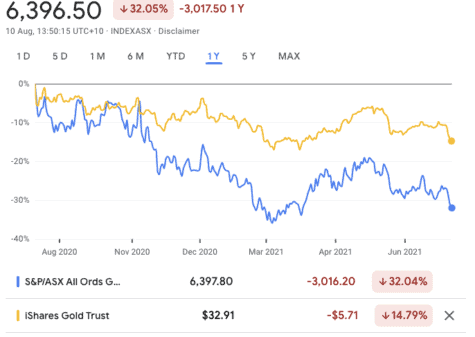
    There is a high correlation between the price of gold and ASX 200 gold shares, as can be gleaned from the chart below. That is, the pair tend to move in a relatively similar fashion. The chart highlights the single year performance of the S&P/ASX All Ordinaries Gold Index (ASX: XGD) versus the iShares Gold Trust.

    For context, according to the issuer iShares, its Gold Trust “seeks to reflect generally the performance of the price of gold” whereas the All Ords’ Gold index “is a benchmark for Australian gold companies”. Therefore, both are acceptable proxies for our analysis.

    Correlation between ASX Gold shares and price of gold, last 12 months

    Source: Google Finance

    Notice the synchronised movement (movement, not actual price) in the pair’s price returns over the last year, for instance.

    Adding weight to this correlation is the underperformance of key ASX gold shares today.

    To illustrate, Newcrest Mining Ltd (ASX: NCM), Evolution Mining Ltd (ASX: EVN), Northern Star Resources Ltd (ASX: NST) and St Barbara Ltd (ASX: SBM) shares have all slipped into the red today, amid many other well-known names.

    For comparison, the S&P/ASX 200 Index has climbed about 0.2% into the green during today’s session.

    Therefore, given the correlation between gold spot and ASX gold shares, it stands to reason that this recent volatility will have some bearing on the ASX gold basket’s price action today.

    What about inflation?

    Inflation is certainly a contentious issue in the global economy at the moment, with commentary from both sides around the globe weighing in on the debate.

    For instance, discussions on “inflation” were at a record high among S&P 500 company earnings calls this quarter, increasing 900% year on year, according to Bank of America.

    Gold has traditionally been viewed as a reasonable hedge against inflation. However, data shows the correlation of gold to inflation has been historically low over the past 50 years, at only 16%. A correlation of 50–100% is considered statistically significant.

    Next, central banks use their position in the marketplace to regulate factors such as inflation and interest rates.

    In fact, one of the Reserve Bank of Australia (RBA)’s primary functions is to maintain inflation within a range of 2–3%.

    In order to achieve this, the RBA utilises its position in the money markets to indirectly increase interest rates, which flows on to contain the fire of inflation in the real economy.

    What about interest rates and ASX gold shares?

    A hike to interest rates is generally seen as a headwind to gold prices as investors seek yield in higher rewarding asset classes, such as fixed income.

    The RBA’s posture has been to hold rates down since 2020, even throughout the COVID-19 pandemic. For instance, the RBA has stated the cash rate will remain flat at 0.1% until 2024 at the current trajectory.

    However, the Commonwealth Bank of Australia (ASX: CBA), amongst other banks, predicts this rise will occur sooner. CBA just adjusted its 2-year and 4-year mortgage rates to reflect its viewpoint, the third increase this year.

    Given the bank’s move, it is not unreasonable to expect other financial institutions to follow suit, thereby acting on their conviction.

    Therefore, it stands to reason that the recent selloff in ASX gold shares is somewhat impacted by the uncertainties on interest rates in the economy.

    Foolish takeaway

    ASX Gold shares have had a rough day on the back of headwinds in the underlying gold markets and in the real economy.

    Gold prices are sensitive to market forces such as interest rates and often there is a conception that gold, on its own, is a reasonable hedge against inflation. There is debate on whether it is or not.

    As the uncertainties on interest rates continue in Australia, this may have some bearing on ASX gold shares as we walk through the remainder of 2021.

    The post What’s up with ASX 200 gold shares on Tuesday? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    The author Zach Bristow has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3CsPTvb

  • ASX 200 rises, Challenger and James Hardie up on results

    bull market encapsulated by bull running up a rising stock market price

    The S&P/ASX 200 Index (ASX: XJO) went up by 0.3% to 7,563 points.

    Here are some of the highlights from the ASX today:

    James Hardie Industries plc (ASX: JHX)

    The James Hardie share price went up 3% today after releasing its result for the first quarter of FY22.

    In the first three months of the financial year, to 30 June 2021, it saw total net sales increase by 35% to US$843.3 million. Net profit surged 1,191% higher to US$121.4 million. Global adjusted earnings before interest and tax (EBIT) increased 45% to US$180.5 million with the adjusted EBIT margin rising 150 basis points to 21.4%.

    The North American and Asia Pacific divisions were what drove the EBIT higher. The North America division saw adjusted EBIT grow 29% to US$169.3 million and Asia Pacific adjusted EBIT rose 50% to A$50.4 million.

    James Hardie CEO Dr Jack Truong said:

    I am very pleased that this first quarter marked our ninth consecutive quarter of delivering growth above market and strong returns. In our investor day at the end of May, we described our three critical initiatives for FY22 through to FY24: One, market directly to homeowners to accelerate demand creation, two, penetrate and drive profitable growth in existing and new segments and, three, commercialise global innovations by expanding into new categories. Further, we discussed our focus on driving a high value product mix in all three regions.

    The company raised its guidance for FY22. It’s now expecting adjusted net income to be between US$550 million to US$590 million, up from the previous guidance of US$520 million to US$570 million. That compares to FY21 adjusted net income of US$458 million.

    The James Hardie share price was one of the better performers in the ASX 200.

    Challenger Ltd (ASX: CGF)

    The Challenger share price went up more than 1% after the annuity business released its FY21 result.

    It said that group assets under management (AUM) grew by 29% to $110 billion, with life book growth of 14% and funds management net flows of $16 billion.

    The company said that its profit was within its guidance range. Normalised net profit before tax was $396 million, down 22%, reflecting a proactive decision to maintain more defensive portfolio settings during the pandemic.

    It generated a statutory net profit after tax of $592 million, which included positive investment gains.

    Challenger said that it has a strong capital position, with Challenger Life having $1.6 billion of excess regulatory capital.

    The full year dividend was increased by 14% to 20 cents per share.

    Challenger managing director and CEO Richard Howes, said:

    This year, we have taken decision action to set up the business for future growth – executing our strategy to diversify revenue, repositioning our investment portfolio and strengthening our balance sheet.

    Following our decision to reposition the investment portfolio during the early stages of the pandemic, as flagged, we gradually deployed significant cash balances into higher returning assets throughout the year, with the full benefits to be realised next year.

    Mr Howes also announced his intention to retire, set for March 2022. 

    Megaport Ltd (ASX: MP1)

    Megaport was another ASX 200 share to report its result to investors today. The Megaport share price increased by 3%.

    It said that annual revenue increased by 35% to $78.28 million, whilst customers went up 24% to 2,285.

    Monthly recurring revenue (MRR) for the month of June 2021 was $7.5 million, an increase of 32% year on year.

    Megaport said that it generated a profit after direct network costs during the year of $42.1 million, an increase of 43% year on year. It achieved breakeven earnings before interest, tax, depreciation and amortisation (EBITDA) in June 2021.

    The Asia Pacific region saw a profit after direct network costs margin of 73%.

    However, the bottom line for the year was a net loss of $55 million. It finished with a cash position of $136.3 million.

    It’s planning to continue to invest for growth of its market share, invest in its product and service, and invest in its people.

    The ASX 200 company also announced the acquisition of InnovoEdge for up to US$15 million, including US$7.5 million of cash. It was described as an AI-powered, multicloud and edge application orchestration company. 

    The post ASX 200 rises, Challenger and James Hardie up on results appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Megaport right now?

    Before you consider Megaport, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Megaport wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended MEGAPORT FPO. The Motley Fool Australia owns shares of and has recommended Challenger Limited. The Motley Fool Australia has recommended MEGAPORT FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3lPyPtw