Category: Stock Market

  • The Westpac (ASX:WBC) share price is higher today after sale update

    A hand holds a wooden figure up to a set of blocks to stop them falling, indicating life insurance policy

    The Westpac Banking Corp (ASX: WBC) share price is gaining today after the bank announced the sale of its life insurance business.

    The bank advised Westpac Life Insurance Services Limited will go to TAL. This is a subsidiary of global life insurance services provider Dai-ichi Life Group.

    TAL will pay $900 million for the business. It will also enter a strategic alliance to provide Westpac’s Australian customers with the service for another 20 years.

    Right now, the Westpac share price is trading at $25.44. That’s 1.27% higher than its previous closing price.

    Let’s take a closer look at today’s news from Westpac.

    Westpac opts out of life insurance

    Today’s positive Westpac share price movement may be responding to the bank’s confirmation of the life insurance service sale.

    According to Westpac, the divestment “releases significant capital”.

    Westpac has lost a total of $1.3 billion (post-tax) on the sale. However, it will add around 12 basis points to Westpac’s Level 2 common equity Tier 1 capital ratio. 

    The big bank will record a post-tax loss of $300 million for the life insurance business in its financial year 2021 results. The immediate loss mainly relates to transaction and separation costs.  

    The remaining loss will the noted when the sale is completed, which is expected to be in late 2022.

    Rumours of the sale have been swirling for months now, with TAL tipped as an interested party in June.

    Commentary from management

    Westpac’s group chief executive specialist businesses and group strategy Jason Yetton welcomed the news, saying:

    This transaction is another step in simplifying the bank while continuing to help customers with their life insurance needs by partnering with TAL.

    Life insurance is an important product for many Australians and this sale provides certainty for customers and new opportunities for our people with TAL.

    TAL already offers insurance products to more than 4.5 million Australians and is well placed to help Westpac’s customers protect the people they love.

    Westpac share price snapshot

    The Westpac share price has had a good run lately.

    It is currently 29% higher than it was at the start of 2021. It has also gained 47% since this time last year.

    The post The Westpac (ASX:WBC) share price is higher today after sale update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Westpac Banking Corp right now?

    Before you consider Westpac Banking Corp, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Westpac Banking Corp wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3Aun53H
  • Here’s why the Charger Metals (ASX:CHR) share price has surged 100% in a week

    A drawing of a rocket follows a chart up, indicating share price lift

    The Charger Metals NL (ASX: CHR) share price has rallied for four consecutive days, surging more than 100% from 21.5 cents to 52.5 cents.

    Charger Metals successfully listed on the ASX on 9 July, raising $6 million at an issue price of 20 cents.

    The company owns a majority interest in a number of prospective nickel, copper, cobalt, lithium and gold projects.

    The purpose of the initial public offering was to fund the company’s exploration activities with the aim of defining valuable mineral resources that can be monetised either through further development or sale.

    Why the Charger Metals share price surging

    Renewables hype

    Charger Metals portfolio is focused on critical metals used in industries such as battery storage, solar and electric vehicles.

    As investors might have noticed, this sector has been on fire lately with other ASX-listed lithium developers and producers surging in the past month. This includes:

    • Pilbara Minerals Ltd (ASX: PLS) up 42.95% to $2.13
    • Galaxy Resources Limited (ASX: GXY) up 31.8% to $4.93
    • Lake Resources N.L. (ASX: LKE) up 64% to 61 cents
    • Core Lithium Ltd (ASX: CXO) up 56% to 36 cents

    With all the above lithium companies surging in valuation, Charger Metals share price might be at the right place at the right time.

    Prospective projects

    Charger Metals has an interest in the following projects:

    • A 70% interest in the Coates Nickel-Copper-Cobalt project
    • An 85% interest in Coates North Project
    • A 70% interest in the Bynoe Lithium and Gold project
    • A 70% interest in the Lake Johnston Lithium and Gold project

    In the company’s July presentation, it cited that lithium, nickel, copper and platinum group metals are “all metals in demand”.

    Charger Metals described the Coates project as a “Julimar geochemical lookalike requiring drilling”.

    For those that don’t know, the Julimar project is owned by Chalice Mining Ltd (ASX: CHN).

    Chalice has described Julimar as a “globally significant discovery” with multiple prospects of high grade nickel, copper, platinum, cobalt and gold.

    Chalice has been undergoing drilling activities at Julimar since March 2020. During this time, its share price has surged more than 1,000% from around 40 cents to $6.72 at the time of writing.

    In addition, Charger Metals has described Bynoe as “fertile area close to a proposed Li mine” and Lake Johnson as a “large landholding with known spodumene”.

    The post Here’s why the Charger Metals (ASX:CHR) share price has surged 100% in a week appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Charger Metals right now?

    Before you consider Charger Metals, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Charger Metals wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Kerry Sun owns shares of Core Exploration Ltd. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3xuEvuV

  • Why is the Novonix (ASX:NVX) share price frozen today?

    A dollar sign embedded in ice, indicating a share price freeze or trading halt

    The Novonix Ltd (ASX: NVX) share price is frozen today as the company prepares to release an announcement to the market.

    The company requested the ASX halt the trading of its shares as it undertakes a strategic capital raise.

    The Novonix share price finished Friday’s session trading for $3.02.

    Let’s take a closer look at the graphite exploration and battery technology company’s trading halt.

    Novonix freezes over

    The Novonix share price is frozen while the company gears up to release news of a strategic capital raise.

    Unless the freeze is extended, Novonix’s shares will begin trade when the company makes its next announcement, or when the market opens on 11 August, whichever comes first.

    The capital raise comes at what appears to be an odd time for the Novonix share price.

    Novonix’s latest quarterly cash flow report stated the company has enough cash to run its current operations for another 140 quarters. That’s a whopping 35 years’ worth of funding.

    Additionally, Novonix underwent a capital raise in February. The capital raise saw Novonix raise approximately $115 million from institutional investors.

    The funds were to go towards increasing the company’s anode materials production capabilities to 10,000 tonnes per annum.

    It also intended to begin a share purchase plan (SPP) to raise another $15 million in March. However, the SPP was first delayed, then cancelled. The company said the SPP’s cancellation was due to fluctuations in the Novonix share price.

    Finally, the company recently expressed interest in listing on the NASDAQ exchange.

    We’ll soon find out if the strategic capital raise is to do with the potential dual listing.

    Although, Novonix could be raising capital for entirely different reasons. Many market watchers are likely anticipating the company’s next announcement.

    Novonix share price snapshot

    It’s been a fantastic year on the ASX for the Novonix share price.

    It has gained 143.5% since the start of 2021. It has also increased by 139.6% since this time last year.

    The company has a market capitalisation of around $1.2 billion, with approximately 404 million shares outstanding.

    The post Why is the Novonix (ASX:NVX) share price frozen today? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Novonix right now?

    Before you consider Novonix, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Novonix wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3jEMoZO

  • Here’s why the Global Energy (ASX:GEV) share price is leaping higher today

    jump in asx share price represented by man leaping up from one wooden pillar to the next

    The Global Energy Ventures Ltd (ASX: GEV) share price is leaping higher today, up 6% at time of writing, having earlier posted gains of more than 9%.

    The company is focused on delivering compressed shipping solutions to produce, store and transport compressed hydrogen to regional markets surrounding Australia.

    Below we take a look at the ASX energy share’s announcement that appears to be driving ASX investor interest.

    What did Global Energy announce?

    Global Energy’s share price is surging after the company reported it has entered into a non-binding Memorandum of Understanding MOU) with Province Resources Ltd (ASX: PRL) and Total Eren on a new green hydrogen shipping study.

    The partnership will help determine the feasibility, both commercial and technical, of exporting compressed hydrogen from the HyEnergy Project in Western Australia to select markets in Asia-Pacific, making use of Global Energy’s compressed hydrogen marine supply chain.

    Following completion of the study, Global Energy hopes the partners of the HyEnergy Project will have sufficient confidence to select its C-H2 marine transport supply chain for green hydrogen exports in the next phase of project engineering.

    Commenting on the MOU, Global Energy’s managing director Martin Carolan said:

    The HyEnergy Project is an ideal green hydrogen export project for our compressed hydrogen shipping solution given its strategic location on the W.A. Gascoyne coastline, within a regional distance to multiple Asian markets with a future requirement for imported hydrogen.

    Province Resources CEO, David Frances added:

    The HyEnergy Project partners are keen to understand the benefits of compressed hydrogen in relation to other means of transporting our potential green hydrogen product to market. GEV are leaders in this technology and will bring that experience to the study.

    The non-binding, non-exclusive MOU expires on 31 December 2022.

    Global Energy share price snapshot

    Over the past 12 months Global Energy’s share price has gained 18%, trailing the 25% returns posted by the All Ordinaries Index (ASX: XAO).

    Year-to-date the Global Energy share price has struggled, down 11% in 2021.

    The post Here’s why the Global Energy (ASX:GEV) share price is leaping higher today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Global Energy right now?

    Before you consider Global Energy, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Global Energy wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2VABsEF

  • Pricing-power shares like Wesfarmers (ASX:WES) help fight inflation: expert

    A smiling man at a shop counter takes payment from a female customer, with racks of plants in the background.

    Inflation can be a persistent and pervasive problem. It tends to erode the value of hard-earned cash by steadily reducing its purchasing power. To maintain that all-important spending power, ASX investors need to find stocks that will provide returns that exceed the rate of inflation. An expert considers Wesfarmers Ltd (ASX: WES) to be one such company.

    One Australian fund manager has shared a characteristic that makes companies potentially more capable of defending against corrosive inflation.

    Defeating the effects of inflation

    Inflation is when prices for goods and services increase over time. This means that it costs more to buy groceries or fill up your fuel tank than it did before.

    However, consumers are often not alone in their inflation woes. Companies can also feel the pinch of rising costs due to inflation, whether this is in the form of increased material costs or labour expenses.

    Portfolio Manager and Head of Research at Airlie Funds Emma Fisher shared her insights on combating inflammatory inflation. In an interview, Fisher highlighted pricing power as an important trait of companies able to ward off the impact of inflation.

    Ultimately when we look across the portfolio, I think the key thing to worry about is that the businesses that you’re invested in have pricing power. Inflation is going up in the near term. The unanimous feedback from corporates is that they are seeing raw material and increasingly labour market inflation coming through. Their hope is that they are going to be able to pass that through to the end consumer in the form of higher prices.

    In addition to this, Fisher suggested examples of these inflation-fighting shares include Wesfarmers, James Hardie Industries PLC (ASX: JHX), Woolworths Group Ltd (ASX: WOW), and Reece Ltd (ASX: REH).

    Back in May, Wesfarmers CEO Rob Scott confessed that the whole market is facing cost pressures. However, the leader of the $72 billion business suggested they weren’t simply looking at increasing prices to offset inflationary costs. Instead, the company is attempting to use its scale to negotiate lower costs with its suppliers.

    Wesfarmers’ plan is to capture a greater market share while other companies pass on increased costs to customers.

    When will Wesfarmers report to the ASX?

    Being one of the largest companies on the ASX, the Wesfarmers FY21 annual report is highly anticipated. The diversified business conglomerate expects to release its annual results on Friday 27 August.

    Shareholders of Wesfarmers are also likely on the lookout for a renewed bid for Australian Pharmaceutical Industries Ltd (ASX: API). This follows the company’s initial $1.38 per share bid for the pharmacy chain operator which was rejected.

    The post Pricing-power shares like Wesfarmers (ASX:WES) help fight inflation: expert appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Wesfarmers right now?

    Before you consider Wesfarmers, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Wesfarmers wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Mitchell Lawler has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Wesfarmers Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2WYdlQv

  • Appen (ASX:APX) share price drops after a fantastic week

    white arrow pointing down

    The Appen Ltd (ASX: APX) share price is dropping during early afternoon trade on Monday. This comes despite no new news being released by the artificial intelligence data services company.

    At the time of writing, Appen shares are fetching for $12.24, down 2.47%. In comparison, the S&P/ASX 200 Index (ASX: XJO) touched an all-time high of 7,549 points, up 0.1%.

    What’s going on with the Appen share price?

    It appears investors are taking some profit off the table after Appen shares bounced 8% higher last week.

    The company’s share price has been hit hard by the onslaught of COVID-19, falling 67% since this time last year.

    In May, Appen delivered a trading update and announced a restructure to focus on its core business interests. Instead of reporting the usual double-digit growth however, the company is expecting a mid-to-high single-digit increase for FY21.

    In addition, Appen shares were kicked out of the ASX 100 Index as its market capitalisation sank, making way for Harvey Norman Holdings Limited (ASX: HVN).

    The United States dollar is also weighing in on Appen’s bottom line. The company traditionally reports in US dollars as most of its revenue is derived from there. However, with the Australian currency rising against the greenback, this will deflate Appen’s potential earnings. Currently, US$1 buys A$1.36.

    Appen is scheduled to report its financial results for FY21 on 26 August 2021.

    Is Appen shares a buy?

    The most recent broker note came from Bell Potter in mid-June. The investment firm cut its 12-month price target by 5.3% to $13.50 for Appen shares. Based on the current share price, this implies an upside of around 9%.

    The post Appen (ASX:APX) share price drops after a fantastic week appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Appen right now?

    Before you consider Appen, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Appen wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras owns shares of Appen Ltd. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Appen Ltd. The Motley Fool Australia owns shares of and has recommended Appen Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3fKghqz

  • Telstra (ASX:TLS) share price rises after regional frequency win

    farmer on telephone enjoying telecommunications in rural area

    The Telstra Corporation Ltd (ASX: TLS) share price is in the green. It comes amid news the company has secured a “win” over new regional radio frequency limits set by the Federal Government.

    Telstra shares are trading for $3.82 as of writing – up 0.39%. The S&P/ASX 200 Index, meanwhile, is 0.19% higher.

    Let’s a closer look at today’s news.

    Telstra share price on the rise

    According to a report in the Sydney Morning Herald (SMH), Communications Minister Paul Fletcher has agreed to a 45% purchase limit of low-band frequency for telcos in regional areas. It exceeds the ACCC’s recommendation of 40% and even the 43% that Telstra had asked for.

    Telstra is already the leading telco, ahead of competitors like Optus and TPG Telecom Ltd (ASX: TPG), in regional areas – at least according to consumer website Finder.

    The government will auction off the rights to the low-band spectrum later this year. The lease will last for 20 years.

    Investors appear to have welcomed today’s news, judging by the Telstra share price movement.

    Defending his decision to go above the competition watch dog’s recommendation, Fletcher said (as quoted in the SMH):

    We very carefully configured this so that we don’t end up with an auction outcome that leaves the customers of Optus or TPG worse off.

    Let’s be clear, [Optus and TPG] will be able to get significant additional spectrum should they want it in both regional and metro under these limits.

    Telstra CEO Andy Penn welcomed the decision, saying:

    It will mean we can bid for enough spectrum to maintain our leading mobile network.

    Recent Telstra and government dealings

    As Motley Fool has previously reported, the Federal Government and Telstra are working on a deal to buy Pacific mobile provider Digicel for approximately $2 billion.

    Apparently, the Government’s interest in the Pacific telco relates to national security concerns.

    “…Beijing could use the [Digicel] networks to spy on political elites and neighbouring island nations”, according to the Australian Financial Review.

    The Commonwealth will provide “significant debt financing” to Telstra to finance the acquisition.

    The Telstra share price lifted on the news.

    Telstra share price snapshot

    Over the past 12 months, the Telstra share price has underperformed the ASX 200 by about 11 percentage points. It’s increased about 12% in that time to the index’s 23%. Year-to-date, however, it has overperformed the benchmark 27% to 13%.

    Telstra Corporation has a market capitalisation of $45.2 billion.

    The post Telstra (ASX:TLS) share price rises after regional frequency win appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Telstra right now?

    Before you consider Telstra, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Telstra wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Marc Sidarous has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Telstra Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3xC39Ka

  • Amazon stock: Investors expect too much

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    amazon prime plane 16:9

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

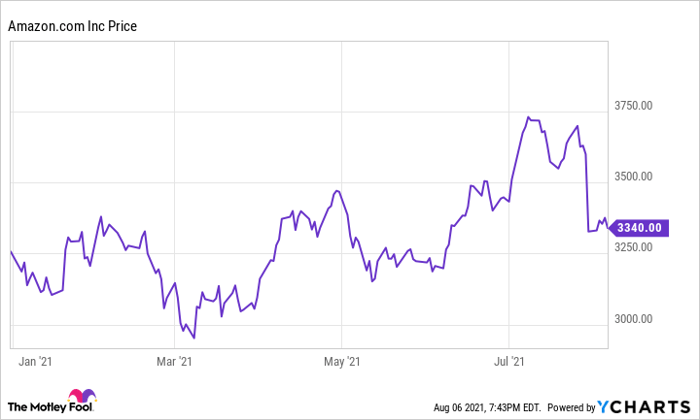
    Just a few weeks ago, shares of Amazon.com (NASDAQ: AMZN) touched a new all-time high above $3,700. This pushed the retail and technology giant’s fully diluted market cap to just shy of $2 trillion.

    However, Amazon stock pulled back 8% after its late-July earnings report, as second-quarter revenue fell short of the analyst consensus and the company issued a weaker-than-expected forecast for the third quarter. While Amazon continues to produce very strong results by ordinary standards, these disappointments suggest that investors may have unrealistic expectations for the e-commerce titan.

    AMZN Chart

    Amazon.com stock performance, data by YCharts.

    Failing to meet high expectations

    Amazon generated $113.1 billion of revenue last quarter: up 27% year over year. Holding currency exchange rates constant, sales would have increased 24%. All three of Amazon’s business segments posted solid gains. On a constant-currency basis, revenue rose 21% in the North America division, 26% in the international segment, and 37% for Amazon Web Services.

    Most companies would love to achieve that kind of growth under any circumstances. Still, analysts had (on average) expected revenue to come in $2 billion higher.

    Interestingly, Amazon’s growth rate in North America trailed the broader retail industry. U.S. retail sales surged 27.8% year over year last quarter, as consumers flocked back to stores as the COVID-19 pandemic eased. Moreover, Amazon’s Q2 revenue benefited from Prime Day shifting into June this year. The two-day event brought in about $7.5 billion of revenue, according to estimates from Piper Sandler analysts. (For comparison, Amazon’s retail business has been generating about $1 billion of revenue on a typical day recently.)

    Operating income jumped 32% year over year to $7.7 billion: near the top of Amazon’s $4.5 billion to $8 billion guidance range. Nevertheless, this probably missed many investors’ expectations, as the company often beats the high end of its operating income guidance by a wide margin.

    More of the same ahead

    Amazon’s third-quarter forecast also disappointed many investors. The company projects that revenue will increase 10% to 16% year over year to a range of $106 billion to $112 billion. Meanwhile, Amazon estimates that operating income will decline from $6.2 billion a year ago to between $2.5 billion and $6 billion. The analyst consensus had called for revenue of $118.7 billion and operating income of $8.1 billion.

    With Prime Day falling in the second quarter this year, investors had to be prepared for slower growth in the third quarter. Furthermore, Amazon faces tough year-over-year comparisons after revenue surged 37% in Q3 2020.

    That said, it also appears that many consumers — particularly in the U.S. — have started to return to their pre-pandemic shopping habits due to the widespread availability of COVID-19 vaccines. During Amazon’s earnings call, CFO Brian Olsavsky noted that growth had slowed to a mid-teens pace beginning in mid-May, excluding the impact of the Prime Day calendar shift.

    Why investors should expect slowing growth

    Prior to the COVID-19 pandemic, Amazon’s growth rate had already started to moderate. On a constant-currency basis, revenue rose 22% in 2019, down from 30% in 2018 and 31% in 2017.

    The pandemic drove a huge increase in e-commerce sales, reversing this trend of slowing growth. As a result, Amazon posted a 37% revenue gain in constant currency last year. However, to some extent, this just pulled forward growth that would have come in 2021 and future years. That has led to the sharp deceleration Amazon is experiencing now — and which will likely continue in the near term.

    Indeed, while Amazon’s growth rate for 2020 and 2021 combined looks quite strong, U.S. retail sales have grown at an incredible pace over this period. As the tailwind from stimulus checks and reduced spending on experiences (like travel and dining out) fades, it will pressure Amazon’s top-line growth. Additionally, Amazon has already crushed most of its weak competitors, which will make it harder to gain market share in the future.

    Amazon stock could still potentially be a worthwhile long-term investment depending on the company’s ability to expand its profit margin. However, investors will need to recalibrate their expectations for top-line growth. The low- to mid-teens growth Amazon is projecting for the third quarter could prove to be the new normal over the next several years.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Amazon stock: Investors expect too much appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Amazon right now?

    Before you consider Amazon, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Amazon wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Adam Levine-Weinberg has no position in any of the stocks mentioned. John Mackey, CEO of Whole Foods Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Amazon. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended the following options: long January 2022 $1,920 calls on Amazon and short January 2022 $1,940 calls on Amazon. The Motley Fool Australia has recommended Amazon. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3yx89kI

  • Brickworks (ASX: BKW) share price down 5% as operations curtailed

    a man peers through a broken brick wall to see grey clouds gathering beyond it

    The Brickworks Ltd (ASX: BKW) share price is under heavy selling pressure on Monday after the company was forced to cut back operations at facilities in New South Wales and Queensland.

    Investors were quick to react to the negative news, with the Brickworks share price sliding 5.38% to $23.74 within the first 10 minutes of trade.

    At the time of writing, shares in the building products and property developer are down 3.26% to $24.35.

    Why the Brickworks share price is tumbling on Monday

    The recent outbreak of COVID-19 across NSW and Queensland and consequent lockdowns has seen a significant decline in building product sales.

    Management said that brick sales in NSW were in line with local production capacity during June and in early July.

    However, “dispatches abruptly reduced by 80% during the pause in construction activity across Sydney in late July. These were the most severe restrictions that our business has faced since the onset of the pandemic …”

    The company said the partial recommencement of construction activity in August resulted in some degree of improvement for brick sales. However, it only represents 50% of pre-lockdown levels.

    With the company’s production outstripping demand, a number of storage yards were quick to reach full capacity.

    “As such, we have been forced to temporarily curtail production at two of our five brick kilns across the state, representing 30% of total production capacity.”

    Encouragingly, management said that it has no intention of laying off any workers and has committed to working with its staff to “preserve their employment throughout this period of uncertainty”.

    Impact on earnings

    Given the timing of restrictions in NSW, just two weeks prior to the end of Brickworks’ financial year, management does not expect a material impact on its FY21 performance.

    However, the company flagged the NSW restrictions are having a material impact on current building products earnings.

    Management added that “with the situation remaining highly volatile and unpredictable, it is difficult to quantify the ongoing impact and we have no confidence in being able to accurately forecast business performance until there is a full reopening of construction activity across the state”.

    Brickworks share price snapshot

    Despite today’s sharp selloff, the Brickworks share price is still up 27% year-to-date.

    The company’s upbeat trading update on 9 June was a major catalyst behind its solid performance this year.

    The post Brickworks (ASX: BKW) share price down 5% as operations curtailed appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Brickworks right now?

    Before you consider Brickworks, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Brickworks wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Brickworks. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3CupE7G

  • IAG (ASX:IAG) share price lifts following major board reshuffle

    A line of people sitting at a long desk in a meeting

    The Insurance Australia Group Ltd (ASX: IAG) share price is rising after the insurer revealed a major board reshuffle.

    IAG is the parent business of a number of insurance companies across Australia and New Zealand such as NRMA Insurance, CGU, SGIO, SGIC, Swann Insurance, WFI, NZI, State, AMI and Lumley. It also has an interest in a general insurance joint venture in Malaysia.

    IAG’s board retirements

    The IAG Chair, Elizabeth Bryan, will retire from the company at the annual general meeting (AGM) on 22 October 2021 after six years leading the business.

    To replace her, the new chair will be Tom Pockett. Mr Pockett has been a director of the business since 2015 and chair of the audit committee. He is also the chair of both Stockland Corporation Ltd (ASX: SGP) and Autosports Group Ltd (ASX: ASG).

    Ms Bryan said:

    The IAG board under Mr Pockett’s chairmanship will be a strong one that will combine a deep understanding of IAG and its Australian and New Zealand business with its new members’ deep insight into the developments taking place in the international general insurance market.

    A second director, Duncan Boyle, will also retire from IAG’s board on 22 October 2021. Mr Boyle has served on the board for five years, including three years as the chair of the risk committee.

    Chair Ms Bryan acknowledged the contribution that Mr Boyle had made to the board’s deliberations with its long experience of the global insurance industry.

    With the impacts of COVID-19 still being felt, the IAG share price is down 5% over the last five years.

    New directors

    IAG also announced that three new directors will join as part of the process to renew the board to ensure it has the right mix of skills and experience to support the company.

    The company said that the new directors “bring deep insurance and public company governance experience to their roles, and their skills will supplement those of the existing directors.”

    The three new directors are: David Armstrong, George Sartorel and Scott Pickering.

    Mr Armstrong will become the new chair of the audit committee, at the end of the 2021 AGM. IAG said he is a well-known and highly respected company director. The insurer also said that he’s a former partner with PwC specialising in financial services. He has a “deep knowledge” of audit and risk control, and experience with Australian public companies.

    Mr Sartorel has had a long career with Allianz Group and was most recently the regional chief executive of the Asia Pacific division. IAG said that he had returned home to Australia and brings with him experience in creating and leading large, innovative insurance companies with digital business models.

    The company noted that Mr Pickering has also had a successful international career as a global insurance executive. He has had senior leadership positions with Royal Sun Alliance and Willis Towers Watson. Mr Pickering has recently retired from the role of CEO of the NZ Accident Compensation Corporation.

    IAG share price

    The IAG share price is up 4% at the time of writing. That brings the market capitalisation to $12.3 billion according to the ASX.

    The post IAG (ASX:IAG) share price lifts following major board reshuffle appeared first on The Motley Fool Australia.

    Should you invest $1,000 in IAG right now?

    Before you consider IAG, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and IAG wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Insurance Australia Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3iv3LNf