Category: Stock Market

  • Here’s why the Oneview (ASX:ONE) share price is climbing today

    Group of doctors celebrate by pumping fists in the air

    The Oneview Healthcare PLC (ASX: ONE) share price is in the green today. Shares in the healthcare company received a boost after Oneview released its quarterly report earlier today.

    At the time of writing, Oneview shares are up 2.27% to 45 cents.

    Let’s take a look at how Oneview performed in the second quarter of 2021.

    Oneview share price rises on quarterly report

    Earlier today, Oneview released its report for the second quarter ending 30 June 2021.

    The company’s financial performance was highlighted by a 42% increase on the previous corresponding period (pcp) in net operating cash outflows to €1.24 million ($2 million). This included €1.98 million ($3.18 million) in receipts from customers, a 56% increase on the pcp.

    Despite a growing cash outflow, Oneview reported increased administrative and marketing costs for the quarter.

    The company also noted a stable balance sheet, with a cash balance of €5.0 million ($8.03 million) as at 30 June 2021.

    Oneview reports strong operational highlights

    In addition to the company’s financial performance for the quarter, Oneview also elaborated on its operational achievements.

    In particular, Oneview highlighted the company’s 5-year contract extension with its largest customer in Australia, Epworth HealthCare. Oneview also noted its 5-year contract with Northern Health in Melbourne.

    Oneview also said it continues to work with its new partner Samsung. Early feedback from their combined market strategy has shown a preference for Cloud Enterprise vs. Cloud Star.

    The second quarter of 2021 marked the first quarter of sales and marketing for Oneview’s Cloud Enterprise product. The company’s management was pleased with the market response and foreshadows a material increases in its sales pipeline.

    Snapshot of the Oneview share price

    Oneview is an Irish healthcare technology company that provides digital tools for patients and their caregivers.

    Facilities systems and services are unified on Oneview’s Care Experience Platform with the aim of improving the overall care experience.

    The company currently services 63 hospitals, operating in the US, Australia, the Middle East, and Asia.

    The Oneview share price has had a stellar year thus far. Shares in the healthcare technology company have surged more than 948% since the start of the year.

    The post Here’s why the Oneview (ASX:ONE) share price is climbing today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Oneview right now?

    Before you consider Oneview, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Oneview wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Nikhil Gangaram has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3BKryAu
  • Here’s why the Zip Co (ASX:Z1P) share price is leaping 5% today

    happy woman using phone outside

    The S&P/ASX 200 Index (ASX: XJO) is having a pretty decent day on the markets this Thursday. At the time of writing, the ASX 200 is up a robust 0.37% to 7,407 points. But one ASX 200 share that’s doing a few better is the Zip Co Ltd (ASX: Z1P) share price.

    Zip shares are currently up a healthy 4.57% to $6.86 a share, after closing at $$6.56 yesterday afternoon and opening at $6.65 a share this morning.

    Like its typical pattern of late, Zip has had a wild week. Even though the company is up more than 5% today, Zip shares are still down almost 3% over the past 5 trading days, and down more than 10% over the past month.

    The entire buy now, pay later (BNPL) sector was rocked by news earlier this month that both Apple Inc (NASDAQ: AAPL) and PayPal Holdings Inc (NASDAQ: PYPL) would be expanding their BNPL products.

    In Apple’s case, it was a rumour that the electronics giant would be introducing a BNPL version of its popular Apple Pay service in ‘Apple Pay Later’. In PayPal’s case, it was the news that the company would be abolishing late fees on its own BNPL ‘Pay in 4’ service.

    This news (which came out on the same day) really spooked BNPL investors, and the Zip share price (along with other ASX BNPL shares) has struggled ever since.

    So what’s going on with this BNPL ASX share today?

    Zip shares zip higher

    Well, it’s not immediately obvious what has lit a rocket under Zip shares today, thus far. There have been no major news or announcements out of the company since 22 July, when Zip delivered its quarterly results report.

    However, there is an obvious pattern today which Zip is clearly a part of. Most ASX BNPL shares are enjoying very healthy gains this Thursday. Take Zip’s arch-rival Afterpay Ltd (ASX: APT). Afterpay shares are currently up 3.4% to $102.35 a share. Sezzle Inc (ASX: SZL), Openpay Group Ltd (ASX: OPY) and Splitit Ltd (ASX: SPT) are also performing very well today.

    The US BNPL company Affirm Holdings Inc (NASDAQ: AFRM) was also up big last night in US trading hours. Affirm shares rose a very enthusiastic 2.82% to finish the trading day at US$61.18 a share. Perhaps ASX investors have taken a lead from our American counterparts, and seen fit to pick up BNPL shares for relatively cheap prices today.

    At the current Zip share price, the company has a market capitalisation of $3.68 billion.

    The post Here’s why the Zip Co (ASX:Z1P) share price is leaping 5% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Zip Co right now?

    Before you consider Zip Co, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Zip Co wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Sebastian Bowen has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended AFTERPAY T FPO, Affirm Holdings, Inc., Apple, PayPal Holdings, and ZIPCOLTD FPO. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended the following options: long January 2022 $75 calls on PayPal Holdings, long March 2023 $120 calls on Apple, and short March 2023 $130 calls on Apple. The Motley Fool Australia owns shares of and has recommended AFTERPAY T FPO. The Motley Fool Australia has recommended Apple and PayPal Holdings. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3f9pNDf

  • Own CSL (ASX:CSL) shares? Here’s what to look for this reporting season

    patient with doctor, medical company, medical insurance

    The CSL Limited (ASX: CSL) share price has struggled to deliver shareholder value in 2021, with a year-to-date return of about 2.05%.

    With August reporting season on the horizon, what should investors look out for in the company’s results?

    All eyes on plasma collections

    In CSL’s annual report to shareholders, it said “at the origins of our value chain, plasma donors fuel our pipeline …”.

    Plasma collections form the backbone of many CSL treatments including its immunoglobulins business, which contributed approximately 43% of the group’s 1H21 revenue.

    The last time CSL updated the market on its plasma collections was February, when the company released its FY21 half-year results.

    It advised “plasma collections adversely impacted by COVID-19” and that collection volumes in December 2020 were roughly 80% of the December 2019 volumes.

    The company launched multiple initiatives in an attempt to drive plasma collection figures. This included enhanced targeted marketing, improving the donor experience and the rollout of 29 new collection centres in FY21.

    The CSL share price will be put to the test as to whether or not these initiatives are paying dividends.

    CSL competitor notes recovery in plasma collections

    The Motley Fool has previously covered observations of a plasma donation recovery in the United States.

    Grifols, a US$14 billion Spanish multinational biotech company has observed some improvements in the plasma collections space.

    In the company’s quarterly results on 4 May, it said, “In the United States, plasma donations are gradually recovering. Of note was the trend observed in January, February and April in the wake of the country’s vaccination rollouts and the easing of COVID-19 restrictions, while taking into account the mitigating effect of stimulus incentives issued in March and December.”

    CSL share price tumbles on seemingly good results in February

    It can be difficult to get a read on how the CSL share price will perform after the release of its full-year results on 18 August.

    Looking back, the company delivered seemingly positive half-year results on 18 February with a 15% increase in revenue to US$4,911 million and a 44% jump in net profit after tax (NPAT) to US$1,248 million.

    CSL acknowledged that COVID-19 had “tempered the performance of CSL Behring whilst boosting the performance of Seqirus”.

    The company reaffirmed its (NPAT) guidance of US$2,170 million to US$2,265 million for FY21, which represents an increase of 3.2% to 7.7% on FY20 figures.

    The CSL share price closed at $289.00 on 18 February and tumbled from there. It hit a year-to-date low of $246.00 on 8 March. The shares have since rallied to a year-to-date peak of $305.52, which it reached on 18 June.

    At the time of writing today, the CSL share price is $290.53, up 1.94%.

    The post Own CSL (ASX:CSL) shares? Here’s what to look for this reporting season appeared first on The Motley Fool Australia.

    Should you invest $1,000 in CSL right now?

    Before you consider CSL, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and CSL wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended CSL Ltd. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3l3PZ6d

  • Capital keeps flowing into ASX Biotech shares in 2021

    woman in lab coat conducting testing representing biotech

    Investor funds continue flowing into ASX listed biotechnology shares this year, with a total of almost $485 million of capital raised this year to date.

    Adding the flurry of initial public offerings (IPO) undertaken in the biotech domain, one observes that this total increases to over $1 billion, according to today’s Australian Financial Review.

    Here, we examine just what is driving this recent trend in capital inflows towards ASX Biotech shares.

    What is behind the surge in inflows to ASX Biotech shares this year?

    There has been a spate of capital raised for ASX Biotech shares this year, such as Imugene Limited (ASX: IMU), Immutep Ltd (ASX: IMM) and Aroa Biosurgery Ltd (ASX: ARX).

    For instance, Imugene recently “completed an upsized $95 million offer”, issuing ~300 million additional shares at a price of 30 cents apiece.

    Aroa also “banked $53 million in a placement and share purchase plan [SPP]” earlier this week to eligible investors at $1.165 per share. $5 million of this total is sought from the SPP.

    There appears to be “four big reasons behind the recent flurry of [capital] raising” trends that have occurred this year.

    These include the establishment of new equity-focused healthcare investment funds, outsized returns in the broad sector, and a cluster of collaborations with big pharmaceutical companies.

    Moreover, it also appears the biotech sector “has the flavour of the month for investors”, as per the Financial Review.

    Bell Potter Securities analyst Darren Craike was quoted saying:

    A lot of generalist funds are looking for alpha [above market return] in their portfolios…so many have started to gravitate to healthcare where there have been some exceptional returns in the last two to three years.

    Moreover, the trends look set to continue for the time being, with a number of pre-IPO’s on the cards.

    To illustrate, Tissue Repair which is a regenerative medicine and aesthetic dermatology company, plans on “targeting a $25 million raise” via listing this year.

    Additionally, upcoming biotech names Triad Lifesciences and Vitfrafy Lifesciences “are also confirmed to be pursuing listings” this year.

    ASX Biotech shares snapshot

    The basket of ASX Biotech shares contained within the S&P / ASX 200 Index (ASX: XJO) has provided a return of 116% since March of this year.

    This select group has outpaced the overall broad index, which has posted a return of ~12.5% this year to date.

    Such returns help to explain the attractiveness of ASX Biotech shares for Australian investors at the current standing.

    The post Capital keeps flowing into ASX Biotech shares in 2021 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    from The Motley Fool Australia https://ift.tt/2UZRYh9

  • Ramelius (ASX:RMS) share price lifts on record production

    Closeup of a smiling man holding a jar containing nuggets of gold

    The Ramelius Resources Limited (ASX: RMS) share price is trading higher on Thursday. This comes after the company released its June quarterly and full-year FY21 activities report.

    At the time of writing, shares in the gold mining company are up 2.17% to $1.65.

    What did Ramelius announce?

    Investors are bidding the Ramelius share price higher this afternoon after the company’s shares opened 1.54% lower at $1.595.

    The mid-tier gold mining company reported record full-year FY21 production of 272,109 ounces at an all-in sustaining cost (AISC) of A$1,317/oz.

    This compares to the company’s revised guidance of 275,000 to 280,000 ounces at an AISC of A$1,280 to $1,330/oz

    Pleasingly, the company’s FY21 production figures represent an 18% increase from FY20 production of 230,426 ounces.

    Ramelius advised it had a $228.5 million cash position and an addition $5.4 million of gold bullion on hand as at 30 June 2021.

    In addition, the company managed to reduce its debt position to nil. This followed the final debt repayment of $8.1 million at the end of the quarter.

    Looking ahead

    Ramelius could be poised for more growth in FY22 with gold production forecasted to be between 260,000 and 300,000 ounces.

    However, its costs are expected to increase with an FY22 AISC forecast of A$1,425 to A$1,525/oz.

    The company is forecasting an exploration expenditure for FY22 of $32.1 million.

    What’s happening to the Ramelius share price in 2021?

    It’s been a tough year for both the Ramelius share price and the broader ASX gold mining sector.

    Ramelius shares are down 6.46% year-to-date despite continuing to make headway in its production and exploration activities.

    Top-tier ASX-listed mining shares — from low-cost producer Newcrest Mining Ltd (ASX: NCM) to growth-focused Northern Star Resources Ltd (ASX: NST) — also have negative year-to-date returns.

    One of the major catalysts behind the weak performance of gold miners this year is the gold spot price. Gold prices have slumped 4.3% year-to-date from US$1,898 to US$1,816.

    The post Ramelius (ASX:RMS) share price lifts on record production appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Ramelius right now?

    Before you consider Ramelius, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Ramelius wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3fahzuy

  • CV Check (ASX:CV1) share price rockets 9% on business update

    A drawing of a white rocket streaking up, indicating a surging share pirce movement

    The CV Check Ltd (ASX: CV1) share price is storming ahead today following the release of its fourth quarter results.

    At the time of writing, the online integrated screening and verification company’s shares are up 9.68% to 17 cents.

    Let’s take a closer look and see how the company performed for the 3 months.

    CV Check delivers record growth

    Investors appear excited by the company’s latest trading update, sending CV Check shares to a 5-month high.

    For the quarter ending 30 June, CV Check achieved group record revenue of $6.4 million, a 262% increase on the prior corresponding period. The strong result was driven by growth in the Australian and New Zealand economy as well as the acquisition of the Bright People Technologies (BPT) business.

    Net cash from operating activities during Q4 FY21 came to $585,000, adding to its FY21 total of $1.5 million.

    CV Check declared a healthy cash bank balance of $12.9 million with no external financing. During April, $1.3 million was paid to clear BPT’s outstanding debt.

    Annual Recurring Revenue (ARR) stood at $13.3 million, compared to $11.1 million at the end of March 2021. This reflects a growth of 19.8% and a record for 12-month booked ARR.

    The CV Check platform delivered $5 million in revenue for Q4 FY21, up 104% from this time last year ($2.4 million). B2B integrations with HR information systems and applicant tracking systems contributed $0.7 million. Notably, this represents a massive 420% gain over the prior comparable period.

    In addition, the company won new customers during the quarter with several booking their first orders. They included Rheinmetall Defence Australia, Think Childcare, Water NSW, Whitehaven Coal, Winning Appliances Group, among other brands.

    What did management say?

    CV Check executive chair, Ivan Gustavino commented on the result, saying:

    As expected, the quarter under review was a significant period of consolidation for CV1 after the acquisition of BPT. That the business was still able to deliver record revenues for a quarter and for booked 12-month ARR speaks volumes of the calibre of the team. Across both sides of the business, all channels performed strongly: direct sales revenue, revenues booked through integration partners and revenue from the international wholesale sales channel.

    CV Check share price summary

    It has been a whirlwind 12 months for CV Check shareholders. The company’s shares reached as high as 21 cents in February and then fell to 12 cents a few months after. The CV Check share price is up almost 90% in the past year but is down 10% in 2021.

    Based on today’s price, CV Check presides a market capitalisation of roughly $72.9 million and has 428 million shares outstanding.

    The post CV Check (ASX:CV1) share price rockets 9% on business update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in CV Check right now?

    Before you consider CV Check, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and CV Check wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended CV Check Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3j1XXtI

  • Why the Resolute Mining (ASX:RSG) share price is crashing 8% today

    A man stands in front of a chart with an arrow going down and slaps his forehead in frustration.

    The Resolute Mining Limited (ASX: RSG) share price has been a very poor performer on Thursday.

    At the time of writing, the gold miner’s shares are down almost 8% to 52 cents.

    Why is the Resolute Mining share price sinking today?

    The weakness in the Resolute Mining share price today has been driven by the release of a disappointing quarterly update.

    During the second quarter of FY 2021, Resolute Mining reported gold production of 77,450 ounces. This represents a 10% decline on production during the first quarter.

    This was driven largely by its Syama Sulphide operation, which reported a 10% reduction in production to 33,463 ounces. It also recorded an all-in sustaining cost (ASIC) of $1,339 per ounce at the operation, up 5.1% quarter on quarter. This was the result of record levels of mining, processing, and roaster throughput, which were offset by power disruptions, an extension of scheduled mill maintenance, and lower grades.

    The company’s Syama Oxide operation also reported a decline in production and an increase in costs. It saw production fall 13.4% to 13,424 ounces with a 12.6% higher ASIC of $1,466 per ounce. Management advised that record tonnes were processed but offset by lower blended grades and increase in circuit stocks.

    Finally, its Mako operation reported a 7.2% decline in production and 5.6% increase in its ASIC to $1,094 per ounce. Management advised that this was in line with expectations during its cut-back phase.

    Sales decline

    Also declining during the quarter, and potentially weighing on the Resolute Mining share price today, were its sales.

    According to the release, the company sold 68,103 ounces of gold during the quarter. This was down 18% on the previous quarter. One small positive was that its average realised price increased by 0.9% to $1,714 per ounce.

    However, due to a 7% increase in its group AISC to $1,319 per ounce, its margin fell to $395 per ounce from $490 per ounce in the first quarter.

    FY 2021 guidance downgraded

    Unsurprisingly, given its poor performance during the second quarter, management does not expect to achieve its FY 2021 production guidance of 350,000 ounces to 375,000 ounces. Nor does it expect its ASIC to be within its guidance range of $1,200 to $1,275 per ounce.

    Resolute Mining is now expecting production of 315,000 ounces to 340,000 ounces with an ASIC of $1,290 to $1,365 per ounce.

    Following today’s decline, the Resolute Mining share price is now down 38% in 2021.

    The post Why the Resolute Mining (ASX:RSG) share price is crashing 8% today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Resolute Mining right now?

    Before you consider Resolute Mining, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Resolute Mining wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3l7nWCP

  • Should you buy Mineral Resources (ASX:MIN) shares in July for the dividend yield?

    happy woman looking at her laptop with notes of money coming out representing financial success and a rising share price and dividend yield

    After a recent run-up on the charts, Mineral Resources Limited (ASX: MIN) shares have delivered a total return of 155% over the past 12 months.

    Mineral Resources shareholders have enjoyed this total return as a combination of capital gains and dividend payments of $1.77 per share over this period.

    Here, we evaluate Mineral Resources shares from the perspective of their dividend yield, for the benefit of investors who are considering buying the stock ahead of its next dividend announcement in August.

    Some history on the Mineral Resources dividend

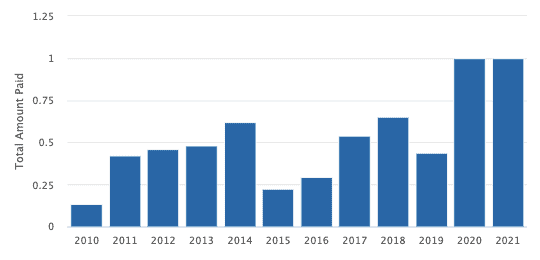
    Mineral Resources has been returning cash to its shareholders via its dividend since November 2010.

    Over this ten-year period to date, the company has made good on each respective payment, completing two dividend payouts a year.

    Mineral Resources was even able to increase its dividend throughout the pandemic, in a testament to the resilience of its dividend program and business model.

    Exhibit 1. Mineral Resources Dividend Payments, 2010 – 2021 (current).

    Source: The Motley Fool Australia

    From November 2010 to March this year, Mineral Resources’ dividend payout has grown at a compound annual growth rate (CAGR) of approximately 20%.

    In addition, the dividend is fully franked, meaning there is no ‘double taxation’ on the income for shareholders.

    The company pays this tax before distribution, and this is credited to shareholders by way of franking credits.

    What does the dividend look like today?

    Let’s look back a little further than July 2020 to get a better scope on Mineral Resources’ dividend situation.

    Mineral’s most recent dividend payment was $1.00 on 9 March, meaning total dividends received from 26 March 2020 to 9 March 2021 equals $2.00 per share.

    In other words, investors who held 100 shares in Mineral Resources over this time period would have received a total pay-off of $200 in dividend income (100 x $2.00 = $200).

    But what about the dividend yield?

    When considering an investment in Mineral Resources shares to capture the dividend payment, the concept of dividend yield is relevant.

    Put simply, the dividend yield is a financial ratio that states the return an investor will receive from a company’s dividend payouts, based on its current share price.

    For instance, if an investor were to allocate $1,000 to shares that are returning an annual dividend yield of 5%, they can expect a return of 5% on their initial investment, or $50 per year, from the dividends alone.

    Note the above calculation excludes any share price movements up or down over the holding period.

    Furthermore, there is an inverse relationship between dividend yield and share price. When the share price goes up, yield goes down and vice versa.

    Given that Mineral Resources’ share price has exhibited considerable appreciation over the past year, it stands to reason that its dividend yield has declined over this time. However, its dividend payout increased, both on an interim and final payment basis.

    Taking the total of $2.00 per share (from March 2020 – March 2021) and dividing this by Mineral Resources’ share price of $63.24 at the time of writing, we arrive at a trailing yield of 3.16%.

    Therefore, assuming no change in share price or dividend payouts, an investment of $1,000 in Mineral Resources shares today would land a return of $31.60 for the year.

    Looking forward — what about the yield, then?

    It is unrealistic to assume no change in the share price or dividend payments over the coming periods. Besides, Mineral Resources has increased its payouts at a CAGR of 20% over the past 10 years, as mentioned.

    Looking forward, it is uncertain what Mineral’s final dividend will look like when it is announced in August.

    However, the analysts at JP Morgan forecast a dividend yield of 5.8% for FY21 and 6% for FY22.

    These forecasts imply growth in dividends and also growth in the dividend yield, at the current market price.

    Given these forecasts and the repeated pattern of dividend growth over the past 10 years, coinciding with share price appreciation on the charts, it stands to reason that JP Morgan likes Mineral Resources’ dividend yield prospects.

    Consequently, the investment bank has assigned a price target of $64.00 on the shares. This implies an upside potential of ~1.2% at the time of writing.

    At that current price, Mineral Resources has a market capitalisation of $11.96 billion and trades at a price-to-earnings (P/E) ratio of 18.73.

    The post Should you buy Mineral Resources (ASX:MIN) shares in July for the dividend yield? appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    The author Zach Bristow has no positions in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3x9Bdx1

  • Oil Search (ASX:OSH) share price struggles despite rising oil price

    barrel of oil sitting on top of falling red arrow representing asx energy shares downgrade

    The Oil Search Ltd (ASX: OSH) share price has been struggling recently despite the price of oil increasing.

    After hitting a low of US$68.62 10 days ago, the price of Brent Crude Oil is currently US$74.70 per barrel.

    The WTI Crude Oil price has followed a similar trajectory, hitting US$66.42 on 19 July before rebounding to trade for US$72.35 per barrel today.

    Oil Search’s shares originally gained alongside oil. They increased 11% between 19 July and 22 July.

    However, they’ve fallen 4.66% since. The Oil Search share price is currently $3.89, 0.77% lower than yesterday’s close.

    Let’s take a look at what might be driving oil prices up, and what’s likely weighing on Oil Search.

    The Oil Search share price is dropping despite good news for oil prices.

    According to reporting by Reuters, the United States’ crude oil inventories are falling faster than was predicted.

    The publication states crude inventories fell by 4.1 million barrels over the course of last week, with some analysts believing OPEC+’s agreement to increase supply won’t cut it.

    Additionally, Reuters reported that the increasing numbers of COVID-19 cases worldwide have hampered oil production, while long-term recovery from the pandemic will likely increase demand.

    All this is putting upwards pressure on the price of oil.

    At the same time the oil price is rising, Oil Search is facing uncertainty.

    First off, the company has seemingly entered a bidding war with Santos.

    Santos Ltd (ASX: STO) sent Oil Search a merger offer late last month. The merger offer went public last week when Oil Search rejected it.

    The Oil Search share price gained 3.5% on the back of the merger’s rejection.

     Now, it looks like the companies will begin fighting in the hopes that Santos can offer a price Oil Search deems worthwhile. In fact, earlier this week, Oil Search’s interim CEO Peter Fredricson said that the company wants “more carats in the diamond ring”.

    And all the while, Oil Search is without a long-term leader after its former managing director Dr Keiran Wulff walked out on 19 July.

    According to the company, its board had faced problems with Wulff’s behaviour. Wulff was also said to have left due to health issues.

    The Oil Search share price increased substantially on the day of Wulff’s departure. It closed 6.2% higher than the session prior.

    Oil Search share price snapshot

    Oil Search is in the ASX green by the skin of its teeth.

    Right now, it’s 3.3% higher than it was at the start of 2021. It has also gained 29.8% since this time last year.

    The post Oil Search (ASX:OSH) share price struggles despite rising oil price appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Oil Search right now?

    Before you consider Oil Search, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Oil Search wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/2UYqk48

  • Why the Brainchip (ASX:BRN) share price is falling today

    woman consoles robot

    The Brainchip Holdings Ltd (ASX: BRN) share price is in the red today.

    At the time of writing, shares in the artificial intelligence (AI) developer are trading for 45 cents each – down 2.15%. The All Ordinaries Index (ASX: XAO) is up 0.5% while the S&P/ASX All Technologies Index (ASX: XTX) is 2.12% higher.

    The price fall comes after the company released its update for the June quarter.

    Let’s take a closer look.

    Company profile

    Brainchip shares are some of the most popular on the ASX, regularly making the list for traded shares in the week. That’s despite the fact the company has a market capitalisation of less than $1 billion.

    According to Brainchip, the company is “a global technology company that is producing a ground-breaking neuromorphic processor that brings artificial intelligence to the edge in a way that is beyond the capabilities of other products”.

    Why the Brainchip share price is down

    In a statement to the ASX, Brainchip gave an update on its cash position and activities during the last quarter. Overall, the company experienced a cash outflow of US$2.3 million for a total cash position of US$17.7 million.

    The main contributor to this position was a US$900,000 drop in customer receipts, a payment of US$2.25 million to a supplier, and more employees at the company. Brainchip collected a net inflow of US$733,000 from financing and equity options being exercised.

    Investors may not be impressed with these numbers, judging by the fall in the Brainchip share price.

    During the quarter, the company also made a number of announcements. These included:

    • The replacement of a member of the board.
    • An additional expert to its scientific advisory board.
    • The holding of its AGM.
    • The upgrading of its shares on the OTC market based in New York, NY.

    Brainchip share price snapshot

    Over the past 12 months, the Brainchip share price has increased 172%. Year-to-date, its value has appreciated only 7%.

    In December 2020, Brainchip shares rocketed 57% in a single day after announcing a partnership with NASA.

    The Brainchip record high is 97 cents per share, which is more than double its current share price.

    The post Why the Brainchip (ASX:BRN) share price is falling today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Brainchip right now?

    Before you consider Brainchip, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Brainchip wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3f4vJh2