Category: Stock Market

  • 2 ASX shares hitting record highs this week

    asx share investor climbing up stairs of an upward trending graph

    The Ansell Ltd (ASX: ANN) and Healius Ltd (ASX: HLS) share prices both set new 52-week highs this week.

    Let’s take a look at each individually and the recent events for each ASX share.

    A look at Ansell’s share price

    The Ansell share price hit a record high yesterday at $43.23, trading above the 52-week low of $33.23 on 8 December 2020.

    Shares in the global player for health and safety protection solutions have climbed 22.67% year-to-date, outpacing the S&P/ASX 200 Index (ASX: XJO)’s 11% at the time of writing.

    The company’s shares have also posted another 4.04% over the last 1 month, at the time of writing. Today’s trading volume is more than 50% of the 20-day average.

    The Ansell share price has also gained a further 2.6% over the past 5 days to hit $43.16 at the time of writing, giving the company a market capitalisation of $5.39 billion.

    On 8 June 2021, the company announced the appointment of new Chief Executive Officer Neil Salmon, to succeed outgoing CEO Magnus Nicolin, effective September 2021.

    In the announcement, Ansell chair John Bevan stated:

    Neil has the right combination of financial and operational experience and capability for the CEO role at Ansell. He has worked alongside Magnus for many years and was a key contributor to the strategies which transformed Ansell during that time. More recently, Neil also led our Industrial GBU with its over 7,500 strong manufacturing, marketing and product development workforce located in multiple jurisdictions. His leadership was critical in the management of the initial challenges of the pandemic, positioning the business where it could maximise benefits from the recovery as it emerged.

    Investors continue to reward Ansell shares, with the company’s share price gaining 10.5% since this event at the time of writing.

    Healius share price snapshot

    The Healius share price set a new 52-week high of $4.65 in today’s session, capping off a year-to-date gain of 20.16% at the time of writing.

    Trading volume is more than triple of the 20 day average for this time of day. The 52-week range for Healius share price is $2.98–$4.65.

    The Australian healthcare company specialises in pathology, imaging and medical facilities. Its shares have gained 9.64% over the previous month and 4.9% in the previous 5 days, giving the company a market capitalisation of $2.8 billion.

    Healius has seen its share price increase by 15.86% since May, where it presented a positive trading performance to the Macquarie Australia trading conference.

    Foolish Takeaway

    These 2 ASX shares have each set new 52-week highs after gaining more than 20% each this year, and have both outpaced the ASX 200’s return this year to date.

    The post 2 ASX shares hitting record highs this week appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Ansell Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/35WanNT
  • Why Twitter stock was up 12% last week

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    woman looking at social media on her phone

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    What happened

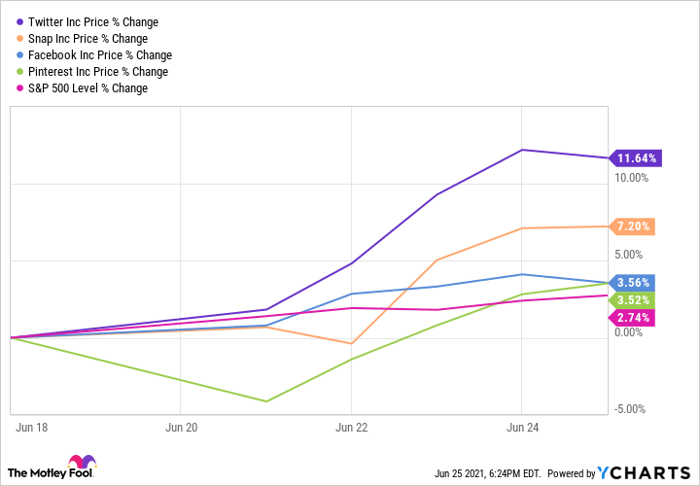
    Shares of Twitter (NYSE: TWTR) climbed 11.6% the week of June 21, leading the way among social media stocks over the same period. Snap Inc. was the only other social media stock to gain more than 5% over the same period, though the rest of the crowd had a better week than the S&P 500.

    TWTR Chart

    TWTR data by YCharts

    The week’s gains for Twitter were mostly tied to positive news about its efforts to increase monetization, both for its top users and for the company itself.

    So what

    For some time, speculation has been rampant that Twitter was planning to roll out a number of features that would — at long last — help it monetize its treasure trove of users to make money. And we’ve seen several of those start coming to fruition recently, including Twitter Spaces, and more recently, “Twitter Blue,” a subscription service it has rolled out in several international markets already, that adds some additional features for users willing to pay up.

    But the next group is now on the horizon, and it has investors feeling more bullish: Super Follows and Ticketed Spaces. In short, Twitter bulls have high hopes that adding features that Twitter users will pay for and allowing for paid events on Twitter Spaces, will unlock more of the economic value of Twitter’s users since the company will take a cut of what its users charge for Ticketed Spaces and Super Follows.

    Now what

    The plans for these two new offerings have been in the works for many months and should come as no surprise to anyone who’s followed Twitter. But the fact is, they’re finally about to come into the real world and start helping generate revenue for the company. With Twitter’s shares trading for about 14 times sales and less than 49 times operating cash flow, only Facebook has a lower valuation among social media peers.

    If these new cash-generating offerings are even moderately successful, Twitter could prove to be a bargain at these prices. All that’s left is the hardest part: Releasing them into the wild and finding out if they’re a money-making success or just another disappointing attempt that doesn’t pan out.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Why Twitter stock was up 12% last week appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Jason Hall has no position in any of the stocks mentioned. Randi Zuckerberg, a former director of market development and spokeswoman for Facebook and sister to its CEO, Mark Zuckerberg, is a member of The Motley Fool’s board of directors. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Facebook and Twitter. The Motley Fool Australia has recommended Facebook. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/35YGpIZ

  • Genworth (ASX:GMA) share price dives 17% after CBA contract update

    falling asx share price represented by child looking shocked at computer screen

    Shares in Genworth Mortgage Insurance Australia Ltd (ASX: GMA) plummeted 17% to 8-month lows in early trade this morning.

    At the time of writing, the lenders mortgage insurance provider’s share price is down 15.16%, trading at $2.15.

    Let’s take a look at what may be impacting the Genworth share price today.

    What did Genworth announce?

    In today’s statement, Genworth said the Commonwealth Bank of Australia (ASX: CBA) advised that it intended to issue a request for proposal “relating to its Lenders Mortgage Insurance (LMI) requirements” after the current exclusivity agreement with Genworth expires on 31 December 2022.

    Genworth has a range of lender customers across Australia including major and regional banks, building societies, credit unions and non-bank mortgage originators. The company said it had provided CBA with its LMI services for more than 50 years, including an exclusive arrangement since 2006.

    Genworth added that its CBA LMI contract represented approximately 57 per cent of the company’s FY20 gross written premiums.

    Management commentary

    Genworth CEO and managing director Pauline Blight-Johnston said:

    We welcome the opportunity to submit a proposal to CBA to extend our agreement for the supply of LMI beyond 2022, building on the strong foundations of our long-standing relationship.

    A core part of our strategy is to work with our lender customers to continue to improve the efficiency and competitiveness of LMI as we look to reimagine LMI for a new generation of home buyers.

    Genworth share price in 2021

    Despite having a strong exposure to Australia’s red hot property market through its LMI products, the Genworth share price has struggled to outperform the broader market.

    Genworth shares have now tumbled ~12% year-to-date and are down almost 25% in June. This compares to the S&P/ASX 200 Index (ASX: XJO), which has run about ~9.3%.

    The post Genworth (ASX:GMA) share price dives 17% after CBA contract update appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Genworth right now?

    Before you consider Genworth, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Genworth wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3jrOldE

  • Why the Neometals (ASX:NMT) share price is moving higher

    happy mining worker in foreground of earthmoving equipment

    The Neometals Ltd (ASX: NMT) share price is gaining in morning trade, up 2.2% to 47 cents per share.

    Below we look at the latest resource update from the ASX mineral explorer

    What update did Neometals report?

    Neometals’ share price is gaining after the company announced a major Mineral Resource upgrade for several of its nickel deposits.

    The updated Mineral Resource estimates for its McEwen and McEwen Hangingwall deposits come in at a grade of 1.4% nickel, totalling 41,500 tonnes of contained nickel. That’s a 45% increase from the previous estimates of 29,220 tonnes.

    These deposits represent 2 of 11 total Mineral Resources at the Neometals’ Mt Edwards Project in Western Australia. All are located in an area rich with historic nickel sulphide mines near the town of Widgiemooltha.

    The Global Mineral Resource at the Mt Edwards Project has been revised upwards to 9.64 million tonnes at 1.7% nickel for a total of 160,000 tonnes of contained nickel.

    Freshly researched historical data also led the company to downgrade its Zabel Mineral Resource, which was last estimated in December 2020. According to the release, the revised estimate “now only includes nickel sulphide in fresh rock”. The Zabel Mineral Resource was reduced by 7%, with 325,000 tonnes at 2% nickel for a total of 6,360 tonnes of contained nickel.

    Neometals said it plans additional exploration at both McEwen and McEwen Hangingwall, with bot reverse circulation and diamond drilling to increase its knowledge of the extents of mineralisation.

    Neometals share price snapshot

    Neometals shares have gained an impressive 236% over the past 12 months, compared to a gain of 27% on the All Ordinaries Index (ASX: XAO).

    Year-to-date the Neometals share price has continued to outperform, up 62% so far in 2021.

    Neometals has a market cap of $251 million.

    The post Why the Neometals (ASX:NMT) share price is moving higher appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Neometals right now?

    Before you consider Neometals, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Neometals wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3w44Yib

  • Collins Foods (ASX:CKF) share price hits record high after reporting strong FY 2022 growth

    jump in asx share price represented by man jumping in the air in celebration

    The Collins Foods Ltd (ASX: CKF) share price is pushing higher on Tuesday morning following the release of its full year results.

    At the time of writing, the KFC-focused quick service restaurant operator’s shares are up 4% to a record high of $13.25.

    How did Collins Foods perform in FY 2021?

    For the 12 months ended 2 May, Collins Foods reported a 12.4% increase in revenue to $1.07 billion. This was driven largely by its KFC Australia business, which reported a 13.8% increase in revenue to $900.4 million thanks to new store openings and same store sales growth of 12.9%.

    This was supported by a 57.4% increase in Taco Bell revenue to $28 million, which offset a 0.6% same store sales decline from the KFC Europe business.

    In respect to earnings, Collins Foods reported underlying earnings before interest, tax, depreciation and amortisation (EBITDA) from continuing operations (pre AASB 16) of $136.3 million, which was up 12.4% on the prior corresponding period.

    On the bottom line, underlying net profit after tax from continuing operations was up 18.2% to $56.9 million.

    This strong form allowed the company to declare a fully franked final dividend of 12.5 cents per share, bringing its total dividend to a fully franked 23 cents per share. This represents a 15% increase on FY 2020’s dividend.

    Management commentary

    Collins Foods’ CEO, Drew O’Malley, said: “Collins Foods successfully navigated the unprecedented challenges of COVID-19 to deliver another year of strong earnings growth in FY21. Our focus on people and operations was critical to this result, as our teams did an exceptional job of keeping our restaurants operating at a world-class level, often without the benefit of dine-in sales channels.”

    “KFC Australia was the standout performer with same store sales growing at a record rate of 12.9% and Underlying (pre AASB 16) EBITDA margins reaching 17.9%. As consumers turned to trusted brands and sought convenience, we responded with powerful brand marketing, combined with exciting initiatives in digital and an expansion of our delivery network. Digital and delivery continue to be pillars of our growth strategy for the KFC brand,” he added.

    And while things were not as positive in Europe, management remains positive on its prospects in the potentially lucrative market.

    Mr O’Malley explained: “KFC Europe had a more challenging operating environment with margins impacted by ongoing lockdowns and dining restrictions, in place for most of the year. Nonetheless, we were able to leverage weakness in the market to advance our strategic interests there, recently executing a more favourable Development Agreement and increasing our footprint in the Netherlands with the acquisition of a (net) eight new restaurants. Both of these moves will position the European business unit for a favourable recovery.”

    Outlook

    No guidance was provided for the year ahead. However, management spoke positively about the future both at home and overseas.

    Mr O’Malley said: “With continuing strong cash generation and a healthy balance sheet, Collins Foods is well positioned to continue to pursue strategic organic and acquisition growth opportunities across the Group in the year ahead.”

    In Australia, the company has signed an agreement to build a minimum of 66 new KFC restaurants by 2028. Whereas in Europe it has been incentivised to drive growth and expects up to four new builds per year in the Netherlands going forward. Collins Foods is also monitoring the landscape for opportunities to increase openings in Germany following improvements in business performance.

    Finally, Taco Bell is on track for accelerated development in FY 2022. This will be supported by ongoing consumer demand for Mexican food in Australia, and a refined marketing approach. It is looking at 9 to 12 new restaurants being opened in the year ahead.

    The CEO concluded: “Our team remains aligned on delivering on our core mission of Restaurants Done Better. Our continued emphasis on operational execution, people development, and excellence in store development will underpin our pursuit of sustainable growth in FY22 and beyond.”

    The post Collins Foods (ASX:CKF) share price hits record high after reporting strong FY 2022 growth appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Collins Foods right now?

    Before you consider Collins Foods, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Collins Foods wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro owns shares of Collins Foods Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended Collins Foods Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3A2E6CB

  • BHP (ASX:BHP) announces first deal in thermal coal selloff

    Commodities premium ASX shares Female miner and male miner stand in open mine pit surveying the area

    BHP Group Ltd (ASX: BHP) shares finished yesterday 1.04% in the green, after announcing the first step in its thermal coal selloff. This morning, however, the BHP share price has given back yesterday’s gains and is currently trading down 1.36% at $47.74 per share.

    Let’s take a closer look at the mining giant’s recent news.

    BHP offloads stake in coal project

    Yesterday afternoon, BHP announced the divestiture of its 33.3% stake in the Carrejon coal project

    Carrejon is a non-operated energy coal joint venture in Colombia. In addition to BHP, Anglo American and Glencore each held a 33.3% position in Carrejon prior to this transaction. The transaction will occur on a $387 million cash sale to Glencore PLC.

    BHP has previously stated it intends to divest its thermal-coal operations by the end of 2022.

    The sale is anticipated for full closure by December 2021, and the purchase price may include an adjustment for dividends paid to BHP by Carrejon from when signing to the deal’s completion.

    Glencore acquired Anglo American’s position on similar terms, in addition to BHP’s interests, for a total consideration of ~USD$588 million.

    Further, an additional post-taxation impairment charge of $80 million will be recognised by BHP in the second half of FY21 related to the sale.

    Analysts at investment bank Jeffries state the sale is a “win-win-win deal” for all parties involved.

    “Glencore triples down in Columbia but will run the asset for cash until depletion,” it said in a note to investors on Monday.

    Although BHP shares finished in the green, the share price fell around 5% intraday on announcement of the divestiture at about 2pm, and fell again towards the end of yesterday’s session.

    The entire transaction is expected to settle sometime in FY22.

    BHP share price snapshot

    At the time of writing, the BHP share price is down 0.87% across the past month, but has returned more than 12% over the year to date.

    With a share price of $47.74, BHP has a market capitalisation of around $140 billion, and trades at a price-to-earning ratio (P/E) of 24.97.

    The post BHP (ASX:BHP) announces first deal in thermal coal selloff appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3y1SOI7

  • CSL (ASX:CSL) share price up as AstraZeneca advice shifts

    Woman getting vaccination

    The CSL Limited (ASX: CSL) share price is gaining today. This comes amid conflicting news from the Federal Government regarding the AstraZeneca plc (LSE: AZN) COVID-19 vaccine.

    At the time of writing, the CSL share price is $289.62 – 0.42% higher than yesterday’s close.

    The AstraZeneca vaccine has been a crown jewel for the biotech company since September, when it announced it was to manufacture the vaccine in Melbourne. The CSL share price has often reacted to news of the vaccine’s use in Australia.

    Despite numerous changes to Australia’s use of the AstraZeneca vaccine, CSL is determined to keep manufacturing it in Australia.

    Late last night, Prime Minister Scott Morrison announced adults of any age can now request the AstraZeneca vaccine from their general practitioner.

    This follows last week’s news that the Federal Government plans to phase out the AstraZeneca vaccine in coming months.

    Let’s take a look at the latest news from CSL and of AstraZeneca’s position in the vaccine rollout.

    AstraZeneca and the vaccine rollout

    In the latest news of the use of the AstraZeneca vaccine in Australia, the Federal Government is implementing a new no fault indemnity scheme for doctors giving COVID-19 vaccines.

    This means all Australians able to be vaccinated can request to get the AstraZeneca jab through their general practitioner.

    Previously, Australians aged over 60 were the only cohort able to receive the AstraZeneca shot due to its side effects, which include a one-in-200,000 chance of potentially deadly blood clots.

    Word from the Prime Minister of flexibility in the age restrictions comes only days after the Federal Government released its vaccine distribution projections. Originally given to states and territories, the projections outlined the government’s plans to phase out the AstraZeneca vaccine.

    That document stated that from October, states and physicians wanting additional AstraZeneca vaccines will have to specifically request their availability.

    In comments published by The Australian, CSL declared it won’t stop manufacturing the embattled vaccine. It stated it may instead ship those produced in Melbourne overseas, as demand from other countries is thriving.

    Chris Larkins, senior vice president of operations for CSL’s vaccine producer Seqirus, was quoted by the publication as saying:

    [The previous decision to restrict who can receive the AstraZeneca vaccine] is very much an Australian decision, based on what’s happening in Australia and the lack of any sort of real transmission of Covid, we’ve had governments calling us up from around the world saying ‘we’ll take it’.

    Today may be an interesting day for the CSL share price. Major news of Australia’s use of the AstraZeneca vaccine often inspires excitement from the market.

    CSL share price snapshot

    The CSL share price needs all the good news it can get after battling a tough 2021 on the ASX.

    Currently, shares in CSL have gained just 1.5% year to date. However, the CSL share price has fallen 0.1% since this time last year.

    The company has a market capitalisation of around $131 billion, with approximately 455 million shares outstanding.

    The post CSL (ASX:CSL) share price up as AstraZeneca advice shifts appeared first on The Motley Fool Australia.

    Should you invest $1,000 in CSL Limited right now?

    Before you consider CSL Limited, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and CSL Limited wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended CSL Ltd. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3AcwHki

  • Investors push Australia’s largest ASX shares to disclose climate risks

    Trees and a road shapes a dollar sign of green, indicating the share price movement of ASX eco companies

    Investors are pushing Australia’s largest ASX-listed shares to disclose climate risks as investment firms are warned of reduced capital.

    The push follows what has been described as a ‘coming of age’ for environmental, social, and governance (ESG) investing.

    Heating up for ASX shares

    Australia’s largest ASX shares may soon be forced to disclose climate risks by the Investor Group on Climate Change (IGCC), Principles for Responsible Investment, and Carbon Disclosure Project. Conjointly, the groups represent more than $2 trillion in assets.

    Members of IGCC include the Westpac Banking Corp‘s (ASX: WBC) BT management, and Commonwealth Bank of Australia‘s (ASX: CBA) Colonial.

    The groups have launched a plan that would begin with S&P/ASX 300 Index (ASX: XKO) companies. Initially, the plan would be voluntary under an “if not, why not” approach. However, by 2024 the IGCC wants a mandatory system.

    According to IGCC’s release, the scheme is a bid to improve the current Task Force on Climate-related Financial Disclosures (TCFD).

    Currently, 60 of the top 200 ASX shares are already providing climate-related financial disclosures. Although, a lack of a standardised approach continues to introduce inconsistencies.

    In its statement, IGCC said:

    Institutional investors have reported that the quality and consistency of these company disclosures is severely lacking, leading to the underpricing of climate risks in the market.

    With other major jurisdictions already shifted to mandatory systems, IGCC worries Australian companies and investors could be left beholden to multiple regulatory frameworks. This outcome would likely be detrimental to Australian investors and companies.

    Climate mispricing

    ASX-listed shares could face extensive climate costs in the future. The issue for fund managers and retail investors is trying to evaluate this on a company-by-company basis.

    The cost of climate change to a company may include carbon pricing changes, extreme weather events, or transitory costs. Unfortunately for investors, the quality of this risk assessment differs greatly between companies.

    Commenting on this, IGCC policy director Erwin Jackson said:

    Companies who disclose will get better access to capital. If an investor looks into a company and they’re just doing tick box exercises, the investor will say you don’t understand this and you’re not prepared. If they see a company doing good disclosure, leaning towards solutions, they say this is a good company to invest in.

    Lastly, the plan stipulates that consultation over implementing measures will be held between 2022 and 2023. Following that, legislative measures could be put in place with full compliance required by 2024 to 2025.

    The post Investors push Australia’s largest ASX shares to disclose climate risks appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Mitchell Lawler owns shares of Commonwealth Bank of Australia. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3h0ue4z

  • Why the Smartgroup (ASX:SIQ) share price is edging higher today

    share price up

    The Smartgroup Corporation Ltd (ASX: SIQ) share price is edging higher in early morning trade. This follows an announcement from the salary packaging and novated leasing company that it has renewed a significant contract.

    At the time of writing, Smartgroup shares are fetching for $7.24 apiece, up 0.42%.

    Smartgroup extends partnership

    Investors took the time to digest the company’s release overnight which have pushed its shares slightly higher.

    In yesterday’s after market statement, Smartgroup advised it has been successful in securing a contract renewal from the Department of Defence. The continued partnership will see the company provide salary packaging and novated leasing services until June 2026.

    The latest win comes after Smartgroup entered into a competitive tender process against other salary packaging and fleeting management companies.

    It’s worth noting, the Department of Defence is Smartgroup’s largest single client since first winning the contract in 1999.

    Smartgroup CEO, Tim Looi commented on the positive news, saying:

    We are delighted that Smartgroup will be able to continue its long-term relationship with Department of Defence. We have strong client relationships across our diversified client base and continue to focus on customer experience as a key driver of those relationships.

    In 2020, we renewed or extended all eight top 20 contracts that fell due and we have now renewed or extended the bulk of the top 20 contracts that fell due in 2021.

    About the Smartgroup share price

    In the last 12 months, Smartgroup shares have risen from the $6 mark to $7.21 as of yesterday’s closing price. This roughly represents an increase of 20% for shareholders. The company’s shares reached a 52-week high of $7.85 in early February ahead of its full-year results. However, once the financial report was released to the ASX, Smartgroup shares tanked to $5.95.

    Based on valuation grounds, Smartgroup commands a market capitalisation of about $962 million, with approximately 133 million shares on issue.

    The post Why the Smartgroup (ASX:SIQ) share price is edging higher today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Smartgroup right now?

    Before you consider Smartgroup, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Smartgroup wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended SMARTGROUP DEF SET. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3hhAy6U

  • Why the BARD1 (ASX:BD1) share price is surging 10% higher

    healthcare asx share price rise represented by happy doctor

    The BARD1 Life Sciences Ltd (ASX: BD1) share price has been a strong performer on Tuesday morning.

    In early trade, the diagnostics company’s shares are up 10% to $2.14.

    This means the BARD1 share price is now up over 200% since the start of the year.

    Why is the BARD1 share price racing higher?

    Investors have been bidding the BARD1 share price higher today following the release of an announcement relating to its BARD1 autoantibody test for the early detection of ovarian cancer.

    According to the release, the previously reported study results have been published in the international peer-reviewed journal Genes. This appears to have brought the company onto the radar of a wider group of investors, boosting the BARD1 share price.

    The study data published in Genes shows positive results from BARD1’s OC-CA125 and OC-R001 studies in ovarian cancer. These studies were performed at the University of Geneva (UNIGE) under a research agreement.

    What is the study?

    BARD1 is exploring several approaches for developing an accurate and reliable blood test for earlier detection of ovarian cancer utilising its proprietary BARD1 autoantibody (AAb) and SubB2M technologies.

    The BARD1 autoantibody approach in the above studies used a research-stage enzyme-linked immunosorbent assay (ELISA) performed on a research use only (Meso Scale Discover) MSD platform to detect autoantibodies to BARD1 variant proteins.

    However, whilst this has shown promising data, the company believes it requires considerable further assay development and technical validation on a commercial assay platform before advancement towards clinical development of a potential commercial test.

    What else is happening?

    In addition to this, the company advised that is developing a SubB2M-based approach that detects a pan-cancer marker called Neu5Gc. Proof of concept results using a research-stage SPR assay showed outstanding accuracy for detection of ovarian cancer, with 100% sensitivity and specificity across all stages compared to healthy controls.

    Furthermore, SubB2M-based ELISA blood tests are currently being developed for monitoring treatment response and recurrence in women previously diagnosed with ovarian cancer. And finally, BARD1 is also looking to undertake further studies to expand indications for use of a SubB2M-based ELISA to a screening test for early detection of ovarian cancer in asymptomatic women.

    Overall, a lot of promising developments, which goes some way to explaining the rapid rise in the BARD1 share price this year.

    The post Why the BARD1 (ASX:BD1) share price is surging 10% higher appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BARD1 right now?

    Before you consider BARD1, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BARD1 wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3A7xIdg