Category: Stock Market

  • Why the Pentanet (ASX:5GG) share price is sinking today

    women with a microphone is happy whilst using a computer

    The Pentanet Ltd (ASX: 5GG) share price is under pressure on Friday morning.

    At the time of writing, the growth-focused telco’s shares are down 4% to 73 cents.

    Why is the Pentanet share price dropping today?

    The weakness in the Pentanet share price on Friday comes after the company announced a successful capital raising.

    According to the release, the company has received firm commitments to raise $20 million before costs via a share placement to institutional and sophisticated investors.

    Pentanet is raising the funds at 72 cents per new share, which represents a 5.3% discount to its last close price.

    Positively, demand was very strong for the placement. In fact, the company revealed that it received demand three times in excess of what it was seeking. Furthermore, there was a strong level of institutional participation that included many notable Australian funds.

    Why is Pentanet raising funds?

    The release explains that the funds will be primarily used to accelerate the disciplined execution of the company’s Fixed Wireless and Cloud Gaming growth strategy. Central to this strategy is the deployment of Terragraph and GeForce NOW infrastructure to drive industry leading performance capability and to build a unique telecommunications and gaming platform in the Australian market.

    Management notes that market interest in GeForce NOW Powered by Pentanet (the Australian deployment of NVIDIA’s cloud gaming service) has exceeded initial expectations since its announcement in January.

    As a result, Pentanet has significantly expanded the planned pilot infrastructure rollout and put in place an upgrade capability to accelerate the network deployment where market demand continues to support this.

    Pentanet’s Managing Director, Stephen Cornish, commented: “It is good to see the strong support from investors, highlighting an increased level of understanding around the relationship between cloud gaming and 5G, now enabling us to move Pentanet into the next stage of growth early. It is a fast-developing market and we have taken advantage of market opportunities in both our Fixed Wireless and our Cloud Gaming services to strengthen our capabilities.”

    “Our team will continue to show that we are leaders in these developing services, and the highest tier when it comes to providing subscribers with industry leading internet performance and delivering on what will be Australia’s best and most anticipated high-quality Cloud Gaming service.”

    Despite today’s weakness, the Pentanet share price is up a sizeable 25% since the start of the year.

    The post Why the Pentanet (ASX:5GG) share price is sinking today appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Pentanet right now?

    Before you consider Pentanet, you’ll want to hear this.

    Motley Fool Investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Pentanet wasn’t one of them.

    The online investing service he’s run for nearly a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.* And right now, Scott thinks there are 5 stocks that are better buys.

    *Returns as of May 24th 2021

    More reading

    James Mickleboro does not own any shares mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3gCvJGd
  • Starpharma (ASX:SPL) share price jumps 7% on COVID variant update

    covid asx share price represented by man in face mask giving thumbs up

    The Starpharma Holdings Limited (ASX: SPL) share price is on course to end the week on a strong note.

    At the time of writing, the dendrimer products developer’s shares are up 7% to $1.66.

    Why is the Starpharma share price pushing higher?

    The Starpharma share price is pushing higher today after the company released another update on its COVID-fighting Viraleze antiviral nasal spray.

    According to the release, new data demonstrates that the active ingredient in the Viraleze antiviral nasal spray, SPL7013, has been shown to be highly effective against various COVID-19 strains.

    The release explains that SPL7013 achieved a more than 99.9% reduction of virus against the Alpha (UK), Beta (South Africa) and Gamma (Japan/Brazil) SARS-CoV-2 coronavirus variants of concern in laboratory-based virucidal assays. The testing of SPL7013 was conducted in the laboratory of virologist Professor Philippe Gallay at The Scripps Research Institute in the United States.

    Management advised that SPL7013 virucidal activity against the Alpha, Beta and Gamma variants in the current assays were broadly consistent with the virucidal activity demonstrated in the US strain of SARS-CoV2 in the same assay.

    It notes that within 30 seconds to 1 minute of exposure, SPL7013 achieved >99% reduction in infectious virus against Beta and Gamma variants, and >99.9% within 5 minutes. The Alpha variant was quicker, achieving a >99.9% reduction in infectious virus within 30 seconds to 1 minute of exposure.

    Starpharma’s CEO, Dr Jackie Fairley, commented: “We are very pleased to see such potent and rapid virucidal activity of Viraleze against multiple SARS-CoV-2 variants of concern, Alpha, Beta, and Gamma. These variants continue to spread across the globe and challenge efforts to control the COVID-19 pandemic.”

    “Given its broad spectrum of activity, Viraleze could prove to be particularly beneficial as an additional protective measure against these variants. This could prove particularly useful in settings where these variants can be problematic, like hotel quarantine and major international events such as the Tokyo Olympics,” she concluded.

    The post Starpharma (ASX:SPL) share price jumps 7% on COVID variant update appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    James Mickleboro does not own any shares mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Starpharma Holdings Limited. The Motley Fool Australia has recommended Starpharma Holdings Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3q6eVKF

  • Altium (ASX:ALU) share price higher on guidance update

    boy in celebration pose with pointed fingers raised high

    The Altium Limited (ASX: ALU) share price is on the move on Friday morning.

    At the time of writing, the electronic design software provider’s shares are up 3% to $35.46.

    Why is the Altium share price pushing higher?

    The catalyst for the rise in the Altium share price today has been the release of a presentation and a trading update.

    In respect to the latter, Altium’s Chief Financial Officer Martin Ive revealed that the company’s performance improved in the second half after a slow start to the year. However, due partly to a shift in its sales mix, there is a danger it could fall short of expectations in FY 2021.

    He said: “Momentum has returned to Altium’s business with double-digit growth in the second half, however, after a slow first half due to the impact of COVID and our pivot to the cloud, the full year is likely to be at, or slightly below, the low end of our guidance.”

    The guidance range Mr Ive is referring to is for revenue of US$190 million to US$195 million in FY 2021.

    In addition to this, Altium is expecting its margin to be at the low end of the guidance range of 37-39% on an underlying basis. This excludes one-off acquisition costs and the write back of the SolidWorks minimum contractual amount due to termination of its agreement.

    Mr Ive further commented: “Altium’s renewal business is strong, Octopart is set for a record performance and China is delivering a solid performance. Demand is growing for Term Based Licences (TBLs), which is a positive for future recurring revenue, however, Altium’s perpetual licence sales have underperformed relative to our expectations in the key markets of the US and EMEA as our sales organization works through its transition of our new sales model.”

    This new sales model is gathering pace, with the adoption of the Altium 365 cloud platform continuing to increase. The release advises that there are now more than 13,100 monthly active users and over 6,300 monthly active accounts.

    What about the future?

    While FY 2021 might have been a touch disappointing, management remains very positive on the company’s long term growth prospects. This appears to have supported the Altium share price today.

    It has reaffirmed its commitment to achieve Altium’s aspirational 2025 financial goals of US$500 million revenue and 100,000 subscribers. This is expected to be underpinned by the company’s unique position within the global engineering software industry and track record of strategic execution.

    In addition to this, due to the aforementioned change in its sales mix, management expects the majority of this revenue to be recurring in nature by then. It anticipates recurring revenues growing from 60% to 80% of overall revenue by 2025.

    Commenting on the future, Altium’s CEO, Aram Mirkazemi, said: “Everyone at Altium is strongly focused on delivering our strategy and driving value for our investors. Electronics sit at the heart of all intelligent systems, and Altium software and services provide the unique bridges that connect electronic design to the electronics supply chain and the manufacturing of electronics products.”

    “With the strong early adoption of our cloud platform, we are evolving from our PCB design origins and are now playing an essential and growing role in the design and making of smart products, that spans manufacturability and productivity, research and influence, and component sourcing.”

    Mr Mirkazemi appears confident in the company’s strategy and expects Altium to dominate the industry.

    He said: “With our strategy we are pursuing dominance and transformation simultaneously. This will allow us to continue to deliver value to shareholders, while driving electronics industry transformation for the benefit of our customers.”

    “The building blocks of our strategy are in place; our flagship PCB design tool Altium Designer supported our journey to market leadership and remains at the core of the Company, our new cloud platform Altium 365 will drive our ambition to unify and align the electronics industry and our ecosystem platform Nexar will bring transformation and a clear pathway to monetization.” Mirkazemi added.

    The post Altium (ASX:ALU) share price higher on guidance update appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    James Mickleboro does not own any shares mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Altium. The Motley Fool Australia owns shares of and has recommended Altium. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3zKMcj8

  • Apple is already building an augmented reality future

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

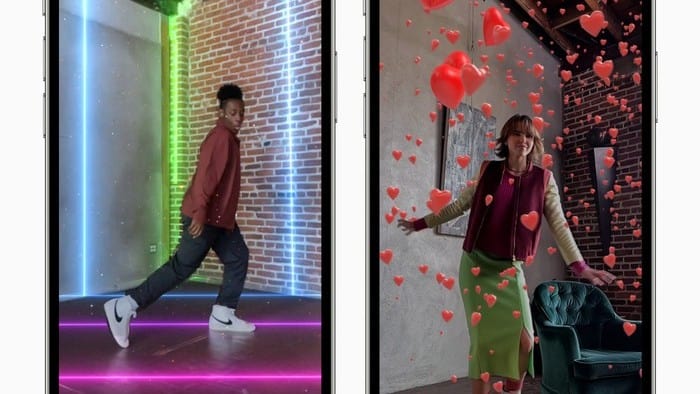
    iPhones with augmented reality features.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    For Apple (NASDAQ: AAPL), the future is about far more than our physical reality. The company is building tools for augmented reality (AR) that could be in common use by over 1 billion devices around the world, and virtual reality (VR) has been rumored to be on the way as well.

    What’s become clear in the last few quarters is that Apple is building the foundation of its AR strategy right before our eyes. Lidar included in iPhones and iPads today increases the accuracy and fidelity of AR on the devices, and Apple is already creating an ecosystem of apps and tools for developers. At its Worldwide Developers Conference last week, Apple said it is bringing AR into maps and capture tools for third-party apps in an AR strategy that could keep this tech stock growing for the next decade.

    Augmented reality is coming to maps

    The most notable AR addition announced last week was AR for maps. In a news release, Apple described its mapping AR technology by saying, “With iOS 15, users can simply hold up iPhone, and Maps generates a highly accurate position to deliver detailed walking directions in augmented reality.”

    For now, this technology will only be available on the iPhone, but it’s unlikely that’s the end game. AR glasses like Magic Leap have long envisioned maps as a high-value use for augmented reality technology. A Magic Leap app called Holomaps says you can “see 3D maps with live data, traffic, weather, and Twitter updates.” If and when Apple announces AR glasses, it could offer the same tools.

    The combination of knowing a user’s location and being able to scan the surrounding area opens up a world of possibilities, especially if users are wearing Apple AR devices. And if Apple can use the user’s scan data to improve its maps, we could see that add value not only to maps but also to new technologies like self-driving vehicles.

    Capturing AR assets just got a lot easier

    Another notable addition to iOS is Object Capture. One of the challenges with building cost-effective AR tools is capturing 3D assets, and now that can be done with just a camera. Here’s what Apple said about Object Capture and RealityKit 2, part of ARKit, in a press release:

    RealityKit 2 introduces Object Capture, a simple and powerful [Application Programming Interface] API on macOS Monterey [the codename for Apple’s latest OS] that enables developers — like Wayfair, Etsy, and more — to create high-quality, photo-realistic 3D models of real-world objects in minutes by taking photos shot on iPhone, iPad, or DSLR and transforming them into 3D models optimized for AR. These models can be viewed in AR Quick Look or added to AR scenes in [applications like] Reality Composer or Xcode, making it easier than ever to build amazing AR apps.

    If capturing assets gets easier, it’ll make it easier for developers and companies to include AR assets in their apps. And more assets mean more app possibilities for current iOS devices and next-generation devices like AR or VR glasses or headsets.

    AR is core to Apple’s future

    Apple highlighted that it has over 1 billion AR devices in the world, and the company has slowly but surely been building a foundation in AR for years. It has hardware with AR technology integrated, tools for developers to build with, and billions of users already in the ecosystem. If Apple introduces AR glasses in the next few years, as rumored, it could expand its product lineup even further and continue growth into the next generation of technology devices. Don’t sleep on the importance of AR to Apple’s future.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    The post Apple is already building an augmented reality future appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Travis Hoium owns shares of Apple. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Apple, Etsy, and Twitter. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has recommended the following options: long March 2023 $120 calls on Apple and short March 2023 $130 calls on Apple. The Motley Fool Australia has recommended Apple. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3xwcraS

  • Why the RPMGlobal (ASX:RUL) share price will be in the spotlight today

    industrial asx share price on watch represented by builder looking through magnifying glass

    The RPMGlobal Holdings Ltd (ASX: RUL) share price will be one to watch on Friday.

    This follows the release of an update in relation to the mining software company’s sales for FY 2021.

    What did RPMGlobal announce?

    RPMGlobal shares will be in focus today after the company revealed its current trading conditions have been stronger than the previous year.

    The company provided an update on total contracted value (TCV) and annual recurring revenue (ARR) for subscription software sales.

    During FY 2021, RPMGlobal has achieved $40 million in TCV software subscriptions, with $40.4 million recorded year to date. This is an increase of $9 million from when the company reported $31.4 million in TCV sales early last month.

    ARR from software subscriptions has also grown to $21.5 million, up from $20.1 million on 4 May 2021.

    What does RPMGlobal do?

    Founded in 1968, RPMGlobal provides advisory consulting, training and software for the mining and related services industries. The group operates across 3 segments, namely software, advisory, and GeoGAS.

    The software division integrates planning and scheduling with maintenance and execution, and simulation and costings for mining companies.

    Next up, the advisory division comprises consulting and advisory services, delivering expertise on technical mining papers. This provides insights into geology, engineering and environmental, social and governance factors, as well as mining logistics to resource companies.

    And finally, the GeoGAS division provides services to coal mining customers such as gas content testing and relevant consulting services.

    RPMGlobal share price summary

    Over the last 12 months, the RPMGlobal share price has accelerated by almost 60%. In 2021, the company’s shares have lifted by nearly 30%.

    Last Thursday, RPMGlobal shares hit a milestone all-time high of $1.735. It’s worth noting that at the current price of $1.66 before market open, they could break a new record today if investors respond positively to the company’s latest update.

    RPMGlobal has a market capitalisation of roughly $380 million, with approximately 229 million shares on its registry.

    The post Why the RPMGlobal (ASX:RUL) share price will be in the spotlight today appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended RPMGlobal Holdings. The Motley Fool Australia has recommended RPMGlobal Holdings. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3zzHtAu

  • Here’s why the Immutep (ASX:IMM) share price is frozen

    a doctor looking up at question marks

    For the second day in a row, the Immutep Ltd (ASX: IMM) share price will be frozen at market open.

    Yesterday, Immutep entered a trading halt until Monday’s open, or until such time as the company releases further news regarding a capital raise, whichever comes first.

    When Immutep shares closed on Wednesday ­– their latest active session ­– they were swapping hands for 62 cents apiece.

    Let’s take a look at what we know so far of the biotechnology company’s capital raise.

    New capital raise

    According to Immutep, the capital raise will be an institutional placement. However, the company has not yet stated how much it hopes to raise during the activity.

    Additionally, Immutep hasn’t yet disclosed why it will be conducting the capital raise.

    Market watchers will be keeping an eye on the company today, as further details of its latest placement are likely to be announced before Monday’s open.

    The last institutional placement completed by Immutep took place in August 2020. Through that placement, the company raised $29.6 million by issuing 123.3 million new shares at 24 cents per share to institutional investors.

    Immutep’s previous capital raise was used to boost its clinical programs budget.

    It mostly went towards the ongoing development of the company’s IMP123 – a drug that regulates the immune system. However, a portion of the capital raised went towards Immutep’s immunosuppressive agonist drug IMP761, which is still in preclinical stages.

    Immutep share price snapshot

    2021 has been a good year on the ASX so far for Immutep shares.

    The Immutep share price is currently 48% higher than it was at the start of this year. It has also gained 305% since this time last year.

    The company has a market capitalisation of around $444 million, with approximately 648 million shares outstanding.

    The post Here’s why the Immutep (ASX:IMM) share price is frozen appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3xAr1yp

  • The Trajan (ASX:TRJ) share price is up 38% in under two weeks

    asx share price surge represented by hand holding rocket taking off

    The Trajan Group Holdings (ASX: TRJ) share price has been a strong performer since its IPO earlier this month.

    Since hitting the ASX boards on 7 June, the shares of the global developer and manufacturer of analytical science instruments, devices and solutions are up an impressive 38% from their listing price.

    Based on the current Trajan share price, the company now has a market capitalisation of just over $300 million.

    What is Trajan?

    Trajan was established in 2011 and is a global participant in the analytical science instrument and device industry.

    According to its prospectus, it is a purpose led business that aims to enrich human wellbeing through the design, manufacture and supply of products and solutions that enhance scientific measurement.

    Trajan’s precision componentry and solutions are used in the analysis of biological, food, and environmental samples across a variety of segments that impact human wellbeing. They also have a broad range of life science applications including pharmaceutical, clinical diagnostics, and pathology.

    In addition to this, the company has developed a portfolio of innovative technologies and devices which are expected to support the trend towards decentralised, personalised data‑based healthcare.

    Why is the Trajan share price shooting higher?

    One of the reasons investors have been bidding the Trajan share price higher might be its sizeable and growing market opportunity.

    One segment of the global analytical science industry in which Trajan operates is the mass spectrometry market, which was valued at US$4.1 billion in 2020.

    End‑user segments within this market include pharmaceutical applications which are projected to grow at a CAGR of 9.3% and environmental testing which is projected to have a CAGR of 6.5% from 2020 to 2025.

    For now, it is forecasting revenue of $74.65 million and EBITDA of $9.5 million in FY 2021 and then revenue of $82.5 million and EBITDA of $10.7 million in FY 2022.

    Trajan IPO

    Trajan raised gross proceeds of $90 million at an offer price of $1.70 per share from its IPO.

    Management notes that the proceeds raised will predominantly be used to execute the company’s growth strategy. This strategy encompasses both strategic acquisitions of complementary businesses, technologies and processes, and continued investment in its proprietary technology and device portfolio.

    Some of the proceeds were also used to give existing shareholders the opportunity to realise a minority part of their investment in the company.

    Given its bright prospects and high quality technology, it might be worth keeping an eye on the Trajan share price in 2021.

    The post The Trajan (ASX:TRJ) share price is up 38% in under two weeks appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    James Mickleboro does not own any shares mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3q4UzS0

  • 3 excellent ETFs for ASX investors

    ETF spelt out

    If you’re looking for an easy way to invest in international shares for diversification, then exchange traded funds (ETFs) could be the answer.

    But which ETFs should you look at? Here are three excellent ETFs that could be worth getting better acquainted with:

    BetaShares NASDAQ 100 ETF (ASX: NDQ)

    The first ETF to look at is the hugely popular BetaShares NASDAQ 100 ETF. This fund gives investors exposure to the 100 largest non-financial shares on the famous NASDAQ index. Among the 100 companies included in the fund are household names such as Amazon, Apple, Facebook, and Microsoft. And while the fund does have a high weighting to the tech sector, there are also a number of outstanding non-tech companies included in it as well. These include Mondelez, Moderna, Pepsico, Starbucks, and Tesla.

    The BetaShares NASDAQ 100 ETF has generated a return of 23.6% per annum over the last five years.

    BetaShares Global Cybersecurity ETF (ASX: HACK)

    Another ASX ETF to look at is the BetaShares Global Cybersecurity ETF. As it names indicates, this ETF gives investors exposure to the leading companies in the global cybersecurity sector. This could be a great place to be right now, with demand for cybersecurity services increasing due to the growing threat of cyber attacks. Included in the fund are quality companies such as Accenture, Cisco, Cloudflare, Crowdstrike, Okta, and Splunk.

    Over the last five years, the index the BetaShares Global Cybersecurity ETF tracks has delivered a return of 20.1% per annum.

    VanEck Vectors Video Gaming and eSports ETF (ASX: ESPO)

    A final ETF for ASX investors to look at is the VanEck Vectors Video Gaming and eSports ETF. It gives investors access to a portfolio of the largest companies involved in video game development, hardware, and esports. This means you’ll be buying a slice of companies such as Nvidia, Take-Two, and Electronic Arts. These companies are well-placed to benefit from the increasing popularity of video games and eSports.

    The index the VanEck Vectors Video Gaming and eSports ETF tracks has generated an average return of 33.6% per annum over the last five years.

    The post 3 excellent ETFs for ASX investors appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended BETA CYBER ETF UNITS and BETANASDAQ ETF UNITS. The Motley Fool Australia owns shares of and has recommended BETA CYBER ETF UNITS and BETANASDAQ ETF UNITS. The Motley Fool Australia has recommended VanEck Vectors ETF Trust – VanEck Vectors Video Gaming and eSports ETF. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/35y97Ak

  • Here are the best performing ASX 200 shares so far in 2021

    Three ASX 200 share holders climbing ladders up into the clouds

    Leading up to the midpoint of 2021, it might be time to take stock and see how your investments stack up against the best performing shares in the S&P/ASX 200 Index (ASX: XJO) so far this year.

    While the arbitrary timeframe of performance holds little weight in the long term, it can be helpful to understand what a winning investment looks like. Whether it’s macro trends, business decisions, or speculation – there’s usually a reason behind strong performance.

    So, let’s make like a rock and get rolling…

    Top 5 ASX 200 shares, you might be surprised

    We covered 2021’s top performers out of all the ASX-listed shares on Wednesday. But today is solely for those that are included in the benchmark index.

    And here they are…

    ARB Corporation Limited (ASX: ARB)

    The Australia-based 4×4 accessories manufacturer has shot the lights out so far this year. This ASX 200 share has gained 48% year to date (YTD). Making its performance all the more impressive, this is on the back of a 64% gain in 2020.

    The company has benefitted from a massive boom in vehicle sales, as savings and the desire to travel locally surged. For the half year ended December 2020, ARB reported revenue of $283.9 million, representing an increase of 21.6% on the prior corresponding period.

    Other share price catalysts included the company’s acquisition of Truckman – a utility accessories manufacturer in the United Kingdom, and a strategic collaboration with Ford Motor Company for its new Ford Bronco.

    Reece Ltd (ASX: REH)

    Ultra-low interest rates, a rebounding economy, and money to spend – a recipe for a thriving property market. Whether it’s building brand new, or updating the bathroom, Reece has captured plenty of the property tailwinds. Reece is Australia’s largest supplier of all things bathroom, kitchen, plumbing and HVAC.

    The company reported a 4% increase in revenue for the half-year. Meanwhile, earnings before interest, tax, depreciation, and amortisation (EBITDA) jumped 12% to $349 million. With the property trend continuing into 2021, investors have been buying up this ASX 200 share in their droves.

    The Reece share price has gained almost 50% YTD.

    Pilbara Minerals Ltd (ASX: PLS)

    Lithium prices have flown higher this year, with carbonate and hydroxide pushing more than 50% off November 2020 lows. The upwards move in the electrifying commodity has boosted revenues and earnings margins for lithium mining companies, such as Pilbara Minerals.

    As of December 2020, the company’s trailing 12-month revenue was $105.5 million, an increase of 59.4% from December 2019. Additionally, the company’s strategy and outlook announcement on 11 May showed plans to further increase production.

    The Pilbara Minerals share price has surged 53% so far this year. Despite the jump in its share price, the company is still one of the smaller shares in the ASX 200 index with a market capitalisation of around $3.85 billion.

    Pro Medicus Limited (ASX: PME)

    Pro Medicus is a provider of healthcare imaging software, ranging across medical accounting, clinical reporting, appointment scheduling and more. The company runs on a software-as-a-service (SaaS) model, making it important for it to land new contracts.

    So far in 2021, Pro Medicus has landed a few big contracts, instilling investor optimism. In January, the company signed a 7-year contract with Intermountain Healthcare for $40 million.

    Then in February, another 7-year contract – this time with a major University Health System for $31 million. Lastly, an 8-year contract worth $14 million was signed with the University of Vermont Health Network in May.

    The flurry of new customers has been met with a 58% share price increase YTD.

    Codan Limited (ASX: CDA)

    Finally, taking out the spot for best performing ASX 200 share so far in 2021 with a gain of almost 66% YTD is… Codan. A manufacturer of metal detectors, communications, and tracking solutions, Codan has enjoyed record sales – driven predominantly by metal detector and tracking solution sales.

    Furthermore, the company has made two acquisitions already this year, the first being Domo Tactical Communications. Domo is a provider of high-bandwidth wireless communications to more than 20 key United States Government agencies.

    The second acquisition involved Zetron Inc, a provider of mission-critical communication technologies. Codan anticipates that the acquired business will contribute roughly $67 million in sales during the next financial year.

    The post Here are the best performing ASX 200 shares so far in 2021 appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Motley Fool contributor Mitchell Lawler owns shares of Pro Medicus Ltd. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and has recommended Pro Medicus Ltd. The Motley Fool Australia owns shares of and has recommended Pro Medicus Ltd. The Motley Fool Australia has recommended ARB Corporation Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3wBnxv7

  • Revealed: 5 sectors with worst gender pay gap

    a man and a woman at work facing off

    The Australian industries with the biggest gender pay gaps have been revealed, and it’s not pretty for investment market participants.

    Analysis firm IBISWorld’s study released Thursday showed that, across all industries and jobs, full-time female workers in Australia earned 13.4% less than a male colleague in the same position.

    “A driving factor of the gender pay gap is unequal representation of women in leadership positions and inflexible working arrangements that do not accommodate for the responsibility of unpaid caring and domestic work,” said IBISWorld senior industry analyst Victoria Baikie.

    The gaps in the 5 worst performing sectors are damning, with 3 of the sectors involved in investment markets.

    Financial brokerage came ‘first’ with a 48.9% pay discrepancy, and the money market dealer industry was the third-worst with 41.3%.

    Aviation, which has companies like Qantas Airways Limited (ASX: QAN) and Air New Zealand Limited (ASX: AIZ) on the ASX, rounded out the worst 5 with a 38.2% wage gap.

    The other two sectors with massive gaps were sport and recreation clubs (47.6%) and real estate services (39.8%).

    Why do these sectors pay women so poorly?

    The gender gap in the finance industry was caused by a lack of female representation in higher positions. The study found that last year just 18% of managers were women.

    While the industry is trying hard to address the gap, this critical element is yet to be resolved.

    “Strategies to address the gap have become more common, such as gender parity graduate programs that support women’s entry. However, a higher proportion of males were promoted to more senior roles than women in 2020, hindering improvement in the gender pay gap.”

    But Baikie had hope that this problem would be rectified. 

    “Firms within the financial asset broking services subdivision are increasingly likely to focus on the retention and promotion of women into leadership positions — especially CEO positions — in order to address the gender pay gap.”

    As for the money market, the domination of the big four banks in Australia seems to be a significant hurdle.

    “None of the 4 largest banks has equal gender representation in their executive leadership team and on their board of directors,” said Baikie.

    Macquarie Group Ltd (ASX: MQG) does have a female chief executive and equal gender split on its board, but it only represents 5% of the sector revenue.

    In aviation, the massive disparity in wages among pilots is letting down the entire industry.

    Just 9% of pilots in Australia are female, earning $942.30 less than men per week.

    The upheaval caused by the COVID-19 pandemic would only exacerbate the situation, according to IBISWorld.

    “Airlines will likely bring back their most senior pilots first as flight numbers increase, limiting opportunities for newly trained female pilots,” said Baikie.

    “The gender pay gap for the air transport subdivision will likely get worse before it gets better.”

    The post Revealed: 5 sectors with worst gender pay gap appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the five best ASX stocks for investors to buy right now. These stocks are trading at near dirt-cheap prices and Scott thinks they could be great buys right now.

    *Returns as of May 24th 2021

    More reading

    Tony Yoo owns shares of Macquarie Group Limited and Qantas. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Macquarie Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    from The Motley Fool Australia https://ift.tt/3wxtTf8