Category: Stock Market

  • Is the Commonwealth Bank (ASX:CBA) share price a buy at $90?

    investor staring off as if wondering about asx share price

    The Commonwealth Bank of Australia (ASX: CBA) share price has been making investors very happy over the past 12 months. The ASX’s largest bank has grown more than 52% in value over the past year, including a healthy 7% in 2021 so far.

    On Friday, CBA broke its 52-week high and closed at its highest level since February 2020 when the bank hit its pre-COVID all-time high.

    Today, CBA has climbed even higher, making a fresh new 52-week high of $89.99 this morning. While that share price is laughably tantalising for being so close to $90, let’s take a look at what this ASX bank has to offer at ~$90 a share today.

    What does Commonwealth Bank offer today?

    So, at the current share price, CBA is trading with a market capitalisation of $159.2 billion, a price-to-earnings (P/E) ratio of 19.96 and a trailing dividend yield of 2.76%.

    At this market capitalisation, CBA is now back atop its sometimes-occupied throne of the most valuable company on the S&P/ASX 200 Index (ASX: XJO). Yes, CBA is now the biggest public company in Australia, a position it has regularly shared with BHP Group Ltd (ASX: BHP) and CSL Limited (ASX: CSL) over the past few years.

    So at a P/E ratio of 19.96, CBA is still below the current average for an ASX 200 company, which is 23.65. However, it is also below the average P/E of other big ASX banks today. To illustrate, let’s take a look at CBA’s big four brethren.

    Westpac Banking Corp (ASX: WBC) shares are currently trading on a sky-high P/E ratio of 39.63. But National Australia Bank Ltd (ASX: NAB) and Australia and New Zealand Banking Group Ltd (ASX: ANZ) currently have P/Es of 24.67 and 23.79 respectively.

    Turning to dividend yields, and CBA is once again looking competitive. A trailing yield of 2.76% far outstrips ANZ’s current trailing yield of 2.08% on current pricing. Ditto with NAB’s 2.24%. And Westpac is currently offering investors just 1.23%.

    However, it’s worth noting that the dividends we will see over the rest of 2021 are likely to look a lot different to what we have seen over 2020.

    So CBA looks objectively attractive on all of these metrics compared to its ASX banking stablemates. But that doesn’t automatically mean CBA shares are a buy today. So what’s the 411?

    Is the CBA share price a buy today?

    According to CommSec, broker Goldman Sachs has a ‘sell’ rating on CBA shares, with a 12-month price target of $73.64 a share. The investment bank and broker points to CBA’s heavy exposure to the retail housing market as the primary reason it is not too keen on CBA shares at $90.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Sebastian Bowen owns shares of National Australia Bank Limited. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of CSL Ltd. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Is the Commonwealth Bank (ASX:CBA) share price a buy at $90? appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/2QVL3TZ
  • ASX 200 flat: NIB update impresses, Altium upgraded

    A graphic showing share price movement, ASX market watch

    At lunch on Monday the S&P/ASX 200 Index (ASX: XJO) is trading broadly flat. The benchmark index is currently down a few points to 7,058.4 points.

    Here’s what is happening on the market today:

    NIB update impresses

    The NIB Holdings Limited (ASX: NHF) share price is surging higher following the release of a trading update. According to the release, for the nine months ending 31 March 2021, NIB reported that its business was performing well despite the ongoing uncertainty surrounding the COVID-19 pandemic. As a result, it expects underlying operating profit to come in at $200 million and $225 million in FY 2021. During the first half, its underlying operating profit was $86.9 million.

    Altium shares upgraded

    The Altium Limited (ASX: ALU) share price is trading flat on Monday despite being upgraded by a leading broker. According to a note out of Shaw & Partners, its analysts have upgraded the company’s shares to a buy rating with a $34.00 price target. The broker believes that Altium is well-placed to benefit from the global economic recovery and expects its revenue to hit an inflection point in FY 2021.

    Perenti rises

    The Perenti Global Ltd (ASX: PRN) share price is pushing higher today. This follows the receipt of a letter of intent from Newcrest Mining Ltd (ASX: NCM) for works at the gold miner’s Red Chris Project. Should everything go ahead as planned, the company advised that it anticipates the project will generate revenue of $38 million over a 16-month period.

    Best and worst ASX 200 performers

    The NIB share price is the best performer on the ASX 200 on Monday by some distance with an 11% gain following its update. The worst performer has been the Whitehaven Coal Ltd (ASX: WHC) share price with a decline of almost 6%. This coal miner’s shares have come under pressure recently amid concerns over issues at its Narrabri operation.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. recommends Altium. The Motley Fool Australia owns shares of Altium. The Motley Fool Australia has recommended NIB Holdings Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post ASX 200 flat: NIB update impresses, Altium upgraded appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/32KNiMv

  • Universal Biosensors (ASX:UBI) share price dips despite latest update

    A doctor looks unsure, indicating share price uncertainty for ASX medical companies

    The Universal Biosensors Inc (ASX: UBI) share price is edging lower today. As of writing, shares in the medical diagnostics company are trading for 73 cents each, down 1.3%. By comparison, the S&P/ASX All Ordinaries Index (ASX: XAO) is 0.02% lower.

    Today’s price movement comes after the company announced another deal to distribute one of its products – this one in South Africa.

    Let’s take a closer look at today’s news and what it means for the Universal Biosensors share price.

    What’s up with the Universal Biosensors share price?

    In a statement to the ASX, Universal Biosensors advised it has entered a nonexclusive agreement with Vicard SA for the distribution of its wine testing platform device, Sentia, in South Africa. The deal is for 3 years.

    Vicard SA is an importer of products necessary for wine production into South Africa. It has been in operation for more than 20 years.

    This is the third such deal for the Sentia product. The company recently announced distribution deals in Chile and the United States. The Universal Biosensors share price rose 6% on the former deal and fell on the latter.

    Sentia is a portable, wine-testing device that delivers results in less than 60 seconds. The test measures the amount of free sulphur dioxide present in a wine product. Free sulphur dioxide needs to be present in wine for bacterial stability.

    Management commentary

    Universal Biosensors CEO John Sharman said:

    Securing distribution in South Africa is another step forward in the commercialisation of Sentia globally. Vicard SA has 20 years of experience supplying high quality resources to the South African wine industry and there are 500 wineries which will now have the opportunity to experience Sentia.

    Along with the current capability we believe the possibility of Sentia’s future testing capability for glucose, fructose, malic acid and others will add significant value to the winemaking industry. We are negotiating terms with a number of key industry players around the world and look forward to reporting additional distribution partnerships in due course.

    Vicard SA CEO Michael Fernandez added:

    I am thrilled to be bringing Sentia to the South African wine industry. The initial reaction from my customers has been very positive and they understand the unique benefits the system offers.

    Universal Biosensors share price

    Over the past 12 months, the Universal Biosensors share price has increased 279%. In fact, just over the last month, the company’s value has appreciated 28.6%. On 9 April, the share price went up 36% in one day after a medical-related update.

    The Universal Biosensors share price has a market capitalisation of $127.8 million.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Marc Sidarous has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Universal Biosensors (ASX:UBI) share price dips despite latest update appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/32P6BV0

  • Here’s why the Archer Materials (ASX:AXE) share price is up today

    A medical researcher works on a bichip, indicating share price movement in ASX tech companies

    The Archer Materials Limited (ASX: AXE) share price is climbing after news the company has secured access to the infrastructure it needs to continue developing its biochip.

    The company’s new access to world-class facilities means it can continue working towards biochip feature sizes of less than 10-nanometres.

    At the time of writing, the Archer Materials share price is up 3.5%, trading for 89 cents.

    Let’s take a closer look at the news out of the materials technology developing company today.

    Next step towards a 10-nanometre biochip

    Today, Archer announced it has access to some of the rare instruments and facilities able to work on nanoscale devices. As a result, the company can begin scaling down its biochip technology to 10 billionths of a metre (10-nanometres (nm)).

    The company’s biochip is a lab-on-chip device. It allows medical laboratory tests on an integrated circuit and includes multiple functional areas and componentry. It also includes microfluidic channels and active biosensing areas.

    Replicating the abilities of the Biochip on a scale of less than 10nm would place Archer’s technology as the global best-in-class in the semiconductor industry, the company has said previously.

    Archer’s access to a suite of deep tech infrastructure resources adds to its access to a $150 million research and prototype semiconductor foundry where it fabricates its devices.

    Commentary from management

    Archer CEO Dr Mohammad Choucair welcomed the news, saying:

    We are very pleased to secure access to world-class facilities that would otherwise be extremely costly to purchase and operate ourselves.

    Archer’s growth has involved integrating the company’s early-stage tech development within institutional scale operations, and this ultimately translates to maintaining a strong cash position and no corporate debt.

    Archer Materials share price snapshot

    The Archer Materials share price is having a fantastic year on the ASX.

    Currently, the Archer Materials share price is up 71% year to date. It’s also up 423% over the last 12 months.

    The company has a market capitalisation of around $194 million, with approximately 226 million shares outstanding.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned.

    The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Here’s why the Archer Materials (ASX:AXE) share price is up today appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3tRhv8l

  • Perenti (ASX:PRN) share price climbs on North American expansion plans

    mining asx share price rise represented by female mining exec talking happily on phone

    The Perenti Global Ltd (ASX: PRN) share price is on the rise in morning trade. This comes after the company announced it has received a lucrative opportunity to expand its North American presence.

    At the time of writing, the mining services company’s shares are fetching $1.13, up 4.15%.

    Continued North America expansion

    Perenti shares are in the green today after investors digest the company’s latest positive announcement.

    In today’s release, Perenti advised its subsidiary, Barminco, has received a letter of intent from Newcrest Mining Ltd (ASX: NCM) for works at the Red Chris Project.

    Located around 80 kilometres south of Dease Lake in northwest British Columbia, Canada, the Red Chris Project is a copper-gold mine. In 2019, Newcrest acquired a 70% interest in the Red Chris Project, in a joint venture with Imperial Metals.

    Under the proposed agreement, Barminco will conduct a number of services for the development of an underground exploration decline. These include mobilisation and site establishment activities and development to build a 3.5-kilometre decline.

    Essentially, a decline is an underground system of ramps and horizontal crosscuts that connects access points targeting specific mineralised areas. However, Newcrest will also use the decline to support access to extend the operation of the open pit.

    It is expected that both parties will come together in the coming weeks to formally sign off on the first stage of works. Commencement of ground activities is scheduled for mid-2021.

    The Perenti share price is responding positively after the company advised it anticipates the project will generate revenue of $38 million over the 16-month period.

    Management commentary

    Perenti managing director and CEO Mark Norwell touched on the exciting development, saying:

    Geographic expansion has been a key focus of our 2025 strategy and this early-stage work at Red Chris builds on our regional growth capabilities after commencing in North America just over a year ago.

    The underground exploration decline works are a significant opportunity and puts the Company in a strong position to access the much wider scope of works associated with the potential block cave development that Newcrest aims to progress towards in the coming years.

    This project fits with our strategy as we continue to pursue high quality growth opportunities within attractive mining jurisdictions, partnering with top-tier producers holding multi-mine portfolios and long-life, expandable assets.

    Perenti share price summary

    The Perenti share price has gained around 41% over the past year but is down 20% year to date. The company’s shares have been on a steep decline since mid-February following the release of its half-year results.

    Perenti has a market capitalisation of roughly $758 million, with more than 704 million shares outstanding.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Perenti (ASX:PRN) share price climbs on North American expansion plans appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3njqBbu

  • Doctor Care Anywhere (ASX:DOC) share price lifts on upbeat update

    flying medical asx share price represented by doctor in superhero outfit

    The Doctor Care Anywhere Group PLC (ASX: DOC) share price is lifting today after the company released its first quarterly update.

    At the time of writing, the Doctor Care Anywhere share price is up 3.8%, trading at $1.07.

    It’s been a rollercoaster ride for investors since the United Kingdom-based company debuted on the ASX on 4 December. At a listing price of 80 cents per share, it was off to the races when its shares opened at around $1.00.

    The Doctor Care Anywhere share price pushed as high as $1.52 by 11 January before grinding back lower to the $1.00 level. 

    Why is the Doctor Care Anywhere share price up today?

    Doctor Care Anywhere delivered a well-rounded first-quarter update with unaudited underlying revenue increasing 16.5% to £4.4 million (A$6.87 million). The company reported a 14.7% increase in sign-ups to the platform to 500,000 and a 21.9% increase in consultations delivered to 90,500.

    The positive news saw the Doctor Care Anywhere share price open 5% higher today at $1.085. 

    The company utilises its relationships with health insurers, healthcare providers and corporate customers to connect with patients and deliver a range of telehealth services.

    The total number of people who have an entitlement to use its services, which the company refers to as ‘eligible lives’, increased to 2.37 million in the first quarter. This has been driven by expanding its membership bases of existing channel partners and new partner, Allianz

    Another key metric to highlight in the quarterly is its gross profit margins. A metric that has arguably come under heavy scrutiny for the likes of Redbubble Ltd (ASX: RBL) and  Kogan.com Ltd (ASX: KGN). The company noted that underlying gross profit margins for the first quarter of FY21 were 43.2%, down 3.6 percentage points on the prior quarter.

    This was driven by a combination of higher than expected demand for its services and increased demand for its GPs to deliver on the national COVID-19 vaccine rollout. On a positive note, the company expects this reduction to be temporary and for margins to normalise over time. 

    Management commentary 

    Commenting on the performance, CEO Bayju Thakar said: 

    The perennial demands on traditional health systems combined with government-imposed lockdowns, which are now easing in the UK, have fostered a level of adoption and acceptance of telehealth services in the past 12 months, by both patients and clinicians, that might previously have taken five years.

    The speed of the UK vaccine rollout will allow our secondary care services, such as diagnostics, to open and this will further support our growth as hospital availability returns to normal.

    Mr Thakar said the business continued to perform strongly, reflecting the long-term changes driving consumer demand for telehealth.

    As we look beyond COVID lockdowns to a more widely vaccinated UK population, we are confident of year on year revenue growth of at least 100% above FY 2020, driven by growth in telehealth lives, activations and consultations together with our ability to grow areas of the business curtailed in the lockdowns.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Doctor Care Anywhere Group PLC. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of Kogan.com ltd. The Motley Fool Australia has recommended Doctor Care Anywhere Group PLC and Kogan.com ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Doctor Care Anywhere (ASX:DOC) share price lifts on upbeat update appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3vhSLqf

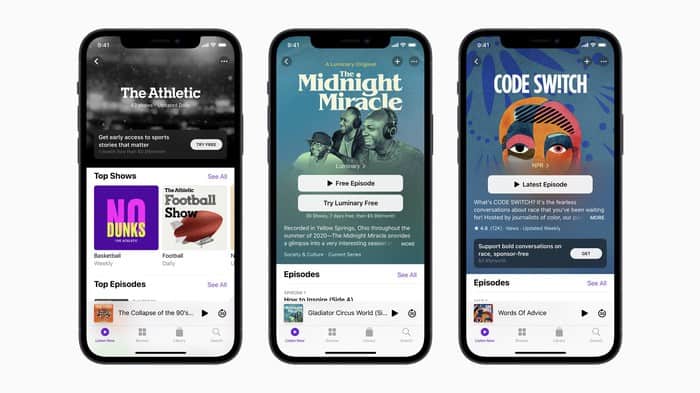
  • Apple takes aim at Spotify’s podcast ambitions

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Despite being extremely early in podcast distribution, Apple (NASDAQ: AAPL) neglected its podcast app for a long time, failing to grow subscriptions, streaming advertisements, or exclusive, high-quality content. That left an opening for Spotify (NYSE: SPOT) to build and acquire the tools necessary to make podcasts a success for listeners and producers alike, potentially making it Spotify’s biggest business long term. 

    That dynamic changed on Tuesday when Apple introduced subscriptions to its Podcast app. Subscriptions will allow producers to charge listeners directly for their content. It could be an effective way to monetize content, but does it really hurt Spotify’s position in the industry? 

    Apple’s theory of the case 

    What Apple is betting on is that easy-to-use subscriptions will be a win-win for producers and listeners. Producers can make money while listeners can get premium, ad-free content. The theory makes sense, but may not be as easy to pull off as you might think. 

    Print organizations have proven that paywalls are a tough way to build a business model. The New York Times and a handful of other large organizations have had success moving content behind a subscription paywall, but most who’ve attempted paywalls have failed. 

    The reason why paywalls haven’t made sense on the internet is that a free version of the information users might be looking for is likely only a click away. And information travels so quickly that paying for content is a tough ask for consumers. 

    Audio may be a little different because the content is unique and consumed differently. A conversation between a podcaster and a guest can’t easily be replicated into print or other audio forms like the content of a news article can. So the paywall could work for Apple and podcasters because it’s the exclusive place to find the content people are seeking. 

    The challenge will be discovery. Free podcasts are easy to find and they open up a world of users to podcast producers. Once a podcast goes behind a paywall there’s a lot more friction between users and discovery. 

    Spotify is playing a different game

    Apple is a big competitor of Spotify in podcasts, but this move may not upend the company’s plans. Spotify already has a subscription business in music and exclusive podcasts, and subscriptions to some podcasts may be coming. But I think the biggest opportunity will be building out an advertising business with the user data and advertiser network to make “free” podcasts profitable. 

    Podcast production, which Spotify has in its portfolio, is also not dependent on being on Spotify’s platform. It has creation tools with Anchor and an editing suite with Soundtrap, just to name a couple of tools. So it’s possible that Spotify will make money on podcasts that are made with its tools but distributed through Apple Podcasts. 

    Do subscriptions make sense in podcasting at all? 

    For creators, it’s great that Apple is providing a new revenue option in its podcast business. But the biggest question facing Apple is whether or not subscriptions make sense at all in podcasts. If listeners don’t mind a few targeted ads in a podcast, just as they get with radio content, then the subscription model may not generate as much revenue as ad-supported podcasts. 

    Aggregation is another thing to think about in podcast subscriptions. Paying one lump sum for access to all podcasts may be appealing, but paying 5-10 subscription fees may be a turnoff. There’s a reason music, TV, and now streaming have aggregated content from multiple sources into a subscription and not charged on a per channel or per record label basis. 

    There’s also the medium that makes podcasts slightly different from any other streaming service to date. Podcasts are a passive medium that you can listen to while working out, driving, or doing almost anything throughout the day. There’s no action needed, unlike clicking on an article or actively watching TV. Given the passive nature, ads may not be the end of the world for podcasts. And if discovery outweighs the revenue from subscriptions, I could see an ad model working out better than subscriptions long term.

    As an Apple podcast listener, I’m happy to see the company put more attention into audio content. But as a Spotify shareholder, I don’t think it’s as big a threat as some investors might think. And even if subscriptions are successful, Spotify is small and nimble enough to adapt to the market as it grows, so my money is still on Spotify winning the podcast battle long term. 

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Travis Hoium owns shares of Apple and Spotify Technology. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Apple and Spotify Technology and recommends the following options: short March 2023 $130 calls on Apple and long March 2023 $120 calls on Apple. The Motley Fool Australia has recommended Apple. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Apple takes aim at Spotify’s podcast ambitions appeared first on The Motley Fool Australia.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3dPN2lC

  • The Fatfish (ASX:FFG) share price is up 9% this morning. Here’s why

    rising asx share price represented by gold fish jumping out of water

    The Fatfish Group Ltd (ASX: FFG) share price is up today after news broke of yet another acquisition. Fatfish has announced it will buy a 55% stake in Pay Direct Technology, a Southeast Asian payment gateway provider.

    The Fatfish Group share price is currently trading at 12.5 cents, up 8.7% from Friday’s closing price.

    Let’s take a closer look at Fatfish’s most recent acquisition.

    Pay Direct acquisition 

    The Fatfish share price is on the rise after the company advised its 55% stake in Pay Direct will have “impactful synergies” with its buy now, pay later (BNPL) rollout.

    Pay Direct operates QlicknPay, a payment gateway technology suite that offers fast payment set up between merchants and financial institutions. It also allows online merchants to accept direct payments through many payment options.

    According to Fatfish’s release, a payment gateway is an important component in accelerating its BNPL services in Southeast Asia.

    Currently, QlicknPay has deals with Malaysian Central Bank’s online payment network as well as Mastercard, Visa and Paypal. It’s used by more than 500 merchants.

    QlicknPay is also used by OCBC Bank, Malaysia’s second largest bank, as well as Public Bank Berhad, one of the country’s most profitable.

    In further news driving the Fatfish share price, the company advised that QlicknPay’s popularity resulted in its transaction volume increasing by an average of 43% each month in 2020.

    Currently, QlicknPay processes $32 million worth of payments each month and $380 million worth of payments each year. 

    Fatfish Group will be paying $470,000 in cash for its 55% stake in Pay Direct.

    Fatfish has been in the news a lot lately following a string of acquisitions. The company purchased a strategic 85% stake in BNPL company Forever Pay earlier this month, signalling its launch into the space. And, in February, a subsidiary of Fatfish acquired assets from iCandy Interactive Ltd (ASX: ICI).

    Fatfish Group share price snapshot

    The Fatfish Group share price has been flourishing on the ASX lately, with today’s news providing only its latest boost.

    Currently, the Fatfish Group share price is up 213% year to date. It’s also up by a whopping 1,150% over the last 12 months.

    The company has a market capitalisation of around $108 million, with approximately 940 million shares outstanding.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Mastercard, PayPal Holdings, and Visa and recommends the following options: long January 2022 $75 calls on PayPal Holdings. The Motley Fool Australia has recommended Mastercard and PayPal Holdings. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post The Fatfish (ASX:FFG) share price is up 9% this morning. Here’s why appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/2Qu9gRa

  • This broker just upgraded the Altium (ASX:ALU) share price to a buy

    asx 200 share price upgrade to buy represented by hand drawing line under the word upgrade

    The Altium Limited (ASX: ALU) share price is trading lower on Monday morning.

    At the time of writing, the electronic design software platform provider’s shares are down 0.2% to $28.48.

    This means the Altium share price is now trading 29% lower than its 52-week high of $40.21.

    Is the Altium share price good value?

    The recent weakness in the Altium share price is being seen as a buying opportunity by one leading broker.

    According to a note out of Shaw & Partners, its analysts have upgraded its shares to a buy rating and lifted their price target on them to $34.00.

    Based on the current Altium share price, this implies potential upside of 19% over the next 12 months.

    What did Shaw & Partners say?

    Shaw & Partners made the move due to Altium’s strong fundamentals and leverage to economic growth.

    The broker believes the company is well-placed to benefit from increasing demand for electronic design software as economies recover from the pandemic.

    Furthermore, its analysts have looked back to how Altium performed during and after the global financial crisis. Based on this, the broker suspects that its revenue will hit an inflection point in FY 2021.

    In addition to this, Shaw & Partners believes its shares trade on attractive multiples in comparison to many of its software-as-a-service (SaaS) peers.

    Is anyone else positive on Altium?

    Shaw & Partners isn’t the only broker that sees value in the Altium share price. Last week analysts at Citi retained their buy rating and $33.50 price target on the company’s shares.

    Although Citi suspects that Altium could fall short of expectations in FY 2021 due to discounting, it remains positive. This is due to its belief, much like Shaw & Partners, that Altium is coming to the end of its downgrade cycle.

    Citi’s price target implies potential upside of just over 16% for its shares over the next 12 months.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. recommends Altium. The Motley Fool Australia owns shares of Altium. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post This broker just upgraded the Altium (ASX:ALU) share price to a buy appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/2QzIZAW

  • Tyro (ASX:TYR) share price drops despite April transaction values surging 155%

    Fall in ASX share price represented by white arrow pointing down

    The Tyro Payments Ltd (ASX: TYR) share price is slipping today, despite yet another positive COVID-19 trading update

    At the time of writing, the Tyro share price is down 2.3% to $3.83 per share. However, Tyro shares have rebounded more than 50% in the last 3 months following the company’s crippling terminal outages and scathing short seller attack back in January. 

    While its recovery story is in its early days, the business has so far shown promise in improving its transaction values and driving additional growth initiatives. 

    What’s driving the Tyro share price?

    Today’s COVID-19 trading update highlights a 155% date-on-date increase from 1 April to 23 April. This compares to the respective 40%, 10% and 10% improvement in March, February and January on the prior corresponding period. 

    The strong uplift in April transaction values could be driven factors such as the Easter holidays and the government’s $1.2 billion tourism support package. 

    Retail trade data is also supportive of the improvement in Tyro’s business, with the Australian Bureau of Statistics (ABS) revealing a 2.3% seasonally adjusted increase in March 2021. This was led by increases in Victoria and Western Australia, with both states rebounding from COVID-19 lockdown restrictions during February.

    The ABS highlighted that cafes, restaurants and takeaway food services led the industry rises, which were again driven by Victoria and Western Australia. 

    The data is good news for Tyro’s business with 35% of its merchants in the hospitality sector that drive 43% of transaction values, as per its 1H21 results.

    From a regional perspective, Victoria and Western Australia contributed a respective 18% and 11% of transaction values in the first half. While Western Australia’s contribution to overall transaction values have remained steady, Victoria has slipped from 25% in FY19, to 23% in FY20 and 18% in 1H20. A recovery in Victorian transaction values could be key in driving the Tyro share price.

    Growth initiatives in FY21 

    Tyro Connect

    Tyro is working on a solution to connect apps and services with a business’ POS system. The company is currently focused on the most critical areas of Australia’s hospitality businesses including ordering, menu management and bookings. 

    This feature enables hospitality businesses to easily integrate and more effectively use the apps they need to thrive in today’s competitive market. Tyro has currently signed up apps including DoorDash, Deliveroo, Google and more. 

    As a relatively new feature, Tyro has signed up 71 merchants as at 18 February, with 286,000 transactions processed. 

    Bendigo Bank alliance 

    In October 2020, Tyro signed a partnership with Australia’s fifth biggest retail bank, Bendigo and Adelaide Bank Ltd (ASX: BEN). This partnership is expected to drive Tyro’s key performance metrics across transaction values and merchants. According to Tyro, pre-integration activities are tracking well, with commercial completion expected by the end of 2H21 to be followed by a roll-out. 

    Merchant dongle solution 

    While Tyro CEO, Robbie Cooke believes a terminal outage of such magnitude will “never happen again”, the business is preparing a back-up solution.

    Tyro is developing a dongle failover solution for every merchant as an extra level of safety and means to rebuild merchant trust. 

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Kerry Sun has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Tyro Payments. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Tyro (ASX:TYR) share price drops despite April transaction values surging 155% appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3aAPWZh