Category: Stock Market

  • Apple introduces slate of updated and new products

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.
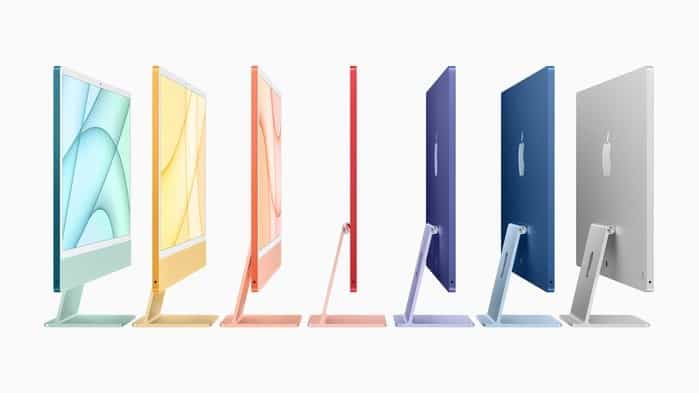
    7 different coloured iMac's

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    In its latest “event” (i.e., new product introduction) on Tuesday, Apple (NASDAQ: AAPL) unveiled a host of fresh products, most of which were improvements on existing offerings rather than entirely new goods.

    Arguably the most impressive new hardware was the company’s latest iMac desktop. This comes in a range of bright colors (seven in total) and is the thinnest iMac yet. More importantly, it is powered by Apple’s recently introduced, proprietary M1 chip.

    Apple also took the wraps off its new iPad Pro, which like the iMac has an M1 in its guts. Promising a “massive leap in performance,” among other improvements, this model boasts a Liquid Retina XDR display and an ultrawide-angle front camera.

    Other product evolutions cover the Apple TV 4K, which has a new remote that is more suited to navigating on-screen options, and a purple color option for both the iPhone 12 and iPhone mini. One new item is the AirTag, a tracking device that hooks into the company’s Find My ecosystem, allowing users to keep tabs on their valuables.

    Another fresh offering are Apple Podcasts Subscriptions, described as “a global marketplace for listeners to discover premium subscriptions offered by their favorite creators,” in addition to a vast and intimidating number of free-to-listen shows.

    Lastly, there’s Apple Card Family. This allows holders of the eponymous credit card to establish a “family sharing group” that combines their credit lines and permits co-management between two members of that group.

    While none of these individually feels as if it’ll be a game-changer, it’s encouraging to see the company continue striving to innovate and keep its lineup fresh. Apple-watchers should pay particular attention to feedback about the machines powered by the new(ish) M1; the company has pinned a lot of hope on that chip.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Eric Volkman owns shares of Apple. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Apple and recommends the following options: short March 2023 $130 calls on Apple and long March 2023 $120 calls on Apple. The Motley Fool Australia has recommended Apple. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Apple introduces slate of updated and new products appeared first on The Motley Fool Australia.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/2Pf2dLM
  • Whispir (ASX:WSP) share price charges higher following Q3 update

    A happy woman at her laptop punches the air, indicating a rising share price

    In morning trade, the Whispir Ltd (ASX: WSP) share price is pushing higher.

    At the time of writing, the communications workflow platform provider’s shares are up 3% to $3.34.

    Why is the Whispir share price pushing higher?

    Investors have been buying Whispir’s shares following the release of its third quarter update.

    According to the release, at the end of March, the company’s Annualised Recurring Revenue (ARR) was up 20.3% over the prior corresponding period to $50.3 million. This was also up 5.2% since the end of the second quarter.

    Management advised that this was driven by continued strong growth in net new customers. During the period, the company onboarded 43 new customers, bringing its total to 750. This is up from 558 this time last year.

    Whispir also revealed a 22.5% increase in quarterly cash receipts to $10.9 million. This left it with a cash and equivalents balance of $51.7 million at the end of March. Management believes it is well-fund for growth.

    Management commentary

    Whispir’s CEO, Jeromy Wells, said: “Our successful capital raising during the Quarter ensures we are able to fast-track our product development and increase our sales and marketing capability to scale the business faster, particularly in Asia and North America where we have large addressable target markets. In ANZ, we are successfully using our land and expand strategy to not only acquire new customers but increase platform usage by our existing customer base.”

    “While we are continuing to build our customer base, existing customers remain the primary driver of revenue growth. This reflects the stickiness of our platform which easily integrates with existing IT systems and can be used for multiple use cases.”

    Outlook

    Positively for shareholders and the Whispir share price, the company is on track to achieve its guidance for FY 2021.

    This morning management reaffirmed its ARR guidance of $53 million to $55.3 million and revenue guidance of between $49 million to $51 million.

    It also stressed that it remains focused on executing its long-term growth strategy; increasing customer numbers, platform usage, and revenue in ANZ, Asia and North America.

    Mr Wells concluded: “Our strengthened balance sheet enables us to accelerate our international expansion to support our longer-term business objectives of 50% of total group revenue being generated internationally by the end of FY23. Given the strength of our ANZ business, we’re increasing our investment in technology and headcount in Asia and North America to drive customer acquisition and product-led growth.”

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Whispir Ltd. The Motley Fool Australia has recommended Whispir Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Whispir (ASX:WSP) share price charges higher following Q3 update appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3dCERsD

  • Redbubble (ASX:RBL) share price crashes 12% on Q3 update

    Fall in ASX share price represented by white arrow pointing down

    The Redbubble Ltd (ASX: RBL) share price is crashing lower on Thursday morning.

    In morning trade, the ecommerce company’s shares down a disappointing 12% to $4.84.

    Why is the Redbubble share price crashing?

    Investors have been selling Redbubble’s shares this morning following the release of its third quarter and year to date update.

    In respect to the latter, for the nine months ended 31 March, Redbubble reported gross transaction value of $576 million and marketplace revenue of $456 million. This was up 85% and 82%, respectively, over the prior corresponding period.

    Management revealed that a strong Australian dollar weighed on its financial performance during the period. On a constant currency basis, gross transaction value would have been up 94% and marketplace revenue would have jumped 97%.

    This ultimately underpinned a 100% increase in year to date gross profit to $184 million and EBITDA of $51 million.

    What about the third quarter?

    While Redbubble’s top line growth is moderating, it remains very strong.

    For the three months ended 31 March, gross transaction value increased 58% (79% in constant currency) to $134 million and marketplace revenue rose 54% (76% in constant currency) to $103 million.

    Gross profit for the quarter was up 55% (78% in constant currency) to $40 million and EBITDA came in at $2.2 million.

    The latter represents an EBITDA/Marketplace revenue margin of 2.1% for the quarter. This compares to its first half margin of 13.8%.

    No explanation was given for the significant contraction in its margins. However, with its third quarter revenue approximately half of its second quarter revenue, this could have been the result of a reversal in operating leverage.

    Whatever the cause, it seems to have caught the eye of investors today, leading to weakness in the Redbubble share price.

    Today’s sizeable decline means that the Redbubble share price is now down 34% from its 52-week high.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Redbubble (ASX:RBL) share price crashes 12% on Q3 update appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3naYDyw

  • Why the Santos (ASX:STO) share price is in focus

    industrial asx share price on watch represented by builder looking through magnifying glass

    The Santos Ltd (ASX: STO) share price is one to watch in early trade after the Aussie oil and gas giant’s latest quarterly result.

    Why is the Santos share price in focus?

    Santos provided an operational and financial update for the quarter ended 31 March 2021 (Q1 2021). The energy group reported “strong base business,” which helped generate US$302 million in free cash flow for the quarter.

    Santos produced 24.9 million barrels of oil equivalent (mmboe) for the quarter, up 39 per cent on Q1 2020. That was largely thanks to the ConocoPhillips acquisition completed in May 2020, which helped boost capacity.

    Production was down 2 per cent from the previous quarter thanks to lower gas demand in Western Australia and unplanned maintenance in PNG. First-quarter revenue of US$964 million was up 5% on the December quarter and 9% on Q1 2020.

    Average realised liquid natural gas (LNG) prices were up 14.6% to US$6.12 per metric million British thermal units. Realised prices across crude oil, condensate, domestic gas and LPG all climbed higher on Q4 2020 figures.

    The Santos share price is one to watch in early trade following the quarterly update. Shares in the Aussie energy group are up 7.9% and currently outperforming the S&P/ASX 200 Index (ASX: XJO). 

    On the balance sheet side, Santos reported net debt of US$3.6 billion after the US$104 million final dividend. S&P Global Ratings reaffirmed Santos’ investment-grade credit rating with a Stable outlook, with Fitch assigning an inaugural BBB rating during the quarter.

    Importantly, Santos reaffirmed all guidance for FY2021. That includes production of 84 to 91 mmboe with sales volumes of 98 to 105 mmboe. Base capital expenditure of ~$900 million and major growth capex of $700 million is expected for the year. Full-year upstream production cost estimates were maintained at $8.00 to $8.50 per barrel of oil equivalent.

    Foolish takeaway

    All eyes will be on the Santos share price following today’s update, with revenue climbing higher despite lower overall production.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Ken Hall has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Why the Santos (ASX:STO) share price is in focus appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3dEDdqH

  • Megaport (ASX:MP1) share price in spotlight following Q3 update

    asx share price on watch represented by investor peering over top of bench

    Megaport Ltd (ASX: MP1) shares will be in the spotlight during morning trade following the release of the company’s quarterly update. At yesterday’s market close, shares of the global provider of elastic interconnection services were sitting at $11.70.

    Let’s take a look at how the company has been faring.

    How did Megaport perform in Q3?

    Megaport shares will be on the radar today after the company provided investors with a robust result that saw consistent growth in all metrics.

    For the quarter ending 31 March (Q3), Megaport delivered continued growth in monthly recurring revenue (MRR), which came in at $6.8 million for March. This represents a lift of $0.5 million, or an 8% quarter-on-quarter (QoQ) increase.

    Revenue also elevated for the three months to $19.58 million, a jump of $0.9 million or a 5% QoQ increase. When looking at year-on-year change, revenue boosted by more than 25%.

    Megaport advised it had 390 installed data centres at the end of March. This follows the commissioning of five new sites and the dropping of one existing data centre.

    Total enabled data centres stood at 741, reflecting a surge of 25 new centres or 3% growth QoQ. The expanded network footpring came from Megaport’s partnerships with RagingWire, Digital Realty, and CyrusOne.

    In further news that could impact the Megaport share price, the company reported 74 new corporate customers, bringing the total number of customers to 2,117, an increase of 4% QoQ.

    Ports also rose by 346 to 7,037 ports, and total services came to 20,056, a jump of 778 services or a 4% lift QoQ.

    Megaport declared a cash balance of $141.5 million at the end of the March quarter.

    Management commentary

    Megaport CEO Vincent English touched on the company’s near-term outlook, saying:

    As we enter the final quarter of FY21, we have a strong pipeline of new customers, driven by increased requirements from digital transformation initiatives. We see this as an indication that enterprises now have greater line of sight to a post-pandemic normal and that overall IT budgets are improving. Our growth in ports and underlying revenue in the second half of the third quarter was strong, and we expect to see this trend continue.

    Fiscal Year 2021 has highlighted the strong operating leverage in our business model and we remain on track to achieving EBITDA breakeven, on a run rate basis, by June 2021.

    About the Megaport share price

    The Megaport share price has been relatively flat over the last 12 months, rising by 2.54%. Year to date, however, the company’s shares are down by almost 18%.

    Megaport has a market capitalisation of around $1.8 billion, with approximately 156 million shares on issue.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends MEGAPORT FPO. The Motley Fool Australia has recommended MEGAPORT FPO. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Megaport (ASX:MP1) share price in spotlight following Q3 update appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3vbb7Jy

  • The Lithium Australia (ASX:LIT) share price is on watch today. Here’s why

    A hand holds a green lithium battery with a leaf, indicating positive share price movement for clean ASX lithium miners

    The Lithium Australia NL (ASX: LIT) share price is on watch today after news a subsidiary of the company received Clean Energy Council (CEC) approval. Soluna Australia Pty Ltd, of which Lithium Australia owns 50%, received CEC approval for its residential battery storage product.

    The Lithium Australia share price closed yesterday, trading at 12 cents.

    Let’s take a closer look at the news shared by the battery metals company this morning.

    Residential battery storage product

    Lithium Australia announced today that Soluna Au’s 10K Pack HV has received CEC approval and can be marketed in Australia.

    The CEC inspects and approves all clean energy products sold in Australia to ensure their safety. 

    The 10K Pack HV is a residential battery energy-storage system for homes with single or three-phase power. The product stores solar power and has 10-kilowatt hours of storage capacity.

    Customers can purchase up to 4 of the batteries, increasing their storage capacity to 40-kilowatt hours.

    Today’s announcement also included news of a distribution deal.

    Soluna Au has signed a distribution agreement with Legend Corporate Services Limited, a company that markets and installs electrical products in Australia and New Zealand.

    Legend has more than 350 employees across manufacturing, engineering, laboratory, and distribution facilities.

    Commentary from management

    Lithium Australia managing director Adrian Griffin welcomed the product’s CDC approval, saying:

    Signing a national distributor agreement will increase our market penetration and rate of sales.

    It is a timely transaction that comes on the back of CEC approval for Soluna’s 10 kilowatt hour pack which extends our product range, providing greater choice for consumers.

    Lithium Australia share price snapshot 

    The Lithium Australia share price is still riding high on the ASX’s lithium wave.

    Currently, the Lithium Australia share price is up 100% year to date and has lifted 140% over the last 12 months.

    The company has a market capitalisation of around $108 million, with approximately 901 million shares outstanding.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor Brooke Cooper has no position in any of the stocks mentioned.

    The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post The Lithium Australia (ASX:LIT) share price is on watch today. Here’s why appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/32zkc2D

  • High-flying ASX tech shares could fall another 90%: fundie

    rise in asx tech share price represented by digitised rocket shooting out of person's hand

    After a huge 2020, growth shares have had a bit of a rest this year.

    Technology, specifically, led the way in massive market gains in 2020 after the March COVID-19 trough. The S&P ASX All Technology Index (ASX: XTX) gained a whopping 125% from 20 March to the end of the year.

    But this year has been a different story, with growth and tech shares falling out of favour.

    The ASX All Tech index remains flat, increasing just 0.9% since New Year’s Day.

    The rotation to value stocks has been triggered by a fear that inflation would rise as the world recovers from the pandemic. When inflation rises, interest rates could rise. 

    And that’s bad news for high-growth stocks, according to Platinum Asset Management chief executive Andrew Clifford.

    “Many high-growth stocks have seen their share prices fall considerably from their recent highs, with bellwether growth stocks such as Tesla Inc (NASDAQ: TSLA) down 27% from its highs, Zoom Video Communications Inc (NASDAQ: ZM) down 45%, and Afterpay Ltd (ASX: APT) down 35%,” he said in an update to investors.

    “Theoretically, rising interest rates have a much greater impact on the valuation of high-growth companies than their more pedestrian counterparts. As such, it is not surprising to see these stocks most impacted by recent moves in bond yields and concerns about inflation.”

    Is the slowdown in growth shares temporary or chronic?

    Multiple experts have predicted that the aversion to growth stocks is temporary, and the market would soon return to the 2020 darlings.

    T Rowe Price Group Inc (NASDAQ: TROW)’s investment committee for its Australian arm last month already started shifting its allocation from value to growth.

    Nucleus Wealth head of investments Damien Klassen also stated last month that pre-COVID deflationary forces would reassert themselves soon.

    Clifford disagrees. He has grave fears for growth stocks that so many people ploughed their money into last year.

    “For many (but not all) of the favourites of 2020, we would not be surprised to see them fall another 50% to 90% before the bear market in these stocks is over,” he said.

    “If our concerns regarding long-term interest rates come to fruition, this will be a dangerous place to be invested.”

    His bearish view was based on his forecast that interest rate rises would be irresistible.

    “It is hard to see how we can avoid a strong cyclical rise in inflation,” he told investors.

    “It is an environment where there is likely to be ongoing upward pressure on long-term interest rates.”

    And history could serve as an example.

    “We only need to look to the end of the tech bubble in 2000 to 2001 for an indication of how this may play out,” Clifford said.

    “The much-loved ‘new world’ tech stocks collapsed in a savage bear market, while the out-of-favour ‘old world’ stocks rallied strongly.”

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Tony Yoo owns shares of AFTERPAY T FPO. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Tesla and Zoom Video Communications. The Motley Fool Australia owns shares of AFTERPAY T FPO. The Motley Fool Australia has recommended Zoom Video Communications. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post High-flying ASX tech shares could fall another 90%: fundie appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3xcDzMN

  • Is the BHP (ASX:BHP) share price in the buy zone after its update?

    A happy miner tips his hard hat, indicating good ashare price results for ASX mining stocks

    The BHP Group Ltd (ASX: BHP) share price was out of form on Wednesday following the release of its third quarter update.

    The mining giant’s shares fell 0.5% to $47.21.

    How did BHP perform?

    For the three months ended 31 March, BHP delivered record production at Western Australia Iron Ore (WAIO) and record average concentrator throughput at its Escondida copper mine.

    This led to the miner holding firm with its FY 2021 production guidance for petroleum and iron ore and lifting its copper production guidance.

    However, one area not performing in line with expectations is its metallurgical coal business. BHP has reduced its guidance due to poor weather conditions.

    Is the BHP share price in the buy zone following its update?

    Analysts at Goldman Sachs were pleased with BHP’s performance during the third quarter. As a result, the broker has retained its buy rating and lifted its price target to $54.20.

    Based on the current BHP share price, this implies potential upside of almost 15% over the next 12 months.

    And with Goldman Sachs forecasting fully franked dividend yields of 6.6% and 6.7%, respectively, over the next two years, this potential return stretches to over 21.5%.

    What did Goldman say?

    Goldman commented: “BHP reported better than expected oil, met coal, copper and iron ore production for the March Q (vs. GSe). Some positive adjustments have been made to FY21 production guidance, most of which we already capture, with Escondida copper production upgraded (and cost guidance lowered), and now expected to be flat in FY22 (previously guided down), iron ore and oil to be at the upper end of the FY21 range, but coal (met and thermal) downgraded (to in-line with GSe) on wet weather and weak demand, and other copper (Spence ramp-up) trimmed slightly.”

    “We retain our Buy rating on BHP on […] strong earnings growth and FCF: We forecast a c. 50% increase in EBITDA and a doubling of FCF in FY21 (equating to c. 10% FCF yield), driven by our positive view on met coal, copper and oil prices,” it added.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Is the BHP (ASX:BHP) share price in the buy zone after its update? appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/3n7JHkZ

  • Analyst sees Netflix falling 38% after earnings

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    person with a remote in their hands watching netflix

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Netflix (NASDAQ: NFLX) first-quarter earnings show what happens when there isn’t a global pandemic to artificially boost subscriber totals, and that has one Wall Street analyst seeing the video streaming giant’s stock cratering.

    Although Wedbush analyst Michael Pachter actually raised his price target on Netflix by $2 per share to $342, it’s still 38% below where the stock closed the day before. However, he maintained his underperform rating on the stock, which is the equivalent of a sell.

    It’s not as though Netflix didn’t experience any growth. It added 4 million new subscribers during the quarter, reaching 207.6 million, and revenue was up 24% year over year. But the numbers underwhelmed the market because management had forecast 6 million additions, though the top-line numbers were roughly in-line with guidance.

    Netflix guidance for next quarter is even more dismal, however, as it expects to add just 1 million new accounts.

    Pachter, who has been pretty much bearish on Netlfix shares for over a decade, told investors in a note that the streamer has a “considerable first-mover advantage.” But because it’s reaching a saturation point in the U.S., that advantage won’t carry it very far anymore. 

    If Netflix wants to keep growing, it will have to do so overseas. While that offers a compelling opportunity, it’s balanced by the costs of content acquisition that are needed to keep acquiring new members. 

    The analyst believes investors should only expect to see Netflix producing subscriber growth rates in the high single digits.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Where to invest $1,000 right now

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for more than eight years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes are the five best ASX stocks for investors to buy right now. These stocks are trading at dirt-cheap prices and Scott thinks they are great buys right now.

    *Returns as of February 15th 2021

    More reading

    Rich Duprey has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Netflix. The Motley Fool Australia has recommended Netflix. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post Analyst sees Netflix falling 38% after earnings appeared first on The Motley Fool Australia.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from The Motley Fool Australia https://ift.tt/3dFuEfb

  • 2 sleeping ASX shares ready to break out

    Watering two small seedlings, indicating share price movements for ASX growth and value shares

    A fund manager has named 2 ASX shares that are “unloved” by the market but have the makings for long-term outperformance.

    According to Prime Value Asset Management portfolio manager Richard Ivers, his fund’s best investments are those that are misunderstood by a market that can be excessively focused on short-term fortunes.

    “We think of it like planting a seed,” he posted on Livewire this week.

    “We expect that investment to sprout and grow over time. However, the timing of this ‘sprouting’ is hard to predict as it is dependent on others in the market also recognising value in the underlying asset and bidding up the stock price to reflect it.” 

    This dependency on other investors to ‘wake up’ means investment performance will fluctuate over time.

    “In some periods, many seeds will be sprouting at once, while at others we are planting many seeds but few are sprouting,” said Ivers.

    “Consequently, investment performance should be judged over the long term – not monthly or quarterly.”

    Here are 2 ASX shares Ivers’ fund currently holds. The first recently sprouted, while the second is just about to:

    Mortgage Choice Limited (ASX: MOC)

    A prime example of a sleeper suddenly sprouting was in March when this home loan broking business received a takeover proposal from REA Group Limited (ASX: REA).

    Mortgage Choice shares gained 61% that day. 

    “This followed from a weak February when the stock was -13% on a reasonable but underwhelming profit result,” said Ivers.

    “Clearly, a stock price can vary significantly from day to day while the underlying value moves more slowly. This creates opportunities for longer-term investors.”

    The Mortgage Choice business has a high level of recurring revenue and “very strong cash flow“, according to Ivers.

    “Prior to the bid, it was yielding 7% fully franked and growing its cash earnings.”

    Mortgage Choice shares were flat on Wednesday afternoon, trading at $1.92. 

    United Malt Group Ltd (ASX: UMG)

    United Malt is the world’s 4th largest provider of malted barley, which is an ingredient used for beer and whiskey production.

    Ivers said it had provided “a moderate return” since his fund’s purchase, but has certainly underperformed compared to the rest of the portfolio.

    “However, we believe the outlook has improved. That is, UMG appears to be a seed that has not yet sprouted.”

    With 60% of its revenue coming from the United States, the vaccination rollout there should see alcohol consumption increase as the economy reopens.

    “Yet the stock is well below its high of late 2020 and valuation looks appealing.”

    This unfulfilled potential makes it unique compared to other COVID-recovery ASX stocks.

    “[United Malt] contrasts with travel stocks, many of which are above their pre-COVID high and exposed to a slower Australian vaccination program,” said Ivers.

    “Further, UMG benefits from the longer-term structural growth of craft beer and its demerger from Graincorp Ltd (ASX: GNC), which will deliver efficiencies and higher return on capital. Over time we expect the underlying value to be reflected in the stock price.”

    United Malt shares were down 0.49% on Wednesday afternoon, trading at $4.06. 

    These Dividend Stocks Could Be Your Next Cash Kings (FREE REPORT)

    Motley Fool Australia’s Dividend experts recently released a brand-new FREE report revealing 3 dividend stocks with JUICY franked dividends that could keep paying you meaty dividends for years to come.

    Our team of investors think these 3 dividend stocks should be a ‘must consider’ for any savvy dividend investor. But more importantly, could potentially make Australian investors a heap of passive income.

    Don’t miss out! Simply click the link below to grab your free copy and discover these 3 high conviction stocks now.

    Returns As of 15th February 2021

    More reading

    Motley Fool contributor Tony Yoo has no position in any of the stocks mentioned. The Motley Fool Australia has recommended REA Group Limited. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Bruce Jackson.

    The post 2 sleeping ASX shares ready to break out appeared first on The Motley Fool Australia.

    from The Motley Fool Australia https://ift.tt/2QMM5l7