• Will Netflix Be a $520 Stock?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Brick wall with Netflix sign at headquarters

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Video-streaming veteran Netflix (NASDAQ: NFLX) is trading near all-time highs right now, currently fetching $440 per share. Jefferies analyst Alex Giaimo sees more gains ahead. Giaimo opened coverage of Netflix on Thursday with a buy rating and a price target of $520 per share.

    The investment thesis

    The analyst cited three main reasons to own Netflix shares today:

    • This company’s addressable market is “vastly underappreciated.”
    • Improving profit margins will lead to sustainable free cash flows over time.
    • Netflix has proven its “ability to create value” in a rapidly changing market.

    Giaimo expects year-over-year subscriber growth to remain in double-digit percentages until 2023 alongside a relatively stable penetration of the domestic market. His model assumes Netflix will widen its international household penetration from 18% to 28%, addressing a global market of roughly 850 million broadband households. Meeting the analyst firm’s targets would give Netflix approximately 285 million subscribers in 2023, up from 183 million paid memberships today.

    The financial background

    Netflix has been consuming a lot of cash in recent years due to the high up-front costs of producing a lot of original content. Management has said that 2019 should be the peak of Netflix’s cash burn, topping out at $3.1 billion. Since content production efforts have ground to a halt under COVID-19 lockdown policies, Netflix expects to consume roughly $1 billion of free cash in 2020, followed by larger content production expenses in 2021.

    The key to unlocking positive cash flows is indeed found in wider profit margins. Here’s how Netflix’s operating margins and cash profit margins have developed over the last three years:
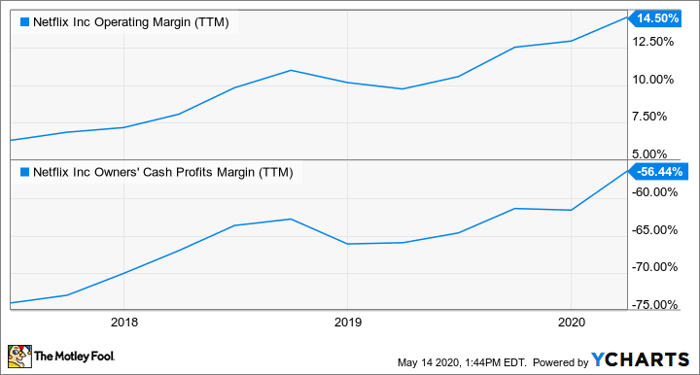
    NFLX Operating Margin (TTM) Chart

    NFLX Operating Margin (TTM) data by YCharts

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    NEW! 5 Cheap Stocks With Massive Upside Potential

    Our experts at The Motley Fool have just released a FREE report detailing 5 shares you can buy now to take advantage of the much cheaper share prices on offer.

    One is a diversified conglomerate trading 40% off it’s all time high, all while offering a fully franked dividend yield of over 3%…

    Another is a former stock market darling that is one of Australia’s most popular and iconic businesses. Trading at a significant discount to its 52-week high, not only does this stock offer massive upside potential, but it also trades on an attractive fully franked dividend yield of almost 4%.

    Plus, this free report highlights 3 more cheap bets that could position you to profit in 2020 and beyond.

    Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares.

    But you will have to hurry because the cheap share prices on offer today might not last for long.

    YES! SEND ME THE FREE REPORT!

    Returns as of 7/4/2020

    More reading

    Anders Bylund owns shares of Netflix. The Motley Fool owns shares of and recommends Netflix. The Motley Fool has a disclosure policy. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Netflix. The Motley Fool Australia has recommended Netflix. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Will Netflix Be a $520 Stock? appeared first on Motley Fool Australia.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from Motley Fool Australia https://ift.tt/2WW563T

  • Why Boral, Corporate Travel Management, United Malt, & Xero are dropping lower

    Downward trend

    In afternoon trade the S&P/ASX 200 Index (ASX: XJO) remains on course to end the week on a high. At the time of writing the benchmark index is up 0.8% to 5,372.5 points.

    Four shares that have failed to follow the market higher today are listed below. Here’s why they are dropping lower:

    The Boral Limited (ASX: BLD) share price is down 3% to $2.50. Investors have been selling the building products company’s shares following the release of a trading update. Boral revealed that revenues are down in most businesses in the first four months of the second half relative to the prior corresponding period. This is largely due to volume and cost pressures associated with bushfires in Australia in January followed by COVID-19 impacts more broadly. EBITDA margins for the period January to April 2020 are tracking ~3-5% lower than in the first half.

    The Corporate Travel Management Ltd (ASX: CTD) share price is down 3% to $10.31. This decline may have been driven by comments out of the International Air Transport Association. It estimates that passenger traffic won’t rebound to pre-crisis levels until at least 2023.

    The United Malt Group Ltd (ASX: UMG) share price has fallen 7% to $3.99. United Malt’s shares have come under pressure after completing a $140 million institutional placement. The malt business raised the funds at $3.80 per share, representing an 11.4% discount to its last traded price. The proceeds will be used to strengthen its balance sheet and provide financial and operational flexibility.

    The Xero Limited (ASX: XRO) share price is down 4.5% to $76.32. This decline may have been driven by a broker note out of Macquarie this morning. According to the note, the broker has downgraded the accounting software provider’s shares to a neutral rating and cut the price target on them to $75.00. It made the move due to the uncertainty being caused by the pandemic.

    If you need a lift after these declines then don’t miss these top shares which have been classed as buys and labelled dirt cheap.

    5 cheap stocks that could be the biggest winners of the stock market crash

    Investing expert Scott Phillips has just named what he believes are the 5 cheapest and best stocks to buy right now. Courtesy of the crashing stock market, these 5 companies are suddenly trading at significant discounts to their recent highs… creating what could be incredible opportunities for bargain-hungry investors.

    Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares to buy now… before the next stock market rally.

    See the 5 stocks

    Returns as of 7/4/2020

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Corporate Travel Management Limited. The Motley Fool Australia owns shares of Xero. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Why Boral, Corporate Travel Management, United Malt, & Xero are dropping lower appeared first on Motley Fool Australia.

    from Motley Fool Australia https://ift.tt/2Z6Y92C

  • Leading fund manager sees good ASX buying opportunities

    Man in white business shirt touches screen with happy smile symbol

    The Australian share market saw particularly strong gains during April, with the S&P/ASX 300 Index (ASX: XKO) up by 9.0%.

    Investment fund manager Perennial commented in its latest monthly report that the ASX market rally in April was across a broad industry base, with the resources sector performing particularly strongly.

    Energy, Gold and Mining Services sectors rally strongly

    Energy was the best performing sector during April, up by an impressive 25%, driven by strong optimism in relation to the outlook of the oil price. Leading the charge in this sector included: Santos Ltd (ASX: STO) shares up by 44% during the month, Woodside Petroleum Limited (ASX: WPL) up by 23% and Origin Energy Ltd (ASX: ORG) up by 27%. These strong rises were on the back of a strong sell-off in the energy sector during March due to a sharp fall in demand.

    Perennial noted that gold shares also performed very strongly, driven by further increases in the gold price, with Evolution Mining Ltd (ASX: EVN) shares up by 34% during April, and St Barbara Ltd (ASX: SBM) and Northern Star Resources Ltd (ASX: NST) both up by 22%. Mining services companies Perenti Global Ltd (ASX: PRN) and Seven Group Holdings Ltd (ASX: SVW) also both saw strong gains.

    Early signs of a post-coronavirus recovery could provide further share price boost

    The Australian Government’s quick response (and that of many other countries) to the crisis, including monetary easing and fiscal stimulus, will no doubt lessen the blow of the crisis on both the local and global economy.

    Also, Perennial pointed out that it is growing increasingly more apparent that the steps taken to limit the spread of the coronavirus in Australia have been more successful than in most other developed nations. This provides Australia with the opportunity to fire up its economy sooner than most. It also positions Australia well to lead other nations in terms of this return to normal economic activity.

    Further buying opportunities for long term investors

    The federal government’s 3-step plan to reopen Australia last week, which aims to see the majority of Australian businesses re-opened by the end of July, will lead the path forward in this respect and I feel this could lead further share price growth in the ASX in the months ahead.

    On a further positive note, with the recent share price falls since February, a significant amount of the downside in the market has now already been factored into current market prices. Also, despite the strong rally in April, there are still opportunities for long-term investors to buy quality companies at more attractive prices.

    For more long-term buying opportunities, don’t miss the report below. 

    5 cheap stocks that could be the biggest winners of the stock market crash

    Investing expert Scott Phillips has just named what he believes are the 5 cheapest and best stocks to buy right now.

    Courtesy of the crashing stock market, these 5 companies are suddenly trading at significant discounts to their recent highs… creating what could be incredible opportunities for bargain-hungry investors.

    Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares to buy now… before the next stock market rally.

    See the 5 stocks

    Returns as of 7/4/2020

    More reading

    Motley Fool contributor Phil Harpur has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Leading fund manager sees good ASX buying opportunities appeared first on Motley Fool Australia.

    from Motley Fool Australia https://ift.tt/2LvMCSo

Sorry, but nothing was found. Please try a search with different keywords.