• Get paid huge amounts of cash to own these ASX dividend shares

    cash piggy bank

    You can be paid huge amounts of cash to own the ASX dividend shares in this article in your portfolio.

    If you’re trying to generate income then the RBA’s official interest rate of 0.25% isn’t going to do much for you unless you’re just protecting capital though the coronavirus crisis.

    But there are some ASX dividend shares which will handsomely reward you for owning them over the years:

    WAM Research Limited (ASX: WAX) 

    WAM Research has a grossed-up dividend yield of 11.1%. It has increased its dividend every year since the GFC. There are few shares that could have provided as much dividend income to investors over the past 10 years. I think it’s one of the best ASX dividend shares.

    It’s a listed investment company (LIC) that invests in undervalued small and medium businesses. It has generated lots of profit in the past, which allows the LIC to steadily pay out a growing fully franked dividend.

    One pleasing factor is that it usually holds a high cash balance for downside protection and opportunities.

    Naos Emerging Opportunities Company Ltd (ASX: NCC) 

    Naos Emerging Opportunities Company has a grossed-up dividend yield of 13.8%. It hasn’t decreased its dividend in its fairly short existence. Recently it has been maintaining the dividend, but there was a string of increases before that. With such a high yield, just maintaining the dividend would be great from this ASX dividend share.

    Naos is another LIC that invests in shares with market capitalisations under $250 million. It’s finding those shares that are undiscovered to the rest of the market. It’s then able to turn some of those capital gains into a solid dividend. Those small caps hopefully have a lot of growth potential.

    Fortescue Metals Group Limited (ASX: FMG) 

    Australian resource shares are known for being decent ASX dividend shares through the cycle. In the good times they are dividend cash machines.

    As long as the China-Australia relationship remains amicable then Fortescue should be able to keep generating solid returns and paying those big dividends.

    It currently offers a trailing grossed-up dividend yield of 11.5%. That’s a very solid yield in the current world.

    Which ASX dividend share to buy

    Fortescue’s yield does look attractive, but you’re up for commodity risks if you go for that one. It’s hard to pick a winner of the other two ASX dividend shares. WAM Research is trading at a sizeable premium to its net assets, though I like the cash position and added diversification that WAM Research’s portfolio has.

    Want some more dividend share ideas?

    These dividend shares could be excellent long-term income picks right now.

    When our resident dividend expert Edward Vesely has a stock tip, it can pay to listen. After all, he’s the investing genius that runs Motley Fool Dividend Investor, the newsletter service that has picked huge winners like Dicker Data (+92%), SDI Limited (+53%) and National Storage (+35%).*

    Edward has just named what he believes is the number one ASX dividend stock to buy for 2020.

    This fully franked “under the radar” company is currently trading more than 24% below its all time high and paying a 6.7% grossed up dividend

    The name of this dividend dynamo and the full investment case is revealed in this brand new free report.

    But you will have to hurry — history has shown it can pay dividends to get in early to some of Edward’s stock picks, and this dividend stock is already on the move.

    See the top dividend stock for 2020

    *Returns as of 7/4/20

    More reading

    Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Get paid huge amounts of cash to own these ASX dividend shares appeared first on Motley Fool Australia.

    from Motley Fool Australia https://ift.tt/2WwMAQr

  • Why Qantas, Webjet and these ASX travel shares are dropping lower today

    The S&P/ASX 200 Index (ASX: XJO) may be storming higher on Friday, but not all shares are doing the same.

    One area of the market that is missing out on today’s rebound is the travel sector.

    Here’s a snapshot of the sector at the time of writing:

    • The Corporate Travel Management Ltd (ASX: CTD) share price is down 3%.
    • The Flight Centre Travel Group Ltd (ASX: FLT) share price is 1.5% lower.
    • The Qantas Airways Limited (ASX: QAN) share price is down 1%.
    • The Webjet Limited (ASX: WEB) share price is down over 0.5%.

    Why are travel shares underperforming today?

    Today’s underperformance appears to have been sparked by comments out of the International Air Transport Association (IATA).

    On Thursday the trade association for the world’s airlines warned that the impact of the pandemic on air travel was likely to be felt for many years to come.

    In fact, the IATA estimates that passenger traffic won’t rebound to pre-crisis levels until at least 2023. This would be a blow for the likes of airline operators such as Qantas and travel bookers such as Flight Centre.

    Though, the IATA’s director general and CEO, Alexandre de Juniac, told CNBC that he is optimistic that more planes will be in the skies in the next six weeks.

    He said: “We are asking governments to have a phased approach to restart the industry and to fly again. We are aiming at reopening and boosting the domestic market by end of the second quarter, and opening the regional or continental markets — such as Europe, North America or Asia-Pacific — by the third quarter, and intercontinental in the fall.”

    Mr de Juniac also revealed that he is against the idea of 14-day quarantine periods for travellers upon arrival. Given how this is arguably the length of a typical holiday, tourism markets are likely to struggle with restrictions of this nature in place.

    He explained: “We are advocating with governments not to implement quarantine measures that will retain people for two weeks that will arrive anywhere. We think that it is useless provided we have implemented the health and sanitary controls that we are discussing with governments. It is absolutely key for the tourist industry which is so important for so many countries in Europe.”

    It certainly looks like it will be an eventful few months for Australian travel shares. 

    Not sure about travel shares? Then take a look at these dirt cheap shares.

    5 cheap stocks that could be the biggest winners of the stock market crash

    Investing expert Scott Phillips has just named what he believes are the 5 cheapest and best stocks to buy right now.

    Courtesy of the crashing stock market, these 5 companies are suddenly trading at significant discounts to their recent highs… creating what could be incredible opportunities for bargain-hungry investors.

    Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares to buy now… before the next stock market rally.

    See the 5 stocks

    Returns as of 7/4/2020

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia owns shares of and has recommended Corporate Travel Management Limited and Webjet Ltd. The Motley Fool Australia has recommended Flight Centre Travel Group Limited. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Why Qantas, Webjet and these ASX travel shares are dropping lower today appeared first on Motley Fool Australia.

    from Motley Fool Australia https://ift.tt/3bzjWTc

  • Will Netflix Be a $520 Stock?

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Brick wall with Netflix sign at headquarters

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    Video-streaming veteran Netflix (NASDAQ: NFLX) is trading near all-time highs right now, currently fetching $440 per share. Jefferies analyst Alex Giaimo sees more gains ahead. Giaimo opened coverage of Netflix on Thursday with a buy rating and a price target of $520 per share.

    The investment thesis

    The analyst cited three main reasons to own Netflix shares today:

    • This company’s addressable market is “vastly underappreciated.”
    • Improving profit margins will lead to sustainable free cash flows over time.
    • Netflix has proven its “ability to create value” in a rapidly changing market.

    Giaimo expects year-over-year subscriber growth to remain in double-digit percentages until 2023 alongside a relatively stable penetration of the domestic market. His model assumes Netflix will widen its international household penetration from 18% to 28%, addressing a global market of roughly 850 million broadband households. Meeting the analyst firm’s targets would give Netflix approximately 285 million subscribers in 2023, up from 183 million paid memberships today.

    The financial background

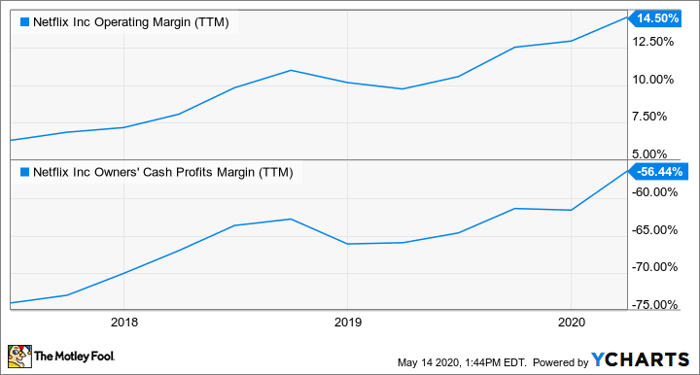
    Netflix has been consuming a lot of cash in recent years due to the high up-front costs of producing a lot of original content. Management has said that 2019 should be the peak of Netflix’s cash burn, topping out at $3.1 billion. Since content production efforts have ground to a halt under COVID-19 lockdown policies, Netflix expects to consume roughly $1 billion of free cash in 2020, followed by larger content production expenses in 2021.

    The key to unlocking positive cash flows is indeed found in wider profit margins. Here’s how Netflix’s operating margins and cash profit margins have developed over the last three years:

    NFLX Operating Margin (TTM) Chart

    NFLX Operating Margin (TTM) data by YCharts

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    NEW! 5 Cheap Stocks With Massive Upside Potential

    Our experts at The Motley Fool have just released a FREE report detailing 5 shares you can buy now to take advantage of the much cheaper share prices on offer.

    One is a diversified conglomerate trading 40% off it’s all time high, all while offering a fully franked dividend yield of over 3%…

    Another is a former stock market darling that is one of Australia’s most popular and iconic businesses. Trading at a significant discount to its 52-week high, not only does this stock offer massive upside potential, but it also trades on an attractive fully franked dividend yield of almost 4%.

    Plus, this free report highlights 3 more cheap bets that could position you to profit in 2020 and beyond.

    Simply click here to scoop up your FREE copy and discover the names of all 5 cheap shares.

    But you will have to hurry because the cheap share prices on offer today might not last for long.

    YES! SEND ME THE FREE REPORT!

    Returns as of 7/4/2020

    More reading

    Anders Bylund owns shares of Netflix. The Motley Fool owns shares of and recommends Netflix. The Motley Fool has a disclosure policy. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. owns shares of and recommends Netflix. The Motley Fool Australia has recommended Netflix. We Fools may not all hold the same opinions, but we all believe that considering a diverse range of insights makes us better investors. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

    The post Will Netflix Be a $520 Stock? appeared first on Motley Fool Australia.

    This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.

    from Motley Fool Australia https://ift.tt/2WW563T