Author: openjargon

  • The RBA could hike rates in September. Which ASX shares are most at risk?

    Investor scratching his head.

    ASX shares have spent 2026 climbing a wall of worry, and interest rates remain the tallest brick in it.

    The Reserve Bank of Australia left the cash rate at 4.35% on 11 August, the central bank’s next decision is due on 29 September.

    For the first time in this cycle, the debate is no longer about when rates fall, but whether they begin to rise again.

    Why a September hike is suddenly plausible

    The Reserve Bank has not been subtle about its bias.

    In its August statement, the Board spelled out exactly what would happen if inflation misbehaves.

    The Board will continue to do what it considers necessary to bring inflation sustainably back to target, including increasing the cash rate target further if upside risks materialise.

    The data since has not helped its case for patience.

    Annual headline inflation eased to 3.5% in July, but the trimmed mean measure the Board watches most closely came in higher at 3.6%.

    Household spending rose 1.1% in the month and 7% across the year.

    Morgan Stanley now expects a hike in September, although Westpac chief economist Luci Ellis is less convinced and sees November as the more likely date.

    The ASX shares most exposed to higher rates

    Not every sector feels a rate rise the same way.

    Let’s focus on bank stocks.

    Higher rates lift deposit costs, slow credit growth, and eventually show up in arrears.

    Long-duration assets are the second group, because a higher discount rate reduces the present value of earnings that only arrive years from now.

    Commonwealth Bank of Australia (ASX: CBA) is a good case study.

    The shares closed last week at $157.25 and are down about 1% for the calendar year.

    Morgans has a sell rating on the bank.

    Analyst Damien Nguyen was blunt about the valuation:

    Despite these headwinds, the stock trades at a significant premium to its peers and historical valuations.

    A rate rise would not break CBA, but it would test a share price that has priced in near perfection.

    Goodman Group and the duration problem

    Goodman Group (ASX: GMG) is another example of how rate hikes can impact ASX stocks.

    The industrial property and data centre developer finished last week at $27.92, down roughly 10% for the year.

    The company’s FY26 operating profit rose 15.7% to $2.675 billion, and work in progress reached $19.7 billion across 50 projects in twelve countries.

    Occupancy held at 95.6%, and management is targeting 9% earnings per share growth in FY27.

    The operating business is clearly performing.

    But the unit price still struggles when bond yields rise, because a development pipeline stretching years into the future is worth less when money costs more.

    That is the trade-off investors accept when they buy growth-heavy property exposure.

    What this means for ASX shares more broadly

    A single hike would not derail the market.

    The S&P/ASX 200 Index (ASX: XJO) is still up 4% this calendar year and sits only a few percentage points below the record 9,296 points reached on 6 August.

    Miners and healthcare names have carried much of that gain, and neither group is especially rate-sensitive.

    The risk here is concentrated rather than general.

    Foolish takeaway

    I do not think investors should rebuild an entire portfolio around one meeting.

    The Reserve Bank may well hold again, and Ellis makes a reasonable case that November is the more likely month.

    But it is worth knowing which of your ASX shares you own for their yield today, and which you own for earnings that only arrive in 2030.

    Those two groups behave very differently when the cash rate moves higher.

    A September hike would be uncomfortable for banks and long-duration property, and largely irrelevant for a good deal of the rest of the market.

    The post The RBA could hike rates in September. Which ASX shares are most at risk? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Commonwealth Bank Of Australia right now?

    Before you buy Commonwealth Bank Of Australia shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Commonwealth Bank Of Australia wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Mark Verhoeven has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Goodman Group. The Motley Fool Australia has recommended Goodman Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Don’t panic if these 9 ASX 200 shares fall today

    A man sitting at a computer is blown away by what he's seeing on the screen, hair and tie whooshing back as he screams argh in panic.

    A number of S&P/ASX 200 Index (ASX: XJO) shares could open lower on Tuesday, but that doesn’t necessarily mean anything has gone wrong.

    9 ASX 200 companies are trading ex-dividend today, which means anyone buying the shares from this point won’t receive the latest dividend.

    This can often lead to the share price dropping by roughly the value of the dividend. But keep in mind that other market movements can still push the shares higher or lower on the day.

    According to The Australian, the combined ex-dividend moves are expected to shave around 6 points from the ASX 200 today.

    So, which shares should investors be watching?

    The ex-dividend moves to watch today

    Fortescue Ltd (ASX: FMG) shares finished Monday at $17.70 and are trading ex-dividend for a fully franked 46 cents per share payout.

    The dividend is due to be paid on 29 September.

    Wesfarmers Ltd (ASX: WES) shares closed at $79.44 and are going ex-dividend for a fully franked $1.20 per share dividend, with payment scheduled for 7 October.

    Woolworths Group Ltd (ASX: WOW) shares ended Monday at $40.31. The supermarket giant is trading ex-dividend for a fully franked 52 cents per share, payable on 25 September.

    Bendigo and Adelaide Bank Ltd (ASX: BEN) is another one to watch. Its shares closed at $10.73 and are going ex-dividend for a fully franked 33 cents per share payout, due on 30 September.

    Five more ASX 200 shares join the list

    Worley Ltd (ASX: WOR) shares finished Monday at $10.22 and are trading ex-dividend for an unfranked 25 cents per share dividend. Payment is due on 30 September.

    Endeavour Group Ltd (ASX: EDV) shares closed at $3.14. Its latest dividend is much smaller at 1.2 cents per share, fully franked, and will be paid on 1 October.

    Domino’s Pizza Enterprises Ltd (ASX: DMP) shares ended Monday at $20.86 and are trading ex-dividend for an unfranked 32.5 cents per share payout, due on 30 November.

    Magellan Financial Group Ltd (ASX: MFG) shares closed at $8.98. Its fully franked 25.5 cents per share dividend is going ex-dividend today and is scheduled to be paid on 16 September.

    Finally, Codan Ltd (ASX: CDA) shares finished Monday at $46.97 and are going ex-dividend for a fully franked 29 cents per share payout, also due on 16 September.

    What should investors expect today?

    The main thing to note is that any early weakness in these shares may simply reflect the dividend coming out of the share price.

    So, if any of these 9 ASX 200 shares open lower today, I wouldn’t read too much into the move straight away.

    The post Don’t panic if these 9 ASX 200 shares fall today appeared first on The Motley Fool Australia.

    Wondering where you should invest $1,000 right now?

    When investing expert Scott Phillips has a stock tip, it can pay to listen. After all, the flagship Motley Fool Share Advisor newsletter he has run for over ten years has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    Scott just revealed what he believes could be the ‘five best ASX stocks’ for investors to buy right now. We believe these stocks are trading at attractive prices and Scott thinks they could be great buys right now…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Domino’s Pizza Enterprises and Wesfarmers. The Motley Fool Australia has positions in and has recommended Bendigo And Adelaide Bank. The Motley Fool Australia has recommended Domino’s Pizza Enterprises and Wesfarmers. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • BHP shares are pulling back from a record high. What now for ASX investors?

    Business people standing at a mine site smiling.

    BHP shares are pulling back from a record high, and after the year shareholders have enjoyed, a breather was probably overdue.

    BHP Group Ltd (ASX: BHP) closed on Monday at $66.23, down from an all-time high of $68.77 last week.

    That still leaves Australia’s largest listed company up roughly 44% in 2026 and close to 56% over the past twelve months.

    With such strong results, is there space left for BHP shares to go further?

    How the FY26 results impacted BHP shares

    BHP handed down its full-year result in late August, and the numbers are behind much of the recent share price strength.

    Attributable profit came in at US$9.8 billion, up 9% on the prior year. Revenue rose 15% to US$58.8 billion.

    Underlying earnings before interest, tax, depreciation and amortisation landed at roughly US$33 billion, while net debt finished the year below US$9 billion.

    The results become interesting when we look at the split between BHP’s divisions.

    Copper contributed US$18.2 billion of underlying EBITDA, a 48% increase, and accounted for 54% of group earnings.

    That is the first time copper has out-earned iron ore across a full financial year.

    BHP produced around 2 million tonnes of copper for a second consecutive year, and it is now targeting roughly 40% production growth by FY35 through projects in Australia, Chile and Argentina.

    Why brokers are cautious on BHP shares

    Here is the awkward part.

    The share price has run well past where most analysts think it should sit.

    Consensus data puts the average twelve-month target at $58.68 across 14 analysts, roughly 10% below the current price.

    There is one buy rating, twelve holds and a single sell.

    Morgan Stanley is the most positive at $67.50, while Morgans sits at $55.30 and Deutsche Bank at $51.

    Not everyone is bearish.

    Morgans analyst Damien Nguyen still sees a clear case for owning the miner:

    BHP offers exposure to a portfolio of high quality mining assets and remains well positioned to benefit from long term demand for copper and other critical minerals.

    The stock trades on a price-to-earnings ratio of a little over 24, which is expensive by its own historical standards.

    The dividend, and the September question

    Income investors have a decision to make this week.

    BHP declared a final fully franked dividend of 99 US cents per share, or about A$1.392.

    The shares trade ex-dividend on Thursday 3 September, with payment due on 23 September.

    Together with the interim payment, that takes FY26 distributions to $2.431 per share and the fully franked yield to about 3.7%.

    There is also a seasonal wrinkle worth knowing about.

    September has historically been the weakest month of the year for the Australian market, with the S&P/ASX 200 Index (ASX: XJO) averaging a 0.94% decline since 1992 and finishing higher only 32% of the time.

    Foolish takeaway

    I would not chase BHP shares at this level, but I would be equally reluctant to sell them.

    The valuation is full, the broker targets sit below the share price, and this month being September could be a bad omen.

    Against that, the copper transition is BHP’s next growth lever, the balance sheet is in good shape, and the cash keeps arriving.

    Owning a world-class asset base at a fair price has usually worked out better than trying to time the last 10% of a rally.

    As such, for long-term holders, BHP shares still look like a business worth owning rather than a trade worth exiting.

    The post BHP shares are pulling back from a record high. What now for ASX investors? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BHP Group right now?

    Before you buy BHP Group shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BHP Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Mark Verhoeven has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has recommended BHP Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Liontown enters Argentina lithium brine farm-in, diversifying future growth

    Miner and company person analysing results of a mining company.

    The Liontown Ltd (ASX: LTR) share price is in focus after the company revealed a strategic farm-in agreement to acquire up to 100% of the Centenario lithium brine project in Argentina, bolstering its existing hard-rock lithium operations in Western Australia.

    What did Liontown report?

    • Entered a farm-in agreement with NEXT Lithium Corp. for the Centenario lithium brine project in Salta, Argentina
    • Potential to earn up to 100% interest in the project by funding US$40 million (~A$56 million) over four years, plus milestone payments
    • Initial payment will be US$5 million (~A$7 million) in cash and US$10 million (~A$14 million) in Liontown shares
    • An initial work program of US$15 million is planned over the first 12–24 months, targeting early-stage exploration and drilling
    • Staged structure allows Liontown to increase its project stake based on funding and exploration outcomes

    What else do investors need to know?

    The project is situated in a promising lithium brine district, close to established operations run by sector giants like Lithium Argentina, Ganfeng, and Eramet. This move offers Liontown a low-cost foothold in a globally significant lithium province and aligns with its strategy to diversify and grow its battery minerals portfolio.

    Partnering with NEXT Lithium gives Liontown access to the expertise of a team with a strong track record in Argentinian lithium brine assets. Liontown retains capital discipline through the staged investment and maintains Kathleen Valley as its core focus.

    The agreement includes standard conditions precedent, such as the release of security interests over the project and the repayment of certain intercompany loans. If these are not satisfied within six months, either party may walk away without further liability.

    What did Liontown management say?

    Managing Director and CEO Tony Ottaviano said:

    This transaction gives Liontown a low-cost entry into lithium brine. Brine is one of the two primary sources of the world’s lithium, and this is our first step in building real understanding and capability in it. Structuring the deal as a staged farm-in ties our capital to results, so we invest more only as the project proves itself. Kathleen Valley remains our priority, and we will keep pursuing value-accretive growth where it fits our strategy. NEXT Lithium knows lithium, knows brine, and knows Argentina. That depth of expertise is exactly what we want alongside us as we build our own capability.

    What’s next for Liontown?

    Liontown plans to launch initial exploration at Centenario, with a US$15 million program over the first two years, including drilling and geophysical testing. As results come in, the company can opt to boost its ownership through further staged investments, up to full control of the project.

    The Centenario farm-in is designed to complement Liontown’s hard-rock operations, providing diversified growth options and access to both major sources of lithium worldwide. Management remains committed to carefully scaling exposure in step with exploration outcomes and market conditions.

    Liontown share price snapshot

    Over the past 12 months, Liontown shares have risen 35%, outperforming the S&P/ASX 200 Index (ASX: XJO), which has risen 2% over the sme period.

    View Original Announcement

    The post Liontown enters Argentina lithium brine farm-in, diversifying future growth appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Liontown right now?

    Before you buy Liontown shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Liontown wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Laura Stewart has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips. This article was prepared with the assistance of Large Language Model (LLM) tools for the initial summary of the company announcement. Any content assisted by AI is subject to our robust human-in-the-loop quality control framework, involving thorough review, substantial editing, and fact-checking by our experienced writers and editors holding appropriate credentials. The Motley Fool Australia stands behind the work of our editorial team and takes ultimate responsibility for the content published by The Motley Fool Australia.
  • Betashares launches 3 new diversified ASX ETFs

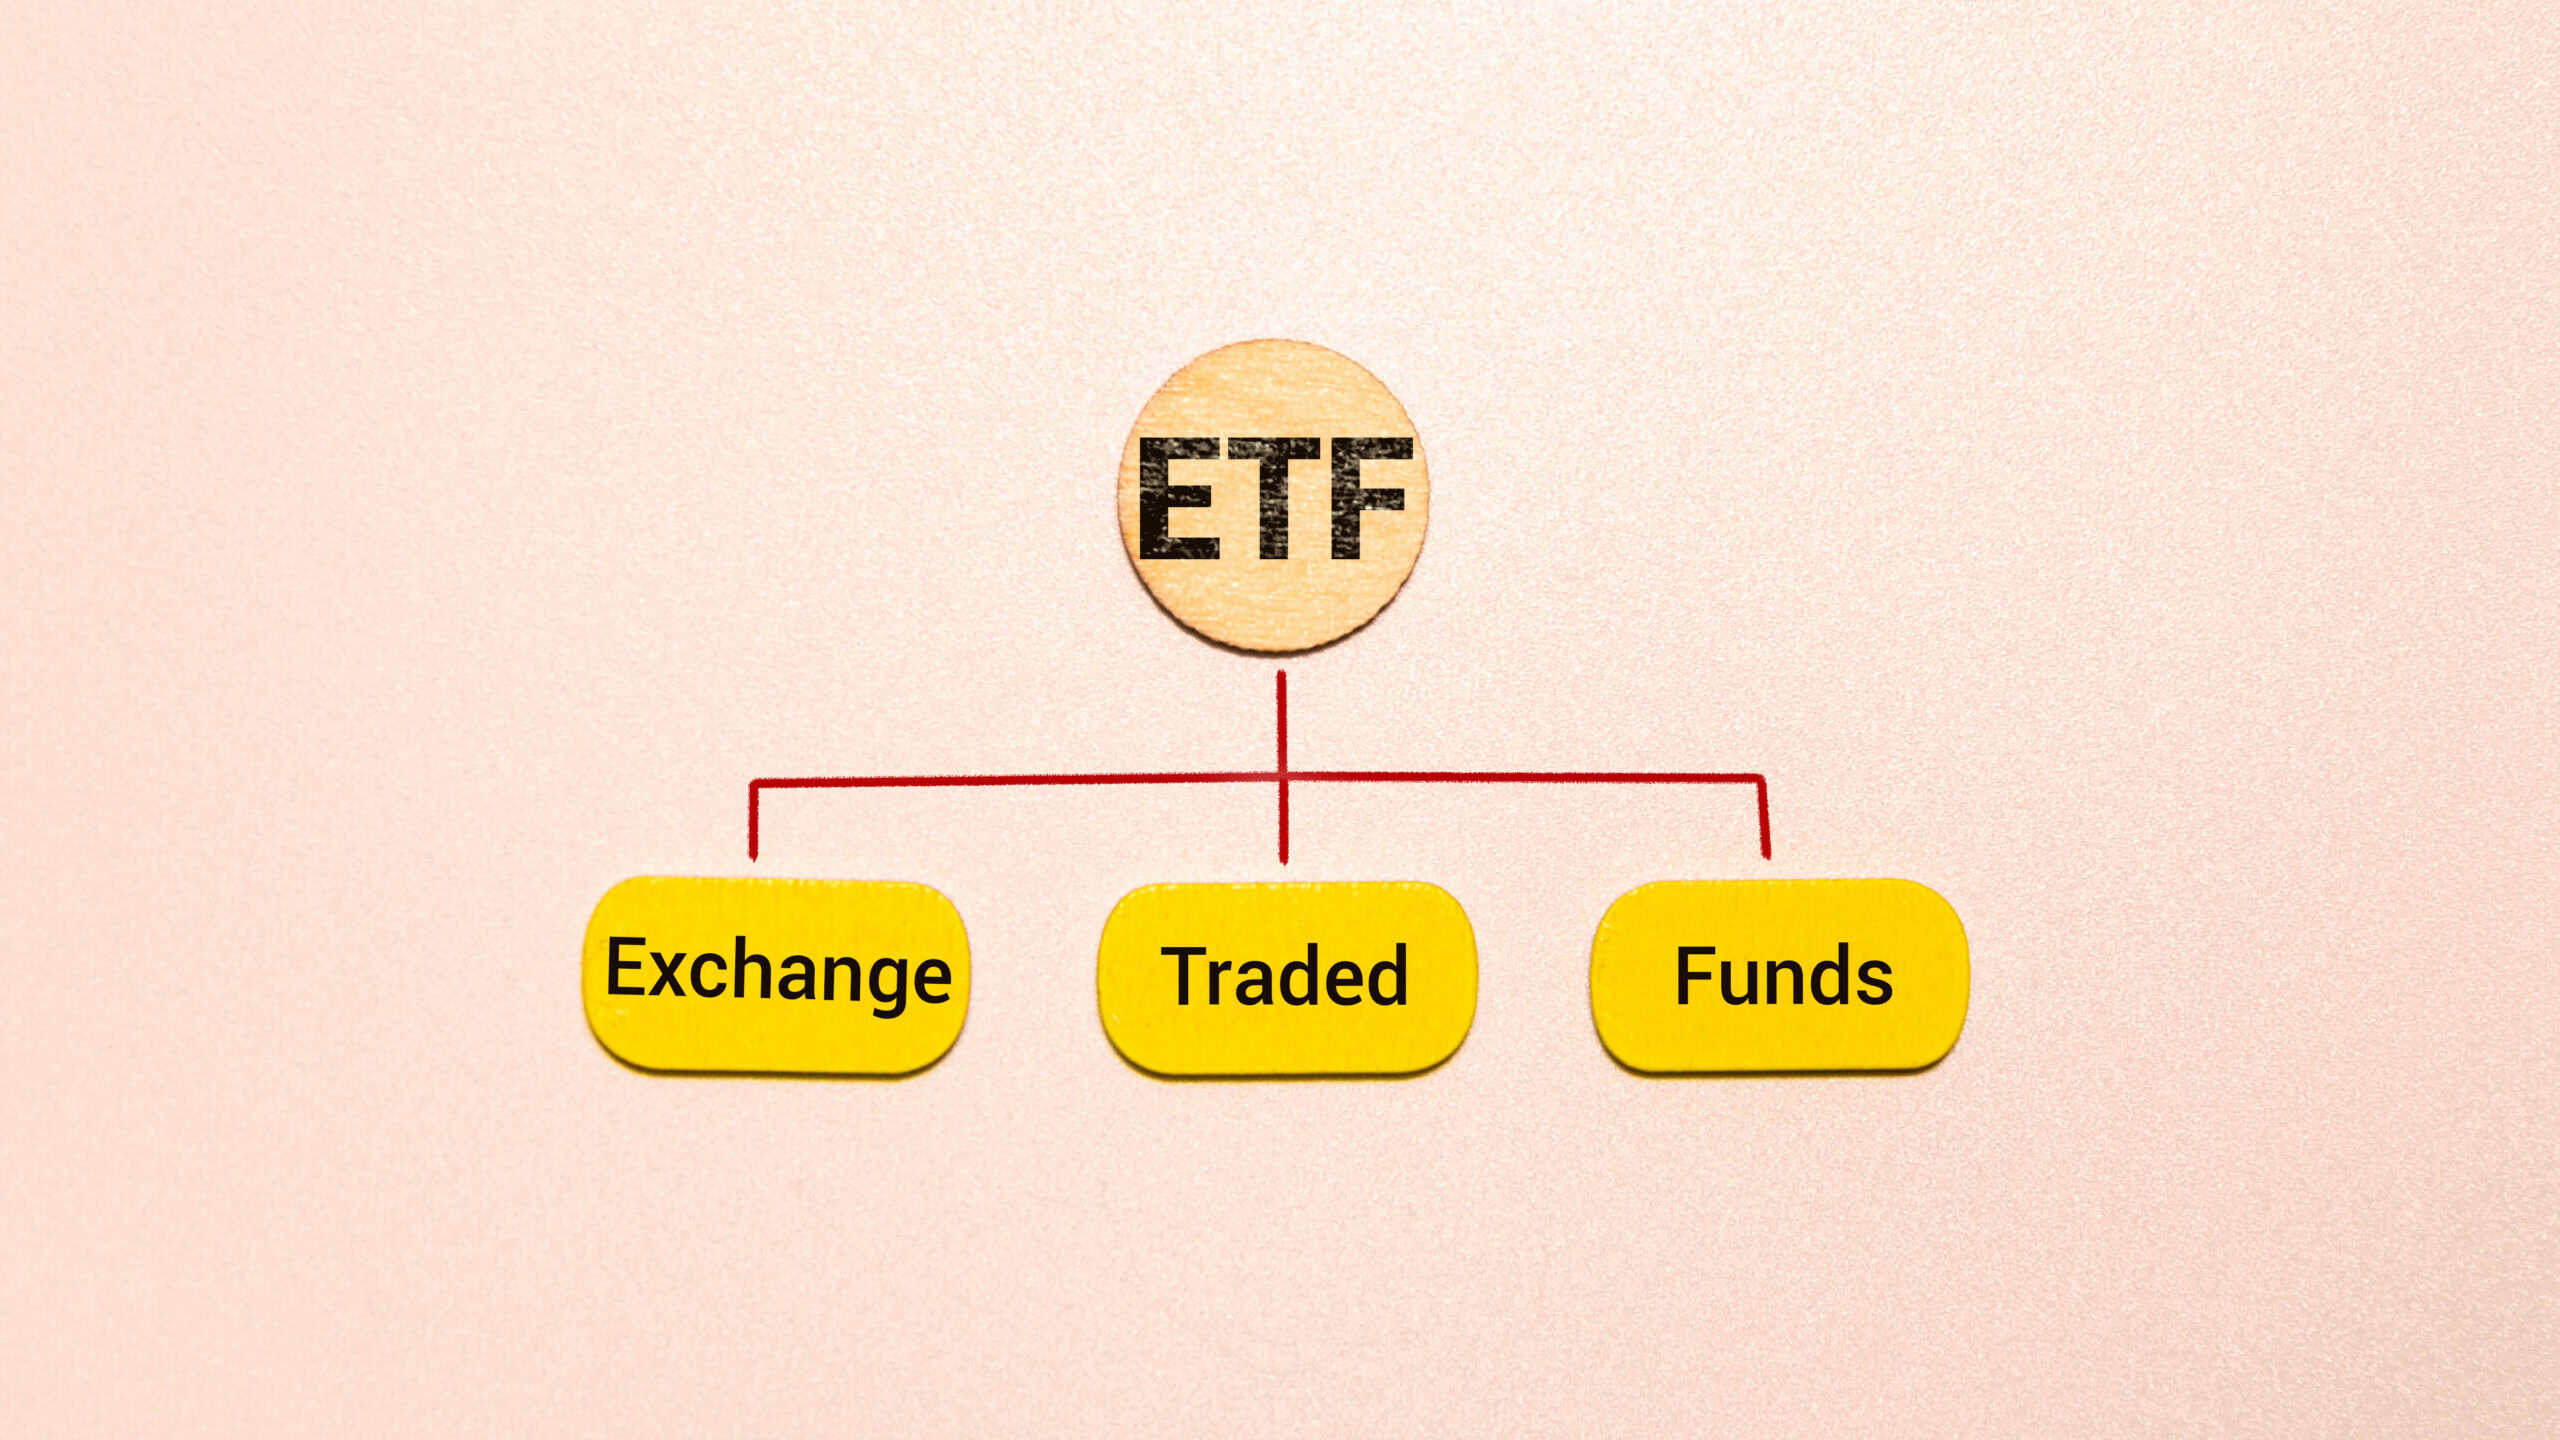
    Exchange traded fund in yellow bubbles, underneath red lines with ETF in black and a light brown circle above.

    The team at Betashares has released three new ASX ETFs this week. 

    The diversified multi-asset ETFs provide professionally constructed exposure across equities, fixed income, cash and infrastructure. 

    The three new funds offer balanced, growth and high-growth risk profiles.

    What are diversified ASX ETFs?

    ASX ETFs are fast becoming one of the most popular assets for Aussie investors. 

    Traditionally, investors used ETFs to track broad indexes like the S&P/ASX 200 Index (ASX: XJO) or the S&P 500 Index (SP: .INX). 

    However providers are now developing more sophisticated and thematic options. 

    One such sector of ASX ETFs is diversified funds. 

    Diversified ETFs have become an increasingly popular route for investors to access professionally constructed portfolios in a single trade. 

    By combining multiple asset classes and thousands of underlying securities within one fund, they can offer a simple and scalable alternative to constructing and maintaining a multi-asset portfolio.

    In simple terms, it can combine Australian shares, international shares, emerging markets and fixed income, growth etc in one trade. 

    Betashares has expanded its Diversified ETF range to provide a simple, low-cost way to implement strategic asset allocation across a range of investor risk profiles.

    The three new funds from Betashares

    Yesterday, Betashares announced three new diversified funds: 

    • Betashares Diversified High Growth ETF (ASX:DVHG) – 90% Growth / 10% Defensive allocation. 
    • Betashares Diversified Growth ETF (ASX:DVGR) – 75% Growth / 25% Defensive allocation. 
    • Betashares Diversified Balanced ETF (ASX:DVBA) – 60% Growth / 40% Defensive allocation. 

    The Funds provide exposure to approximately 2,500 Australian and global companies and 12,000 bonds, with broad diversification across asset classes, regions and sectors. 

    According to Betashares, this can reduce the administration associated with managing multiple holdings, while providing either a simple standalone solution or a passive core to which smart beta or active strategies can be added.

    The Diversified Balanced ETF leans more heavily into cash and fixed income for their defensive characteristics, while the All Growth ETF invests only in equities, targeting long-term capital appreciation.

    All three funds come with a management fee of 0.19% p.a.

    More information about the funds can be found here. 

    What other diversified ASX ETFs are available?

    According to Betashares, Together with the existing Betashares Diversified All Growth ETF (ASX: DHHF), the range now provides investors with diversified portfolio options spanning balanced through to all growth profiles.

    For investors looking to compare the new funds with existing ETFs, there are others to consider, including: 

    • Vanguard Diversified High Growth Index ETF (ASX: VDHG)
    • Vanguard Diversified All Growth Index Etf (ASX: VDAL). 

    The post Betashares launches 3 new diversified ASX ETFs appeared first on The Motley Fool Australia.

    Should you invest $1,000 in BetaShares Diversified All Growth ETF right now?

    Before you buy BetaShares Diversified All Growth ETF shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and BetaShares Diversified All Growth ETF wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Aaron Bell has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Down 28% to 46%: Are these beaten-down ASX shares cheap buys?

    Elderly couple using laptop at home while drinking a cup of coffee.

    If you are in the market for a bargain, then it could be worth hearing what Bell Potter is saying about the beaten-down ASX shares in this article.

    Are they cheap buys? Let’s find out:

    Austal Ltd (ASX: ASB)

    This ASX share is down 46% over the past 12 months. 

    Unfortunately, Bell Potter isn’t in a rush to buy the shipbuilder’s shares after this decline. In response to its results, the broker has retained its hold rating with a trimmed price target of $4.70. It explains:

    Hanwha’s knowledge of recent onerous contracts prior to bid submission suggests a higher likelihood of the deal going ahead. We forecast FY27e sole Australasian EBIT (incl corp. costs) of $32m ($44m normalised in FY26e) implying current multiple of 10- 17x if bid goes ahead vs. global peer group at 16-24x. We believe ramp-up risks are heightened in the Australasian segment over the next 2 years with labour the key constraint. Retain Hold. TP lower on model roll forward.

    Harvey Norman Holdings Ltd (ASX: HVN)

    Bell Potter remains positive on retail giant Harvey Norman, which has seen its shares fall 43% since this time last year.

    However, the broker has taken an axe to its valuation following a review of the company’s FY 2026 results. A note reveals that it has retained its buy rating on the ASX share with a reduced price target of $5.00 (from $6.00). It commented:

    In HVN’s key Australian market, we see near term pressures with a further challenged operating environment and a period of high comps navigated through Sep-Nov. However, HVN has the second highest global exposure within our coverage, while trading at a 1-year forward P/E of ~14x (as per BPe). We view this as reasonable considering the CY27/28 outlook for the name with the growth opportunity in 8 global markets and as Australia’s single largest owner in large format retail with a global portfolio of ~$4.8b.

    Praemium Ltd (ASX: PPS)

    This investment platform provider’s shares are down 28% from their highs, and Bell Potter appears to believe this has created a buying opportunity.

    According to the note, the broker has retained its buy rating on the company’s shares with a trimmed price target of $1.10 (from $1.20). It said:

    . We stay Buy rated. Derecognising assets is a setback. However, PPS has flagged an intention to migrate onto its new system over the coming 12-18 months. We see an untapped potential in superannuation and new client wins beginning to convert into revenue.

    The post Down 28% to 46%: Are these beaten-down ASX shares cheap buys? appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Austal right now?

    Before you buy Austal shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Austal wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Praemium. The Motley Fool Australia has positions in and has recommended Harvey Norman. The Motley Fool Australia has recommended Praemium. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Why Liontown shares could be dirt cheap

    Happy businessman fist pumping while looking at a tablet.

    Liontown Ltd (ASX: LTR) shares have been strong performers over the past 12 months.

    During this time, the lithium miner’s shares have risen 35%.

    Despite this, one leading broker believes that the company’s shares could be dirt cheap.

    What is the broker saying?

    According to a note out of Bell Potter, its analysts felt that Liontown delivered a “solid” result in FY 2026. The broker said:

    LTR reported FY26 underlying EBITDA of $147m (BP est. $222m) and NPAT of $14m (BP est. -$3m). Statutory NPAT was $93m, includes a net -$44.3m tax effected charge for fair value movements and FX gain related to the convertible notes issued to LG Energy Solution, and the recognition of a $112.9m deferred tax asset for tax losses carried forward from prior years. LTR did not declare a dividend, as expected. 

    The FY26 result was symptomatic of the Kathleen Valley ramp-up, with high depreciation associated with completing the open pit in late 2025. As previously reported, LTR finished FY26 with cash of $561m and debt of $369m (excluding leases) implying a net cash position of $192m.

    Looking ahead, Bell Potter highlights that management is working towards a final investment decision (FID) for the Kathleen Valley mine and processing plant expansion, with a decision due in the near term. It said:

    LTR intends to take a formal Final Investment Decision (FID) on the Kathleen Valley mine and processing plant expansion in late September 2026. The expansion is designed to lift underground mining and processing throughput from 2.8Mtpa to 4.0Mtpa, thereby lifting concentrate production capacity from around 500ktpa to over 700ktpa. In today’s release, LTR reiterated FID remains on track for end of Q1 FY27.

    Are Liontown shares dirt cheap?

    Bell Potter believes that Liontown shares are unnecessarily cheap, highlighting that its enterprise value (EV) is trading at a level not seen since lithium prices were significantly cheaper and its debt load was higher. It said:

    We still believe that LTR’s EV is lagging the recent recovery in lithium markets and expected tight fundamentals. The last time LTR was trading at its current EV (early December 2025), SC6 prices were US$1,150/t and net debt was $274m. Since this date. Since then, the Kathleen Valley underground ramp-up has been further derisked and spot SC6 prices are above US$2,300/t. 

    While we expect lithium markets will be volatile, market fundamentals remain strong. Over FY27, LTR will continue to ramp up and de-risk Kathleen Valley, a highly strategic asset in terms of scale, long project life and location in a tier-one mining jurisdiction.

    In response to the company’s results, the broker has retained its buy rating and $1.90 price target on Liontown’s shares.

    Based on its current share price of $1.23, this implies potential upside of approximately 55% for investors over the next 12 months.

    The post Why Liontown shares could be dirt cheap appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Liontown right now?

    Before you buy Liontown shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Liontown wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • By September 2027, $5,000 invested in Macquarie shares could turn into…

    A cool young man walking in a laneway holding a takeaway coffee in one hand and his phone in the other reacts with surprise as he reads the latest news on his mobile phone

    Macquarie Group Ltd (ASX: MQG) shares have stormed higher in 2026, with robust financial results and a series of positive announcements continuing to drive positive investor sentiment.

    At the close of the ASX on Monday afternoon, the investment bank’s shares were down around 0.5% to $250.59.

    Despite the small decline, the shares are still up 23% for the year-to-date and are 12% higher than 12 months ago.

    What do investors like about Macquarie Group?

    At the time of writing, Macquarie is Australia’s fifth-largest bank by market capitalisation, and the sixth largest stock listed on the S&P/ASX 200 Index (ASX: XJO). 

    But Macquarie is more than just an ASX bank stock. It provides services across a diverse range of markets.

    Aside from banking, Macquarie Group also operates across asset management, commodities and financial markets, advisory, investment, and fund management services across 34 markets globally.

    Through most of the year so far, the investment bank has performed strongly, rallying strongly in April and reaching an all-time high in early-August.

    In late July, the company had its AGM, posted its first-quarter FY27 update, and announced that CEO Shemara Wikramanayake will retire in November, with Greg Ward to take over the top job.

    Macquarie described trading conditions during the first quarter as “satisfactory”. Its Banking and Financial Services segment increased its profit contribution compared with the same period last year. Deposits rose by 4% during the quarter, while home loans grew by 6% and business banking loans increased by 3%.

    The news came on the back of the company’s positive earnings results back in May. At the time, Macquarie reported a full-year FY26 net profit of $4.85 billion, up 30% from FY25, and growth across all four of its operating divisions.

    The rally of good news was very well received by the market, and many rushed to snap up the shares.

    The question now is, can Macquarie keep climbing higher? Or have the shares reached a ceiling?

    If I buy $5,000 of Macquarie shares today, what could they be worth in 12 months time?

    Analysts are pretty optimistic about the outlook for Macquarie over the next year. 

    Market Index data shows that the majority of brokers have a buy rating on the shares. The $270.89 average target price implies 8% potential upside at the time of writing. 

    TradingView data shows something similar. Again, the majority (nine out of 12) also have a buy/strong buy rating on the shares. The average $268.69 target price implies a potential 7% upside ahead. 

    The team at Catapult Wealth have a buy rating on the investment bank. The wealth management company thinks Macquarie shares are a good alternative to the big four banks in the current environment.

    Jarden has a buy rating on Macquarie shares, but thinks the stock is now fully priced. It has a price target of $250, just a little above the current share price.

    Morgans also thinks the shares are close to being fully valued. The broker has a hold rating and a $255 target price. It said that Macquarie is a quality franchise and a proven performer, but is overvalued.

    Assuming the average price target comes to fruition within the next 12 months, that means a $5,000 investment today could be worth between $5,350 and $5,400 this time next year.

    The post By September 2027, $5,000 invested in Macquarie shares could turn into… appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Macquarie Group right now?

    Before you buy Macquarie Group shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Macquarie Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Samantha Menzies has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Macquarie Group. The Motley Fool Australia has recommended Macquarie Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.
  • Why PLS shares rocketed 30% in August

    Man smiling ahead while working on his MacBook.

    PLS Group Ltd (ASX: PLS) shares were among the best performers on the S&P/ASX 200 index (ASX: XJO) in August.

    During the month, the lithium giant’s shares surged 30% to end the period at $5.40.

    This means the company’s shares are now up a remarkable 120% over the past 12 months.

    Why did PLS shares rocket in August?

    Investors were fighting to get hold of PLS shares following the release of its FY 2026 results.

    For the 12 months ended 30 June, the lithium miner reported a 152% increase in revenue to $1,934 million. 

    This was driven by a 17% increase in sales volumes to 891.6kt and a 121% jump in its average estimated realised price to US$1,488 per tonne.

    Another positive was that its unit operating cost (FOB) improved by 9% to $569/t (US$386/t), which management advised reflects higher volumes and ongoing operational improvements.

    This ultimately underpinned a more than 1,000% increase in underlying EBITDA to $1,137 million (from $97 million) and a net profit after tax of $526 million, which was up from a $196 million loss a year earlier.

    The good news for shareholders is that this allowed the PLS board to bring back its dividend. It is paying shareholders a 5 cents per share fully franked dividend for the half.

    Commenting on the results, PLS’ CEO, Dale Henderson, said:

    FY26 was a record year for PLS, demonstrating our through-cycle strategy in action. We had positioned the business to respond quickly when market conditions improved and, as the lithium market strengthened, we acted – bringing idled capacity back into production and shifting our focus decisively from defence to growth. That preparation is reflected in the results. We delivered record production of approximately 880 thousand tonnes while reducing unit operating costs by 9%, generating $1.1 billion of underlying EBITDA at a 59% margin and $1.4 billion of cash margin from operations. These are strong outcomes and a credit to our team. 

    With 100% ownership of Pilgangoora, our shareholders receive the full benefit of the scale, low-cost position and operating leverage we have built. We also strengthened the business for what comes next. During the year we accessed the international debt capital markets for the first time through our US$600 million bond and finished FY26 with $2.3 billion of cash. That financial strength gives us flexibility: we can continue investing in Pilgangoora, bring Ngungaju back into production, advance P2000 and Colina, and pay a fully franked final dividend of 5 cents per share. 

    We enter FY27 larger, lower cost and financially stronger than we were a year ago. We remain confident in the long-term opportunity for lithium, and our focus is on continuing to execute well, allocating capital with discipline and delivering value for our shareholders.

    Should you invest?

    According to a note out of Macquarie Group Ltd (ASX: MQG), its analysts still see value in PLS shares at current levels.

    In response to its FY 2026 results, the broker retained its outperform rating and $6.00 price target on its shares.

    Based on its current share price, this implies potential upside of approximately 11% for investors over the next 12 months.

    The post Why PLS shares rocketed 30% in August appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Pls Group right now?

    Before you buy Pls Group shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Pls Group wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Macquarie Group. The Motley Fool Australia has recommended Macquarie Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

  • This broker is tipping 33% upside for Megaport shares

    Two smiling colleagues looking at a tablet in a data centre.

    Following earnings results, the team at Ord Minnett is projecting big upside for Megaport Ltd (ASX: MP1). 

    Megaport provides on-demand data and network interconnection services across multiple continents. 

    It released full-year results on August 20. 

    Results exceeded expectations

    In yesterday’s report, Ord Minnett said Megaport’s FY26 earnings and FY27 guidance exceeded consensus estimates. 

    The company also announced three contract wins, together valued at $506 million. 

    These contracts will deliver annual recurring revenue of $129 million and start contributing in FY27. 

    For FY26, total revenues rose 37% to $312 million, in-line with consensus of $313 million, and within the provided guidance range of $307-315 million. 

    Earnings before interest, tax, depreciation and amortisation (EBITDA) increased 24% to $77 million, ahead of consensus at $72 million, and guidance of $64.5-75.5 million. 

    Guidance is for FY27 revenue of $620-$730 million (consensus: $619 million) and an EBITDA margin of 38-40%, which implies EBITDA in the range of $ 236- $ 292 million (consensus: $242 million). 

    Soft market reaction 

    Despite the positive results, Megaport shares actually fell significantly following the results. 

    Ord Minnett suggested this may have been influenced by several factors: 

    Some parts of the investment community had been expecting contract wins already, or more of a guidance uplift in guidance from GPU Pool monetisation. 

    We see guidance as prudent, and the EBITDA target is achievable purely on a conservative ramp-up of contracts without GPU Pool monetisation. EBITDA of over $300 million is possible with some GPU Pool monetisation on our analysis.

    ‍MP1 renegotiated two strategic contracts due to supply constraints. Despite this, the outcomes appear more favourable for MP1 given the alternative arrangements include providing higher-grade graphic processing units (GPU). This has increased total contract values in aggregate by US$87.1 million with no material change in aggregate annual recurring revenue or capex requirements.

    Big upside remains for Megaport shares

    The recent dip may have created a strong opportunity for value investors. 

    The team at Ord Minnett placed an accumulate rating and $22 price target on Megaport shares following results. 

    From yesterday’s closing price, this indicates an upside potential of approximately 33%. 

    Our EBITDA estimates fall by 11.2% in FY27 on higher expenses but increase 22.6% in FY28 on higher revenues from contract wins. Our target price is revised to $22.We have an Accumulate recommendation. Catalysts for the shares include upgrades to FY27 guidance and more contract wins.

    ‍

    The post This broker is tipping 33% upside for Megaport shares appeared first on The Motley Fool Australia.

    Should you invest $1,000 in Megaport right now?

    Before you buy Megaport shares, consider this:

    Motley Fool investing expert Scott Phillips just revealed what he believes are the 5 best stocks for investors to buy right now… and Megaport wasn’t one of them.

    The online investing service he’s run for over a decade, Motley Fool Share Advisor, has provided thousands of paying members with stock picks that have doubled, tripled or even more.*

    And right now, Scott thinks there are 5 stocks that may be better buys…

    * Returns as of 1 August 2026

    .custom-cta-button p {
    margin-bottom: 0 !important;
    }

    More reading

    Motley Fool contributor Aaron Bell has no position in any of the stocks mentioned. The Motley Fool Australia’s parent company Motley Fool Holdings Inc. has positions in and has recommended Megaport. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.